

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Network Telemetry Market to Hit $1.05B in 2025, 28.45% CAGR Through 2032

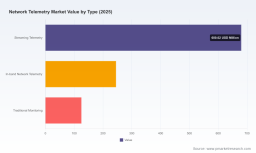
The Visibility Imperative: Strategic Intelligence for the Worldwide Network Telemetry Market 2026
Network operators, cloud architects, and enterprise IT leaders face a fundamental transformation in how infrastructure is observed, measured, and optimized. The era of periodic polling and reactive fault management has given way to continuous, model-driven telemetry that streams operational state in real time. Our latest Worldwide Network Telemetry Market research report maps this accelerating transition with precision, offering decision-makers a structured lens through which to evaluate technology roadmaps, capital allocation, and competitive positioning for 2026 and beyond.
The strategic value of this analysis lies not merely in tracking a fast-growing category, but in decoding the structural forces reshaping network observability. As software-defined architectures, cloud-scale data centers, and AI-driven operations converge, telemetry has evolved from a diagnostic utility into a core operational layer. Organizations that understand where the market is heading, which protocols and platforms are gaining traction, and how regulatory and cost pressures are reshaping deployment economics will be better positioned to modernize infrastructure without incurring avoidable risk or wasted investment.
A Market Defined by Acceleration and Structural Shift
The wholesale market for network telemetry has expanded rapidly over the past half-decade, reflecting the broad industry migration from legacy monitoring toward streaming, high-frequency observability. Historical revenue trajectories show a consistent upward climb from 2020 through 2025, with the base year reaching an estimated $1,050.5 million. The forecast window through 2032 projects continued robust expansion, with the market expected to surpass $1,272.8 million in 2026 and climb toward $6,060.91 million by the end of the forecast period. This growth is anchored by a forecast compound annual growth rate of 28.45 percent, a pace that signals both strong demand pull and an ongoing technology substitution cycle across enterprise and service provider environments.
Such momentum is not uniform across every slice of the market. Adoption intensity varies by organizational scale, industry vertical, deployment model, and regional maturity. Large enterprises continue to anchor a substantial share of demand, while smaller organizations are increasingly adopting telemetry as managed services and cloud-native analytics lower the barriers to entry. Likewise, certain technology approaches are gaining preference as operators consolidate around open, model-driven interfaces and streaming pipelines that integrate cleanly with analytics and AI workflows. The full segmentation breakdown, including regional revenue distribution and component-level splits, is detailed in the complete report for readers who require granular go-to-market and investment planning inputs.
Why 2026 Is a Pivotal Decision Year
For executives planning capital expenditure, vendor consolidation, and architecture modernization in 2026, several intersecting factors make timely intelligence essential. First, the protocol landscape is stabilizing around standards that reduce integration friction. The formalization of gNMI for model-driven network telemetry has given operators and vendors a common language for streaming operational data, which in turn is accelerating interoperability across multivendor environments. Second, regulatory dynamics are reshaping what data can be collected, how it must be handled, and which vendors can participate in specific markets. Compliance expectations around data minimization and privacy in certain regions, alongside evolving telecommunications policy in others, are influencing product design and deployment scope.
Third, infrastructure economics are becoming a more salient constraint. As telemetry pipelines scale, the energy and compute costs associated with ingestion, storage, and analytics are coming under greater scrutiny. With data center energy costs averaging roughly $0.12 per kilowatt-hour globally, organizations are increasingly weighing the operational cost of observability against its value in reducing downtime, improving utilization, and enabling automation. Fourth, geopolitical and trade developments are influencing hardware and software sourcing strategies, particularly where export controls affect the availability of certain platforms or components. These dynamics do not simply alter vendor choice; they reshape architecture decisions, data residency assumptions, and long-term scalability plans.
In this environment, a market map is not enough. Decision-makers need a structured assessment of how these forces combine to influence demand, pricing, deployment models, and competitive differentiation. That is the purpose of this research: to convert market movement into actionable strategy.
Vehicle Telematics Market
What the Report Delivers
This study is designed to support practical decision-making across strategy, procurement, architecture, and competitive intelligence functions. Rather than offering a high-level overview, it provides a multi-dimensional examination of the worldwide network telemetry market across historical performance, forward-looking forecasts, and the operational variables that shape adoption. The report combines top-down market sizing with Bottom-Up segmentation logic, allowing readers to cross-check aggregate trends against the realities of specific buyer groups and technology categories.
Key analytical components include a detailed assessment of market size and growth trajectories from 2020 through the 2032 forecast horizon, with emphasis on the inflection points that matter for planning cycles in 2026. The analysis examines demand by component, distinguishing between solutions and services, and by type, differentiating streaming telemetry, in-band network telemetry, and traditional monitoring approaches. It also evaluates adoption patterns across enterprise size categories and industry verticals, helping readers understand where deployment intensity is concentrated and why. Regional demand is contextualized through a combination of maturity indicators, infrastructure trends, and policy-related considerations, providing a grounded view of where growth is most likely to accelerate.
Beyond sizing, the report delivers a competitive landscape analysis that profiles the companies shaping the market, their technological approaches, and the strategic implications of recent product and protocol developments. It incorporates an assessment of market concentration, giving readers a clear sense of how consolidated the vendor base is and where opportunities for differentiation or displacement may emerge. The study also integrates market dynamics that influence execution risk, including standardization momentum, regulatory requirements, infrastructure cost pressures, and geopolitical considerations that affect supply and deployment options.
For practitioners, the report translates these insights into operational relevance. It discusses how telemetry pipelines are being designed for cloud-scale analytics, how model-driven approaches are enabling richer integration with AI and machine learning workflows, and how security-focused visibility is becoming part of the broader telemetry conversation. It also addresses the practical trade-offs that organizations face when balancing depth of visibility, data volume, processing cost, and compliance obligations.
Competitive Landscape: How the Leaders Are Shaping the Market
The worldwide network telemetry market is being shaped by a set of established networking vendors, silicon providers, and specialized analytics platforms, each pursuing distinct thesis about where observability delivers the most value. Several large networking vendors have built streaming telemetry capabilities directly into their operating systems and platforms, emphasizing model-driven approaches, open interfaces, and integration with broader analytics ecosystems. Cisco Systems has advanced Model-Driven Telemetry using gRPC and dial-out streaming across IOS XR, NX-OS, and Catalyst platforms to provide real-time network insights, and has continued to enhance those capabilities with updates designed to support AI and ML-driven analytics. Juniper Networks has pursued a similar trajectory through its Junos Telemetry Interface, offering high-frequency streaming of operational state via gNMI and IPFIX to analytics platforms, while also expanding configuration telemetry streaming support in recent operating system releases.
Arista Networks has focused on cloud-scale data center environments with EOS eAPI, gNMI telemetry, and CloudVision for state streaming and analytics, and has continued to extend developer-oriented tooling for custom telemetry pipelines. Nokia delivers telemetry in SR OS and 7750 SR routers using gNMI and gNOI for service provider networks, reinforcing its positioning in operator-focused deployments. Broadcom supports telemetry export in StrataXGS and Tomahawk switch ASICs, enabling merchant silicon deployments to participate in the broader observability ecosystem. Huawei integrates telemetry across NE series routers and iMaster NCE for end-to-end network observability, while Extreme Networks emphasizes Universal ZTP and Fabric Telemetry in VOSS and EXOS for wired and wireless network monitoring.
Security and application delivery vendors are also expanding their telemetry footprint. Palo Alto Networks provides PAN-OS telemetry streaming for security-focused network visibility and threat detection, while F5 Networks offers BIG-IP Telemetry Streaming using gRPC for application delivery and ADC monitoring. Alongside these vendor-led approaches, specialized platforms such as Kentik are building cloud-native analytics environments that ingest NetFlow, sFlow, IPFIX, and gNMI for network performance analytics, illustrating the growing convergence between network observability and data-driven operations.
Recent product and protocol developments underscore how quickly the landscape is evolving. Cisco released IOS XR 7.11.1 with enhanced gRPC telemetry for AI and ML model-driven analytics, reinforcing the link between streaming telemetry and advanced operations. Juniper added gNOI support in Junos OS 23.4R1 for configuration telemetry streaming, extending the scope of operational data beyond traditional performance metrics. Arista introduced EOS 4.34.1F with AVA developer tools for custom telemetry pipelines, reflecting an industry-wide push toward flexibility and programmability in how telemetry is consumed and transformed.
These developments matter because they influence not only product selection, but also architectural commitment. As vendors deepen support for open interfaces and streaming pipelines, organizations gain more options for multivendor integration, but they also face more complex evaluation criteria around scalability, data governance, analytics readiness, and long-term support. The report’s competitive analysis examines these trade-offs in detail, helping readers understand where consolidation is likely, where specialization remains valuable, and how market concentration is shaping bargaining dynamics.
Worldwide Network Telemetry Market
Market Dynamics: Standards, Regulation, Cost, and Geopolitics
The trajectory of the network telemetry market is being shaped as much by external conditions as by technology preferences. Standardization is a key enabler. The publication of IETF RFC 9232, which standardizes gNMI for model-driven network telemetry, has provided a shared reference point that reduces ambiguity for vendors and operators alike. This kind of standards alignment tends to accelerate procurement confidence, simplify integration planning, and support broader multivendor deployment models. At the same time, standards do not eliminate differentiation; they often shift competition toward analytics depth, operational simplicity, security integration, and service delivery models.
Regulatory and policy developments are equally consequential. In the United States, the reinstatement of net neutrality rules under Title II has implications for how ISPs must treat telemetry tools, including obligations not to block or throttle such traffic. In Europe, data protection obligations continue to influence how telemetry streams are collected and processed, with data minimization principles affecting design decisions for observability platforms operating in EU networks. These frameworks do not simply impose constraints; they shape product architecture, data handling practices, and the geographic feasibility of certain deployment models.
Cost pressure is another defining dynamic. Telemetry at scale generates significant data volumes, and the associated processing requirements can drive meaningful infrastructure and energy expense. With data center energy costs averaging around $0.12 per kilowatt-hour globally, organizations are increasingly examining whether their observability architectures are aligned with financial and sustainability targets. This has practical implications for retention policies, sampling strategies, edge versus central processing, and the choice between self-managed and service-based deployment models.
Geopolitical factors further complicate sourcing and architecture decisions. Export controls affecting certain hardware and software suppliers have introduced additional considerations for organizations building or expanding telemetry capabilities in restricted environments. These constraints can influence vendor selection, component availability, and the risk profile of long-term infrastructure plans. The report integrates these dynamics into a broader market analysis so that readers can assess not only where demand is growing, but also where execution risk may be elevated and how to plan around it.
How to Use This Research for 2026 Planning
For organizations preparing for 2026, the most valuable use of this research is as a decision-support framework rather than a static market snapshot. Procurement teams can use the segmentation and competitive analysis to refine vendor shortlists, compare solution and service models, and identify where consolidation or specialization is most likely to affect pricing and negotiation leverage. Architecture and operations leaders can use the technology and dynamic analysis to assess protocol alignment, integration requirements, and the cost implications of scaling telemetry across large environments. Strategy and corporate development teams can use the forecast trajectories and concentration analysis to evaluate market entry opportunities, partnership rationale, and the timing of investment decisions.
Because the market is expanding at a pace that rewards early alignment with emerging standards and analytics-ready architectures, the cost of delayed planning can be substantial. At the same time, the presence of multiple viable approaches means that organizations need to evaluate options in the context of their own operating model, compliance environment, and cost tolerance. This report is structured to support that evaluation by connecting market growth to the operational and strategic choices that determine outcomes.
Conclusion: Turning Market Momentum into Strategic Clarity
The worldwide network telemetry market is entering a phase in which growth, standardization, regulation, and cost dynamics are converging to redefine how organizations build and operate observable networks. The combination of strong forecast expansion, accelerating adoption of streaming and model-driven approaches, and an increasingly active competitive field makes 2026 a critical year for strategic planning. Our full research report provides the detailed market sizing, segmentation logic, competitive profiling, and dynamic analysis needed to navigate that environment with confidence.
For decision-makers who require segment-level demand breakdowns, regional revenue distributions, component-level market values, and company-specific competitive assessments, the complete study offers the depth necessary to support procurement, architecture, and strategy decisions. The insight preview above is intended to establish the strategic context; the full report delivers the actionable intelligence required to act on it.
For detailed analysis of this topic, please visit the official page: Worldwide Network Telemetry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com