

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Aircraft Brake Calipers Market Hits $592.28M in 2025, Expands to $1,022.99M by 2032 at 8.12% CAGR

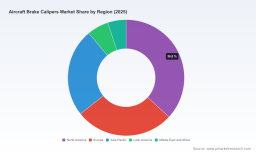
Strategic Imperatives in the Global Aircraft Brake Calipers Market: A 2026 Outlook
The aerospace supply chain is currently navigating a period of intense transformation, driven by the dual engines of post-pandemic commercial aviation recovery and renewed military modernization programs. At the heart of this mechanical ecosystem lies a component critical to safety, performance, and operational economics: the aircraft brake caliper. As aircraft manufacturers push for lighter, more efficient airframes and airlines prioritize turnaround times and maintenance reliability, the braking system market has emerged as a focal point for strategic investment and procurement planning.
In this context, the newly released Worldwide Aircraft Brake Calipers Market research report serves as an essential intelligence asset for stakeholders aiming to navigate the complexities of 2026. This market overview provides a high-level strategic snapshot of where the industry stands today and where it is trajectory-bound over the next decade, highlighting the macroeconomic forces and competitive pressures that will define decision-making in the near future.
Market Trajectory and Economic Scale
The financial landscape of aircraft brake calipers reflects the broader health of the aerospace sector. Over the historical period from 2020 to 2025, the market demonstrated robust resilience and steady expansion, overcoming supply chain disruptions and material cost volatilities. The base year valuation for 2025 encapsulates the mature state of current demand, setting a solid foundation for the forecast period extending through 2032.
Looking forward, the market is poised for significant growth. The projected trajectory indicates that market revenue is expected to climb into the range of over one billion USD by the end of the forecast window. This trajectory is underpinned by a compound annual growth rate that reflects sustained demand across both commercial and defense sectors. The growth is not merely linear; it is fueled by technological shifts in actuation systems and the increased utilization rates of aging fleets that require consistent component replacement. For procurement officers and financial analysts, understanding this top-line growth is only the starting point. The true value lies in dissecting the drivers behind these numbers, which are detailed extensively within the full report.
Worldwide Aircraft Brake Calipers Market
Brake Calipers Market
- The market captures value through complex interactions between liquidity in fleet expansion and the regulatory lifecycle of existing aircraft.
- Revenue indicators suggest a shift toward higher-value components as material technologies evolve.
- Forecast models account for the varying pacing of regional aviation recovery and military procurement cycles.
Regulatory Dynamics and Certification Challenges
Compliance remains a cornerstone of the aircraft brake calipers industry. The operational environment is strictly governed by aviation authorities, ensuring that every component meets rigorous safety standards before installation. In the United States, FAA Advisory Circular AC 25.735-1 continues to provide the essential guidance on certification tests and analysis for brakes and braking systems under 14 CFR §25.735. This framework dictates brake wear limits and ensures harmonized standards with international bodies like EASA, creating a high barrier to entry for new manufacturers while ensuring safety for operators.
Furthermore, technical standard orders such as TSO-C26d establish minimum performance standards for transport airplane wheels and brake assemblies. These standards include dynamic testing requirements that are directly applicable to brake caliper systems. For manufacturers, adhering to these regulations is not optional; it is a fundamental requirement that influences design cycles, material selection, and validation timelines. The industry context noise provided in our research highlights that brake caliper and system designs must meet these rigorous requirements for rejected takeoff and landing performance under updated airworthiness standards. Companies that can navigate these certification landscapes efficiently gain a competitive advantage in time-to-market.
Technical Segments: Actuation and Materials
From a technical perspective, the market is bifurcated primarily by actuation systems. Hydraulic brake calipers continue to represent a substantial portion of the market, owing to their proven reliability and established maintenance infrastructure across legacy fleets. However, the shift toward electric brake calipers is gaining momentum, driven by the aerospace industry's broader push for electrification and weight reduction. Electric systems offer potential benefits in terms of control precision and reduced hydraulic maintenance, aligning with modern fly-by-wire architectures.
Material science plays an equally pivotal role in segment differentiation. Aircraft brake calipers are typically manufactured from aluminum alloy or titanium to provide high strength while minimizing weight. These materials are standard for many applications where thermal loads are within specific thresholds. However, for advanced aircraft brake systems, particularly in commercial wide-body and military applications, carbon-ceramic composites are becoming a primary high-performance material option. These composites are valued for their exceptional thermal stability, allowing for higher energy absorption during heavy braking events without structural degradation. The choice between standard metals and advanced composites often depends on the aircraft type and the specific performance requirements of the mission profile.
Broader Industry Context and Operational Realities
Beyond the technical specifications, the market is influenced by broader operational realities. The fleet availability rate of airlines dictates the frequency of brake replacements. With many commercial aircraft now operating at higher utilization rates to meet travel demand, wear-and-tear on braking components accelerates, creating a steady aftermarket demand alongside original equipment (OE) orders. Similarly, military aircraft undergoing mission profile changes may require upgraded braking systems to handle higher landing weights or different operational environments.
Supply chain stability is another critical factor. The aerospace industry has learned valuable lessons regarding logistics and inventory management. Manufacturers are increasingly looking to secure long-term partnerships with tier 2 suppliers who can guarantee precision-machined components. This extends to structural elements and caliper-related parts required for commercial, military, and business aircraft. Ensuring continuity of supply for critical materials like titanium and specialized alloys is a strategic priority for mid-sized and large-scale manufacturers alike.
Competitive Landscape and Corporate Profiles
The market structure is characterized by a mix of global giants and specialized niche manufacturers. Our analysis identifies a concentrated environment where major players hold significant market share. The top three companies collectively command a substantial portion of the market, while the top five entities dominate the revenue landscape. This concentration suggests that large-scale contracts and OEM relationships are key to maintaining market leadership.
Several key companies define the current competitive landscape:
- Safran Landing Systems (France): Recognized as a world leader in landing and braking systems, Safran supplies complete wheels and brakes, including calipers, for commercial airliners with over 100 seats. Their integrated approach positions them strongly in the commercial OE sector.
- Meggitt Aircraft Braking Systems (Parker Meggitt) (UK/USA): A leading supplier of wheels, brakes, and brake control systems for business, regional, and military aircraft. Their inclusion of the NASCO subsidiary highlights a vertically integrated strategy for brake components.
- Collins Aerospace (RTX Corporation) (USA): A major provider of aircraft wheels and brakes, Collins delivers brake caliper assemblies for both commercial and military platforms, leveraging the broader RTX network for technological synergy.
- Honeywell Aerospace (USA): Supplies aircraft brake systems and components, including calipers for various aircraft platforms, benefiting from a diversified aerospace portfolio.
- Cleveland Wheel & Brake Systems (Signia Aerospace/Parker) (USA): Provides braking systems including wheels, brakes, and hydraulic caliper components for general aviation, business jets, rotorcraft, and military markets. Notably, recent developments show Cleveland was awarded a firm fixed-price purchase order in April 2026 for aircraft wheel and brake components, signaling sustained government and defense demand.
- Grove Aircraft Landing Gear Systems Inc. (USA): Specializes in light aircraft brakes and calipers, such as the 3 Series and 34-XX series, catering specifically to the general aviation segment.
- Rapco Fleet Support (RFS) (USA): An FAA-PMA approved manufacturer producing components for business jets, commuters, and turboprops like Citation, King Air, and Learjet, focusing on the aftermarket and replacement market.
- Nasco Aircraft Brake Inc. (USA): A subsidiary of Meggitt, manufacturing FAA-approved and USAF-approved wheel and brake components, reinforcing the strength of the Meggitt portfolio.
- Beringer Aero (France): Specializes in aircraft brake calipers and systems for light and general aviation aircraft, offering specialized solutions in a niche segment.
- NMG Aerospace (USA): A Tier 2 manufacturer specializing in precision-machined wheel brake components including structural elements and caliper-related parts for commercial, military, and business aircraft.
- Additional Players: Other notable contributors include Crane Aerospace & Electronics, MATCO Manufacturing Inc., Jay-Em Aerospace & Machine Inc., and Aerobrake, the latter being an FAA-PMA manufacturer of approved replacement components.
Recent developments in the market underscore the activity levels among these players. For instance, contract awards in early 2026 indicate that government and defense sectors remain active contributors to revenue growth. These events are not isolated; they reflect the ongoing need for reliable braking systems across diverse aircraft platforms. Our full report analyzes these developments to predict their medium-term impact on market shares and pricing power.
Strategic Value for 2026 Decision-Making
Why does this specific market research matter for decision-makers in 2026? The aircraft brake calipers industry is not static. It is influenced by certificate holders, material scientists, regulatory bodies, and fleet operators. For suppliers, understanding the exact split of revenue by region, aircraft type, and actuation system is vital for capacity planning. For buyers, knowing the competitive concentration helps in negotiation strategies and risk mitigation. For investors, identifying which material technologies are gaining traction informs R&D allocation.
The research provides actionable insights that go beyond basic statistics. It allows stakeholders to:
- Validate Market Entry Opportunities: Determine where the gap in the market lies, whether in electric actuation systems or specific regional aftermarket segments.
- Benchmark Competitor Activity: Compare your technological roadmap against leaders like Safran or Meggitt to identify areas for differentiation.
- Navigate Regulatory Shifts: Anticipate how changes in certification requirements might affect production costs and timelines.
- Optimize Supply Chain: Identify key tier 2 suppliers and material sources to reduce dependency risks.
Conclusion: The Path Forward
The Worldwide Aircraft Brake Calipers Market is on a definitive growth path, supported by increasing fleet sizes, higher utilization rates, and technological evolution in brake actuation and materials. The forecast period from 2026 to 2032 will likely see a divergence between traditional hydraulic systems and emerging electric solutions, with material choices playing a decisive role in performance capabilities for wide-body and military platforms.
However, the high-level overview provided here is only a glimpse of the comprehensive intelligence available. To make informed, high-stakes decisions in this competitive landscape, stakeholders require granular data regarding segmentation splits, specific regional valuations, and detailed company profiles that are not disclosed in a summary format. The full report offers the depth required to navigate these complexities with confidence.
For a complete breakdown of market size, CAGR details, segmentation revenue, and exhaustive competitive analysis, we invite you to access the full research document. Equip your organization with the precise data needed to lead in the aircraft brake calipers sector through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Brake Calipers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com