

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Glass Bending Machine Market to Reach USD 758.23 Million by 2032, Growing at 5.38% CAGR

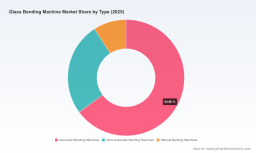
Strategic Intelligence for the Glass Bending Machine Market: Navigating Growth from 2026 to 2032
Executive Overview
The global glass bending machine market is entering a period of sustained expansion, driven by the relentless demand for curved glass solutions in modern architecture and automotive design. As we move into 2026, enterprise decision-makers require precise, forward-looking intelligence to navigate supply chain complexities, regulatory shifts, and competitive pressures. Our latest Worldwide Glass Bending Machine Market research delivers a comprehensive macroeconomic framework, tracing historical performance from 2020 through 2025 and projecting revenue trajectories to 2032. The analysis quantifies a market that reached approximately 412.35 million USD in 2020 and is forecast to scale to 758.23 million USD by 2032, reflecting a compound annual growth rate of 5.38 percent over the 2026 to 2032 forecast period. This report is engineered not as a static data dump, but as a strategic decision-support system for procurement leaders, capital allocators, and executive teams who must align capacity investments with multi-year demand cycles.
The Macro Trajectory: From Recovery to Structural Expansion
Historical data reveals a market that has consistently outpaced linear expectations. Between 2020 and 2022, the sector navigated post-pandemic recovery dynamics, moving from 412.35 million USD to 435.58 million USD and further to 456.59 million USD. The subsequent years demonstrated accelerating momentum, with valued revenues climbing to 494.73 million USD in 2023, eclipsing 499.53 million USD in 2024, and establishing a robust baseline of 525.4 million USD in 2025. Our forecast models project this momentum to carry through 2026 at 554.13 million USD, sustaining growth to 566.68 million USD in 2027, before structural inflection points push valuations to 616.83 million USD by 2028. The trajectory continues through 2029 at 641.41 million USD, reaches 691.73 million USD in 2030, and stabilizes around 693.46 million USD in 2031 before peaking at 758.23 million USD in 2032. This progression is not accidental. It reflects the compounding effect of two intersecting forces: the architectural pivot toward fluid, curved facades that demand precision bending furnaces, and the automotive industry's transition toward larger, more complex windshield and panoramic roof geometries. The 5.38 percent CAGR encapsulated in our forecast is deliberately calculated across the 2026 to 2032 horizon to smooth out short-term volatility and highlight the underlying structural runway. Enterprises that internalize this trajectory can optimize capex timing, align service infrastructure with machine deployment cycles, and preempt capacity bottlenecks before they translate into margin erosion.
Segmentation Dynamics: Where Capital Meets Application
The market's evolution is deeply heterogeneous. Our segmentation framework dissects demand across equipment types, application verticals, and geographic corridors, revealing where intensity of competition and opportunity concentration diverge. Across equipment classifications, the market is anchored by automatic bending machines, which command the largest share of revenue and reflect the industry's migration toward high-throughput, repeatable bending cycles. Semi-automatic systems maintain a meaningful presence for mid-volume producers and specialized fabricators, while manual bending machines serve niche experimental and low-volume architectural applications. On the application side, automotive glass represents a dominant demand pillar, driven by lightweighting mandates, aerodynamic optimization, and consumer preference for expansive glazing. Architectural glass constitutes a closely matched revenue stream, propelled by the proliferation of curved atriums, bespoke façade panels, and renovation projects that require custom bending solutions. The furniture and appliances segment, while smaller in absolute terms, contributes steady ancillary demand from premium retail and specialty design manufacturers who leverage bent glass for aesthetic differentiation. Geographic performance further illuminates regional competitive postures and supply chain localization strategies. Each major economic zone exhibits distinct procurement cycles, regulatory baselines, and end-user concentration patterns. Our report maps these regional revenue distributions in granular detail, enabling multinational operators to calibrate regional service networks and regionalized pricing models. Because precise regional splits and application-level percentages are tailored to support confidential client benchmarking, we reserve those exact figures for the full dataset. The framework, however, makes clear that capital deployment should be weighted toward regions where bending infrastructure modernization aligns with both automotive OEM investment schedules and large-scale architectural procurement pipelines.
Competitive Landscape: Precision, Scale, and Technological Moats
The market's competitive architecture is defined by a concentration of established OEMs that have built durable moats around furnace control systems, energy efficiency, automation integration, and application-specific engineering. Our analysis tracks a cohort of leading producers whose product portfolios and geographic footprints shape pricing dynamics and technology diffusion. Among these, Changzhou ZT Machine Co., Ltd., operating from China, has distinguished itself through large-format and complex curved glass solutions, including furnaces deployed for landmark architectural projects such as the world's tallest observation wheel. The firm's turnkey approach to automotive glass bending and lamination, combined with operator training programs, positions it as a full-lifecycle partner for high-capacity fabricators. CMS Glass Machinery, based in Turkey, has built a reputation for flat and bending glass tempering furnaces with integrated automatic bending units designed for curved tempered glass production. Its emphasis on architectural and broader glass processing applications underscores the value of versatile line configurations that can switch between flat and curved outputs without sacrificing throughput. LandGlass Technology Co., Ltd., headquartered in Luoyang, China, specializes in bent glass tempering furnaces and intelligent automotive glass bending and tempering equipment, extending its core tempering furnace portfolio into highly automated, automotive-grade production environments. This convergence of bending and tempering competencies is a recurring theme among top-tier suppliers, as integrated process lines reduce handling losses and improve dimensional consistency. European manufacturers contribute strongly to the high-end segment. Glaston Corporation, from Finland, offers a breadth of bending and tempering systems, including HTBS for bent tempered glass, ProBend for cylindrical glass, and ScreenMax for windshield bending, with a growing emphasis on zero-tooling processes for architectural and automotive applications. Recent activity highlights this trajectory: in June 2025, Glaston installed a ScreenMax glass bending furnace at Finn Lamex for windshield production, illustrating how engineered systems are being deployed into operational automotive supply chains. Mappi International Srl, Italy, focuses on high-performance curved glass processing for architectural and industrial uses, while Bottero S.p.A., also Italian, emphasizes automation and customization for curved glass production. Bavelloni, another Italian player, supplies glass machinery that includes bending and shaping solutions for architectural and specialty applications, reinforcing the region's strength in precision glass processing equipment. North American suppliers maintain a strong presence in the automotive and specialty glass segments. Glasstech, Inc., based in the United States, provides advanced automotive glass bending and tempering equipment such as the DBX-T deep bend system, optimized for high-capacity, energy-efficient production of complex curved glass. Casso-Solar Technologies, also U.S.-based, produces infrared furnaces for glass bending across architectural, automotive, aerospace, and ballistic applications, supporting both custom and high-volume production regimes with flexible heating technologies that address energy and process control requirements. From a platform and processing perspective, LiSEC Group, headquartered in Austria, supplies comprehensive flat glass processing solutions including bending and tempering equipment with high precision automation. Chinese producers such as Luoyang Lever Industry Co., Ltd., Shandong Eworld Machine Co., Ltd., and Liaoda (LAD) Glass Machinery Co., Ltd. further expand the competitive field by offering glass bending machines and tempering equipment across a range of industrial capacities, reflecting a market where regional manufacturing density and cost-competitiveness continue to drive adoption among mid-tier and emerging processors. The competitive dynamic is further characterized by measurable concentration. Market structure analysis indicates that the top three firms collectively account for approximately 38.5 percent of revenue, while the top five firms capture roughly 52.1 percent. This concentration level signals that a subset of OEMs holds meaningful influence over pricing norms, innovation velocity, and technology leadership, yet also leaves ample room for specialized challengers targeting niche applications, custom geometries, or regional service advantages. Our report profiles these companies with operational context, product differentiation, and deployment case narratives that help buyers evaluate total cost of ownership rather than unit price alone.
Industry Dynamics and the Operating Environment
Operational realities are reshaping procurement criteria and machine specifications. Raw material volatility, particularly in silica sand and energy inputs, directly impacts the cost structure of glass production and the operating economics of bending machines. Enterprises that base decisions solely on equipment sticker price are exposed to margin compression as input cost fluctuations transmit through melting, heating, and annealing cycles. Our research integrates cost-structure sensitivity into the analysis, helping buyers model energy consumption profiles and feedstock exposure when comparing furnace technologies and bending line configurations. Regulatory pressure is intensifying the focus on energy efficiency. Stricter regulations on energy consumption are compelling manufacturers to adopt sustainable practices and deploy energy-efficient glass bending equipment. This regulatory shift is not merely a compliance checkbox; it is becoming a procurement differentiator. Buyers are prioritizing furnaces and bending units that deliver lower kilowatt demand, improved heat recovery, and automated cycle control that minimizes thermal losses. The report evaluates how equipment-level energy metrics align with regional compliance expectations and how lifecycle cost modeling can turn regulatory pressure into a competitive advantage. Demand-side trends reinforce the technology upgrade cycle. Increasing demand for curved glass in modern architecture and automotive sectors is accelerating the adoption of advanced bending technologies. This demand is not limited to volume; it increasingly concerns geometric complexity, surface quality, and repeatability across large batches. As a result, manufacturers are investing in systems that can handle deep bends, cylindrical forms, and windshield geometries without re-tooling delays, while maintaining tolerances that meet architectural and automotive specifications. These dynamics elevate the strategic importance of supplier capabilities in process control, automation, and application-specific engineering.
What the Report Delivers: Operational Intelligence for 2026 and Beyond
This research is structured as a practitioner's toolkit. It begins with a rigorous historical reconstruction from 2020 through 2025, establishing baseline demand patterns and identifying the inflection points that led to the 2025 revenue environment. From there, the forecast engine extends to 2032, disaggregating growth drivers, constraints, and scenario conditions so that leadership teams can test strategic assumptions against multiple demand paths. Rather than presenting a single deterministic line, the analysis incorporates upstream and downstream factors that affect adoption speed, capacity utilization, and regional rollout cadence. The report provides actionable segmentation narratives that connect equipment types to application requirements and to the procurement behaviors of specific end-user groups. It translates these connections into guidance for capacity planning, service network design, and channel strategy. For operators evaluating investments, the segmentation analysis clarifies which machine classes are aligned with high-growth application pockets and which are better suited to stable, lower-growth niches. For suppliers, it highlights where differentiation through automation, energy efficiency, or zero-tooling processes can translate into premium positioning. Competitive profiling extends beyond product catalogs. The report examines the strategic postures of leading companies, the nature of recent deployments, and the operational signals that indicate where technology diffusion is occurring fastest. These company-level insights are cross-referenced with market concentration metrics to help stakeholders understand how market share, technological proximity, and regional presence interact to shape competitive risk and opportunity. The analysis also addresses pricing dynamics indirectly, focusing on value drivers such as throughput, energy performance, automation depth, and application coverage, which are more reliable indicators of long-term competitiveness than headline price comparisons. To support execution, the research includes frameworks for evaluating total cost of ownership across bending and tempering systems, considering energy use, maintenance intensity, retraining requirements, and scrap reduction. It also maps regulatory and input-cost pressures onto machine selection, helping organizations build procurement criteria that are resilient to volatility. For firms planning geographic expansion or service hub investments, the regional analysis offers directional intelligence on where demand density, modernization urgency, and competitive intensity create the most favorable conditions for entry or reinforcement.
Why This Analysis Matters for 2026 Decision-Making
The 2026 planning cycle demands a clear line of sight across market scale, growth momentum, and competitive positioning. With a base year of 2025, historical coverage from 2020 to 2025, and a forecast period extending to 2032, the analysis is timed to support annual operating plans, multi-year capital programs, and strategic sourcing decisions. The 5.38 percent CAGR and the progression to a 758.23 million USD market by 2032 provide a credible backdrop for scenario planning, but the real value lies in the segmentation, concentration, and dynamic context that explain how growth is distributed and where friction points emerge. Enterprises that act on this intelligence can time machinery purchases to match demand surges, select equipment classes that align with their application mix, and structure service and training support to protect uptime as complexity increases. Suppliers and investors can identify where concentration creates defensibility and where specialization can unlock share gains. In all cases, the objective is to move from reactive procurement to strategic positioning, using market structure and dynamics as a compass rather than relying on unit-price heuristics.
Next Steps for Comprehensive Market Intelligence
This overview is designed to demonstrate the analytical depth and strategic relevance of the full Worldwide Glass Bending Machine Market research while preserving the detailed figures, regional allocations, application-level splits, and proprietary benchmarking that make the dataset actionable for confidential planning. The complete report contains the granular revenue distributions, competitive profiles, deployment case studies, regulatory impact analysis, and cost-structure modeling needed to convert market intelligence into operating decisions. To access the full dataset, segmentation tables, and company-level evaluations that support precise 2026 strategy and beyond, please visit the source webpage to retrieve the complete research package.
Worldwide Glass Bending Machine Market
Worldwide Bending Machine Market
For detailed analysis of this topic, please visit the official page: Worldwide Glass Bending Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com