

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts CNS Stimulants Market to Hit $47.9B by 2032 with 6.25% CAGR

Strategic Intelligence for the Next Growth Cycle: Inside the Worldwide CNS Stimulants Market Research
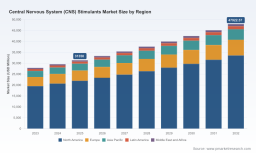
The global central nervous system (CNS) stimulants market stands at a pivotal inflection point. Built on a base year of 2025 and anchored in a five-year historical analysis (2020–2025), our latest market research projects the sector’s trajectory through 2032. The overarching narrative is one of sustained, disciplined expansion: the worldwide market surpassed USD 31.35 billion in 2025 and is forecast to reach approximately USD 33.31 billion in 2026, ultimately scaling toward a 2032 valuation near USD 47.92 billion. This progression reflects a compound annual growth rate (CAGR) of 6.25 percent across the forecast horizon, signaling a landscape where therapeutic innovation, regulatory recalibration, and supply chain resilience intersect to redefine competitive positioning.
For executives, investors, and strategic planners, the value of this research lies not in static snapshots but in actionable foresight. The following overview outlines the structural forces shaping the CNS stimulants arena, highlights the operational and regulatory dynamics that will influence 2026 decision-making, and demonstrates how our comprehensive study equips stakeholders with the intelligence required to navigate an increasingly complex environment.
Market Trajectory and Structural Momentum
The historical record (2020–2025) reveals a market that has consistently outperformed broader pharmaceutical benchmarks in both resilience and expansion. Revenue climbed from approximately USD 27.85 billion in 2023 to USD 29.52 billion in 2024, before reaching USD 31.35 billion in 2025. This sequence underscores an industry benefiting from durable prescription demand, broadening clinical utilization, and sustained formulary inclusion across mature and emerging care settings. The 2026 opening figure of USD 33.31 billion establishes a new baseline, and the forward curve—extending through 2032—demonstrates a steady accrual of value as clinical pathways mature and delivery innovations gain traction.
What makes this growth profile strategically meaningful is its consistency. A 6.25 percent CAGR over a seven-year forecast period suggests that the market is not being driven by a single transient factor but by a convergence of enduring drivers: persistent unmet need in attention-related and sleep-related disorders, incremental adoption of long-acting and specialized formulations, and continued physician familiarity with established stimulant classes. At the same time, the market’s scale and growth rate invite scrutiny from regulators, payers, and supply chain operators, creating a dynamic where competitive advantage will increasingly belong to organizations that can align product strategy with compliance readiness, manufacturing agility, and reimbursement intelligence.
Demand Architecture and Therapeutic Utilization
Within this expanding market, therapeutic demand is anchored by well-defined clinical indications that continue to shape prescribing patterns and product development priorities. Attention Deficit Hyperactivity Disorder (ADHD) remains the central pillar of utilization, reflecting the broadest patient reach and the most sustained prescribing volume across pediatric, adolescent, and adult populations. Narcolepsy represents a distinct, high-acuity demand segment where stimulant therapy plays an essential role in daytime alertness management and quality-of-life preservation. A third cluster—encompassing binge eating disorder and other affiliated indications—adds incremental breadth to the demand base, supporting a diversified usage profile that helps stabilize volume against indication-specific fluctuations.
The therapeutic footprint is mirrored by a drug-type landscape that balances established molecules with differentiated formulations. Amphetamine-based products and methylphenidate-based products each command substantial share, while specialized variants such as dexmethylphenidate and an array of other stimulants contribute targeted clinical options for specific patient profiles and tolerability considerations. The coexistence of branded and generic offerings across these categories reinforces a market structure in which clinical preference, reimbursement dynamics, and formulation convenience all influence uptake. Our research dissects these interlocking demand streams to clarify where volume concentration persists, where formulation differentiation creates pricing space, and how indication-level utilization patterns influence portfolio planning for both incumbents and entrants.
Competitive Landscape and Strategic Positioning
The CNS stimulants market is shaped by a constellation of global pharmaceutical leaders, specialty manufacturers, and formulation-focused innovators. At the top tier, multinational pharmaceutical companies leverage established brands, broad commercial infrastructure, and long-standing clinical credibility to maintain leadership positions across key stimulant categories. These organizations anchor segments built around methylphenidate and amphetamine-based therapies, with product portfolios that span immediate-release, extended-release, and specialized delivery forms. Their scale advantages in regulatory affairs, pharmacovigilance, and payer engagement create durable moats, but they also operate in an environment where formulation novelty and supply reliability increasingly differentiate performance.
Alongside these leaders, generic manufacturers and niche formulation specialists play a critical role in broadening access and shaping price dynamics. Generics of mixed amphetamine salts, methylphenidate immediate-release and extended-release tablets, and other core molecules contribute materially to overall market volume while intensifying competition on availability and cost. Simultaneously, a set of specialty players competes on delivery technology and patient-centric design—liquid formulations, extended-release architectures, delayed-release profiles, transdermal systems, and prodrug-based approaches—each aimed at improving adherence, minimizing adverse effects, or addressing unmet needs in specific subpopulations.
Worldwide Nervous System Medications Market
This layered competitive structure produces a market concentration profile that rewards strategic clarity. With a concentrated set of leading participants accounting for a substantial portion of total revenue, and a broader field of mid-tier and specialty firms contributing incremental share, the environment rewards companies that can articulate a precise positioning strategy: whether through branded differentiation, generic supply reliability, novel delivery platforms, or indications-focused commercialization. Our study maps these relationships in detail, providing competitive benchmarking, portfolio overlap analysis, and strategic implications for market entry, partnership evaluation, and lifecycle management.
Regulatory, Supply Chain, and Reimbursement Dynamics
No strategic assessment of the CNS stimulants market can ignore the regulatory and operational forces that directly influence availability, labeling, and commercial execution. Recent developments have brought these forces into sharp focus. In mid-2025, regulatory labeling updates required expanded warnings for extended-release amphetamine and methylphenidate stimulants concerning weight loss and other adverse reactions in patients younger than six years, reinforcing the importance of safety communications and indication-specific prescribing discipline. Later that year, quota adjustments by the Drug Enforcement Administration raised the aggregate production quota for d-amphetamine and methylphenidate for sale, reflecting manufacturer requests amid ongoing demand and underscoring the continued interplay between controlled-substance oversight and market supply.
These regulatory actions unfold against a backdrop of supply chain pressure. Concentrated active pharmaceutical ingredient (API) manufacturing footprints have contributed to persistent shortages of amphetamine-based CNS stimulants, and multiple manufacturers have reported ongoing constraints for immediate-release amphetamine mixed salts tablets due to active ingredient limitations and demand intensity. Quality surveillance activity has also remained a central operational consideration, with recent testing outcomes confirming compliance for selected methylphenidate hydrochloride extended-release products from key generic suppliers, illustrating the importance of manufacturing consistency and quality assurance in maintaining market continuity.
Reimbursement dynamics add another layer of strategic complexity. CNS agents, including stimulants, have been among the categories evaluated in proposed pricing benchmark parameters relevant to Medicare Part B, signaling that payer scrutiny and pricing efficiency will remain central to commercial planning. For market participants, the challenge is to align product strategy with a landscape where regulatory labeling, controlled-substance quotas, API supply reliability, and reimbursement modeling all influence prescriber behavior, patient access, and margin expectations. Our research integrates these dynamics into a coherent operational framework, enabling decision-makers to anticipate risk, prioritize mitigation, and align go-to-market plans with the realities of the 2026 environment.
What the Report Delivers: An Operational Toolkit for 2026
This market research is designed as a decision-support instrument rather than a high-level summary. It combines quantitative market sizing with qualitative strategic analysis, giving executives a multi-dimensional view of where value is created and where vulnerabilities emerge. The study provides a structured examination of market size and forecast curves, with historical context that clarifies the momentum underlying the 2026 baseline and the path to 2032. It analyzes demand across major therapeutic indications and drug-type categories without reducing the picture to simplistic aggregates, instead focusing on the strategic implications of how utilization is distributed and how formulation differences influence adoption.
The competitive analysis component profiles the leading multinational participants, the generic manufacturers, and the specialty innovators who collectively define the market’s structure. Each profile is assessed in terms of product positioning, formulation strategy, and the operational strengths that support market presence. The report also evaluates recent regulatory and supply chain developments, translating headline events into practical implications for production planning, labeling compliance, shortage management, and patient access strategies. In addition, the study explores reimbursement-related pressures and their potential influence on pricing, formulary strategy, and market access negotiations.
Worldwide Central Nervous System (CNS) Stimulants Market
To support scenario planning, the research incorporates an assessment of market concentration and competitive interdependence, helping stakeholders understand where share is held, where fragmentation creates opportunity, and where coordinated action may be required to manage supply, pricing, or regulatory risk. By weaving together market sizing, segmentation logic, competitive intelligence, and macro-level dynamics, the report provides a foundation for strategic choices in portfolio prioritization, partnership screening, manufacturing and supply chain planning, and market-entry evaluation.
Strategic Implications for 2026 Decision-Makers
As the market moves from a 2025 base of USD 31.35 billion toward a 2026 opening near USD 33.31 billion and beyond, the strategic question is not whether growth will continue, but how organizations can position themselves to capture value while managing the operational and regulatory complexities that accompany it. Companies with branded portfolios must balance clinical differentiation and safety communication against the reality of intensified generic competition and payer scrutiny. Generic and specialty manufacturers must navigate API availability, quota frameworks, and quality surveillance expectations while preserving reliability and margin integrity. Across the board, leaders need a clear view of where demand is concentrated, how formulation and delivery choices shape adoption, and how regulatory and reimbursement developments might alter the commercial calculus over the forecast period.
This research is built to inform those choices. It offers a comprehensive, evidence-based view of the CNS stimulants market’s structure and trajectory, with the granularity required to support operational planning and the strategic framing needed for executive decision-making. By integrating market sizing, segmentation logic, competitive profiling, and dynamic risk factors into a single analytical framework, the study helps stakeholders identify where to invest, where to protect, and where to adapt as the market evolves through 2032.
For organizations seeking a deeper working knowledge of the worldwide CNS stimulants market—beyond high-level aggregates and into the operational and competitive details that shape real-world strategy—we invite you to explore the full report. The complete study provides the segmentation depth, company-level analysis, regulatory and supply chain context, and forecast detail necessary to translate market intelligence into concrete 2026 decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Central Nervous System (CNS) Stimulants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com