

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Isononyl Acrylate Market to Hit $316.72M by 2032 at 5.45% CAGR

Strategic Outlook: The Worldwide Isononyl Acrylate Market 2026-2032
The global specialty chemicals landscape is undergoing a period of structural recalibration, driven by evolving end-user performance requirements, tightening environmental regulations, and volatile feedstock economics. Within this complex ecosystem, Isononyl Acrylate (INA) has emerged as a critical enabler for high-value formulations across coatings, adhesives, and advanced polymer systems. As organizations prepare their strategic roadmaps for the second half of the decade, understanding the trajectory of this niche yet pivotal monomer is no longer optional. It is a foundational requirement for capacity planning, supply chain resilience, and competitive positioning.
PW Consulting's latest comprehensive study, the Worldwide Isononyl Acrylate Market, provides an exhaustive analytical framework designed specifically to inform enterprise-level decision-making through 2032. This article outlines the strategic imperative behind this research, highlighting the macro-level market architecture, the competitive forces at play, and the regulatory and feedstock dynamics that will define the commercial landscape in the coming years.
The Macro Growth Trajectory: A Decade of Measured Expansion
The market for Isononyl Acrylate has demonstrated resilience and steady expansion over the past five years, setting a robust foundation for the forecast period. Historical revenue data from 2020 through 2025 reflects a market that has navigated supply chain disruptions and demand fluctuations with remarkable stability. The compound annual growth rate (CAGR) projected for the 2026 to 2032 forecast window stands at 5.45 percent, signaling a mature but consistently upward trajectory. This growth rate is not merely a statistical artifact; it represents the cumulative effect of sustained demand from pressure-sensitive adhesive manufacturers, UV-curable resin formulators, and industrial coating producers who continue to prioritize performance and durability in their end products.
Revenue scaling from the base year of 2025 through the terminal forecast year of 2032 underscores a market that is adding substantial absolute value over time. The progression indicates that while the sector is not experiencing explosive hypergrowth, it is firmly entrenched in a phase of value-accretive expansion. For procurement directors and strategic planners, this pattern suggests a stable pricing environment punctuated by periodic feedstock-driven volatility, rather than the erratic boom-and-bust cycles seen in less mature chemical segments. Understanding the precise inflection points within this curve is essential for timing capital expenditures, negotiation cycles, and inventory strategies.
Structural Segmentation and Regional Dynamics
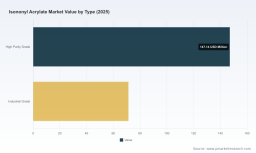
The Isononyl Acrylate market is not monolithic. Its value distribution is shaped by distinct structural splits across grade specifications, application verticals, and geographic territories. At the product grade level, the market is bifurcated between high purity grade material, which commands premium positioning due to its suitability for sensitive optical and electronic applications, and industrial grade material, which serves broader manufacturing requirements. The balance between these two categories influences margin structures across the value chain and dictates the competitive strategies of producers who must decide whether to compete on volume or on specialized formulation capabilities.
Application-wise, the market derives its largest revenue contributions from pressure-sensitive adhesives, followed by UV curable resins, industrial coatings, and plasticizers and elastomers. Each of these verticals carries unique demand drivers. The adhesives sector is heavily influenced by packaging growth and label material innovation. UV curable resins are tied to advancements in printing technologies and protective coating formulations. Industrial coatings respond to infrastructure development and automotive refinish requirements. Plasticizers and elastomers reflect broader polymer processing trends. The interplay between these demand clusters creates a diversified risk profile for market participants, insulating the overall sector from downturns in any single end-use industry.
Geographically, the market exhibits a pronounced concentration in Asia Pacific, which accounts for the largest share of global revenue. North America and Europe follow as significant secondary markets, while Latin America and the Middle East and Africa represent emerging but still relatively modest demand centers. This geographic distribution is not static. Trade flows, local manufacturing capacity additions, and regional regulatory environments continuously reshape the relative weight of each territory. For multinational corporations, this means that a one-size-fits-all supply strategy is inadequate. Regional market nuances require localized intelligence to optimize logistics, manage carbon border adjustments, and align product grades with local specification preferences.
Competitive Landscape: Key Players and Strategic Positioning
The Isononyl Acrylate industry is characterized by a moderately concentrated supplier base, with a handful of specialized chemical manufacturers holding significant market influence. The competitive dynamics are defined by product specialization, technical service capabilities, and integration with downstream formulation ecosystems rather than pure commodity pricing competition.
Sartomer (Arkema), headquartered in Exton, Pennsylvania, operates as a leading global supplier of specialty acrylates. Its Isononyl Acrylate offering, marketed under the SR-395 designation, is widely recognized in UV and electron beam curable coatings, adhesives, and inks. The company's strength lies in its global distribution network and its ability to provide technical support that bridges monomer chemistry with end-user formulation challenges. For competitors and buyers alike, Sartomer represents a benchmark for quality consistency and application engineering.
Worldwide Isononyl Acrylate Market
In South Korea, Miwon Specialty Chemical and KOHC (Kumho Oil Chemical Industrial) form a notable axis of Asian production capability. Miwon's MIRAMER M-195 product line is specifically oriented toward radiation-curable formulations, serving coatings and overprint varnish applications. KOHC complements this regional supply with a broader acrylic monomer portfolio that integrates Isononyl Acrylate into industrial resin systems and UV-curable product lines. The presence of multiple Korean producers underscores the region's strategic importance as both a manufacturing hub and a demand center, creating opportunities for localized supply chains that reduce lead times and mitigate cross-border trade friction.
In Europe, Sanfer Noury, based in Bergamo, Italy, produces Isononyl Acrylate tailored for specialty polymer applications in adhesives and coatings. The European producer landscape is increasingly shaped by regulatory compliance requirements and carbon cost considerations, making technical differentiation and regulatory readiness critical competitive advantages. The overall market concentration, as reflected by the combined share of the top three and top five players, indicates a market where scale, technical reputation, and supply reliability matter more than price alone. New entrants or existing players seeking to expand share must therefore invest in application development support, quality certification, and supply chain transparency to gain traction.
Regulatory and Feedstock Dynamics: Navigating the External Environment
Market performance for Isononyl Acrylate does not exist in a vacuum. It is deeply intertwined with raw material economics and regulatory frameworks that can alter cost structures and market access overnight. Production of Isononyl Acrylate relies on isononyl alcohol, which is derived from isobutene. As of the first quarter of 2026, isobutene spot prices have been reported at $850 per metric ton, reflecting a stable petrochemical feedstock supply environment. While stability in the upstream base chemical is constructive, it does not eliminate volatility elsewhere in the value chain.
Acrylic acid, a key feedstock for acrylate esters, introduces a separate layer of cost sensitivity. In February 2026, acrylic acid traded at $1,450 per metric ton FOB Asia, representing a five percent increase from the prior month driven by propylene tightness. This upward pressure on a critical input material can compress margins for producers who have not secured long-term supply agreements or who lack hedging mechanisms. For downstream formulators, sustained increases in acrylic acid costs may eventually translate into higher monomer prices, prompting a reevaluation of formulation economics and alternative material considerations.
On the regulatory front, the European Union's Carbon Border Adjustment Mechanism (CBAM) has introduced a new dimension of cost accountability for non-EU producers. Starting in January 2026, imported Isononyl Acrylate from outside the EU is subject to carbon border adjustment if embedded emissions exceed 0.3 metric tons of CO2 equivalent per metric ton of product. This policy effectively raises the cost of carbon-intensive production routes and incentivizes suppliers to adopt cleaner manufacturing processes or source feedstocks with lower carbon intensity. For buyers in Europe, CBAM compliance is now a procurement criterion that extends beyond price and quality to include the carbon footprint of the supply source.
Simultaneously, regulatory clarity in other jurisdictions provides a degree of operational certainty. The REACH registration for Isononyl Acrylate, identified under EC number 248-214-6, has been confirmed as compliant with no additional restrictions under Annex XVII as of the 2025 update. This status reduces regulatory uncertainty for European market participants and allows formulators to continue using the material without the burden of emerging restriction risks. Nevertheless, regulatory landscapes are dynamic, and continuous monitoring remains essential for long-term planning.
What the Full Report Delivers: Actionable Intelligence for 2026 and Beyond
The Worldwide Isononyl Acrylate Market study by PW Consulting is designed to translate these complex dynamics into structured, decision-ready intelligence. The report goes beyond headline market sizing to provide a granular yet strategically coherent view of the industry. It covers historical performance data, detailed forecast trajectories, and segmentation analyses that illuminate where growth is concentrated and where margins are under pressure.
Isononyl Alcohol Market
Key components of the research include a comprehensive segmentation breakdown by region, grade type, and application, enabling readers to identify the most promising commercial opportunities within their specific operational context. The report examines market concentration metrics and the competitive positioning of major suppliers, offering insights into share dynamics, product differentiation strategies, and potential consolidation trends. Additionally, the study integrates real-time industry context, including raw material price movements, regulatory updates, and regional policy shifts, to provide a living picture of the forces that will shape market outcomes throughout the forecast period.
For strategic planners, the report serves as a foundation for scenario analysis. It supports decisions related to capacity investment, supplier diversification, pricing strategy, and geographic expansion. For procurement teams, it provides the context needed to negotiate effectively, anticipate cost pressures, and evaluate the long-term viability of supply relationships. For product developers and R&D leaders, the segmentation and application data offer guidance on where formulation innovation can capture premium value and where commoditization risks are greatest.
Strategic Takeaways for Decision Makers
As the Isononyl Acrylate market moves through the 2026 to 2032 period, several strategic themes will define success for market participants. First, feedstock cost management will remain a critical lever for margin protection, requiring active monitoring of isobutene and acrylic acid markets and the development of flexible sourcing arrangements. Second, regulatory compliance, particularly around carbon costs and chemical registration, will increasingly influence supplier selection and geographic sourcing decisions, making transparency and documentation essential assets. Third, the moderate but steady growth trajectory rewards players who can differentiate through technical service, application support, and grade specialization rather than those who rely solely on volume competition.
The market's regional concentration and evolving trade policy environment also demand a nuanced geographic strategy. Companies must balance the efficiency of centralized supply against the resilience and cost advantages of regionalized production and distribution, all while accounting for mechanisms such as CBAM that alter the economics of cross-border trade. Finally, the competitive landscape, while concentrated, remains dynamic. Suppliers that invest in innovation, quality consistency, and customer collaboration are best positioned to protect and expand their share in a market where the top players already command a significant portion of total revenue.
PW Consulting's Worldwide Isononyl Acrylate Market report offers the depth, structure, and forward-looking analysis required to navigate these complexities with confidence. The full study provides the detailed segmentation data, regional breakdowns, competitive profiles, and forecast models that enterprise teams need to convert market intelligence into actionable strategy. For those preparing to make critical decisions in 2026 and beyond, accessing the complete report is the essential next step toward securing a well-informed, strategically sound position in this evolving specialty chemicals market.
For detailed analysis of this topic, please visit the official page: Worldwide Isononyl Acrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com