

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Lemon Juice Concentrates Market to Reach $1,237.91 Million by 2032, Growing at 5.45% CAGR

Navigating the Citrus Shift: Strategic Intelligence for the Global Lemon Juice Concentrates Market Through 2032
The global lemon juice concentrates market is entering a phase of structural transformation, driven by shifting consumer preferences, supply chain volatility, and evolving regulatory frameworks across key trade corridors. As procurement leaders, product developers, and competitive intelligence teams calibrate their strategies for the 2026–2032 horizon, access to precise, forward-looking market intelligence is no longer a luxury but a strategic imperative. This comprehensive market study dissects the operational, financial, and competitive dynamics shaping the worldwide lemon juice concentrates landscape, providing decision-makers with the contextual clarity needed to optimize sourcing, portfolio positioning, and regional expansion.
The market has demonstrated consistent expansion over the past half-decade, reflecting steady demand from industrial food and beverage manufacturers alongside emerging applications in cosmetics and pharmaceuticals. From 2020 through 2025, the sector moved from approximately 660.45 million USD to 853.82 million USD, a trajectory that underscores both baseline resilience and the compounding effect of value-added product innovation. Looking ahead, the forecast period to 2032 projects a compound annual growth rate of 5.45 percent, with market valuation expected to surpass the 1.2 billion USD threshold by the early 2030s. These macro-level indicators signal a market that is maturing but far from saturated, with significant variation in growth velocity across product formulations, end-use verticals, and geographic corridors.
Decoding the Forecast: Why 2026 Market Intelligence Matters for Forward-Looking Strategy
Forecasting in the concentrates sector requires more than extrapolating historical trends. Raw material volatility, trade policy adjustments, and processing technology shifts introduce discontinuities that traditional models often fail to capture. For executives planning capital allocation, supplier diversification, or new product development in 2026, a granular understanding of these inflection points is essential. This study maps the trajectory from the 2026 baseline of roughly 906.28 million USD through to the 2032 outlook, highlighting where demand acceleration is likely to concentrate and which structural constraints may cap expansion in specific corridors.
Strategic decision-makers will find particular value in the report's approach to translating top-line growth into actionable intelligence. Rather than presenting static snapshots, the analysis constructs a dynamic view of how pricing pressure, harvest cycles, and formulation preferences interact to shape procurement timelines and margin structures. This enables teams to anticipate rather than react to market shifts, aligning inventory planning, contract negotiation, and R&D investment with realistic demand scenarios.
Core Pillars of the Worldwide Lemon Juice Concentrates Market Study
The report is structured to deliver both breadth and operational depth, ensuring that commercial, procurement, and strategy functions can extract directly applicable insights. Each section is designed to bridge high-level market context with the tactical decisions that determine competitive performance.
- Historical Baseline and Forward Trajectory : A decade-spanning analysis from 2020 to 2032 that contextualizes past performance and isolates the drivers likely to dictate growth through the forecast period.
- Product Architecture and Formulation Dynamics : A detailed examination of cloudy versus clarified lemon juice concentrates, including processing requirements, sensory profiles, and the industrial use cases that favor each format.
- Application Vertical Mapping : Deep dives into beverages, food and confectionery, cosmetics and personal care, and pharmaceuticals and other end uses, with emphasis on formulation trends, label-claim pressures, and substitution risks.
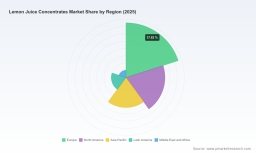
- Regional Supply and Demand Corridors : A comparative assessment of major geographic markets, focusing on production capacity, import dependency, logistics constraints, and the evolving role of trade policy in shaping regional pricing.
- Competitive Positioning and Firm-Level Profiles : Comprehensive company analyses covering manufacturing footprint, product breadth, capacity strategies, and recent commercial moves that signal shifting market intent.
- Pricing Architecture and Raw Material Intersections : An evaluation of how lemon supply dynamics, processing costs, and contract structures influence concentrate pricing, with particular attention to recent upward price momentum and regional supplier behavior.
- Regulatory and Compliance Landscape : A review of trade agreements, antidumping provisions, tariff parity mechanisms, and food safety notifications that affect cross-border trade and ingredient verification requirements.
- Scenario Planning and Strategic Playbooks : Practical frameworks for stress-testing sourcing strategies, evaluating supplier consolidation risks, and identifying high-probability opportunities for margin protection and market entry.
Competitive Landscape: Leading Actors and Strategic Positioning
The global lemon juice concentrates market is characterized by a moderately concentrated structure, with the top three firms accounting for approximately 32.45 percent of total revenue and the top five reaching roughly 48.72 percent. This concentration level reflects the presence of established regional processors alongside multinational ingredient suppliers, creating a competitive environment where scale, geographic sourcing advantage, and formulation expertise determine differentiation.
European manufacturers maintain a strong foothold, leveraging proximity to high-quality citrus cultivation and established processing infrastructure. Firms based in Spain and Italy have built reputations around fresh lemon sourcing, precise clarification and cloud retention technologies, and tailored ingredient blends for beverage and food applications. Recent commercial activity from these players illustrates a clear strategic focus on emulsified and high-performance formulations, alongside targeted partnership development in growth corridors such as the Middle East. These moves reflect an intent to capture premiumization trends while expanding distribution reach beyond traditional core markets.
In the Americas, a mix of specialized citrus processors and broader ingredient suppliers competes on reliability, volume consistency, and product range. North American firms offer both concentrated and reconstituted lemon juice products, serving baking, marinade, sauce, and industrial beverage customers with formulations designed for process stability and flavor consistency. Meanwhile, South American processors bring organic certification capabilities and large-scale lemon processing infrastructure to the global supply chain, positioning organic lemon juice concentrate and related citrus derivatives as differentiated offerings in markets where clean-label and sustainability claims carry pricing power.
Asian and cross-border manufacturers have expanded their presence through aseptic processing technology, export-oriented production facilities, and a focus on natural, high-quality concentrate grades for global distribution. Their growth trajectory highlights the increasing importance of supply chain redundancy and the role of processing precision in meeting stringent international food safety expectations. Multinational ingredient companies with broader fruit juice portfolios also participate in this market, leveraging integrated supply networks and formulation expertise to serve large-scale industrial clients across multiple geographies.
Supply Chain Realities: Raw Material Pressures and Pricing Architecture
The cost structure of lemon juice concentrates is highly sensitive to agricultural output, weather patterns, and harvest timing. Recent market observations indicate that bulk industrial lemon juice pricing from Southern European suppliers has moved upward, with 2026 campaign quotes reported around the 1.10 EUR per kilogram range, a notable shift from typical prior levels near 0.70 EUR per kilogram. This repricing reflects a combination of supply disruptions, scarcity pressures, and delayed harvests that have tightened availability, particularly in European markets where demand has remained robust.
These raw material dynamics carry direct implications for concentrate pricing, contract structuring, and inventory strategy. Procurement teams that rely on short-term spot purchasing may face heightened exposure to price swings, while organizations with forward contracts, diversified sourcing, or formulation flexibility are better positioned to manage cost volatility. The report examines how these pricing signals interact with regional supply balance, logistics constraints, and end-user demand elasticity, enabling readers to evaluate where cost pass-through is feasible and where margin compression is likely to intensify.
Regulatory Currents and Trade Policy Intersections
Trade policy and food safety compliance introduce additional layers of complexity to the global concentrates market. Recent adjustments to longstanding trade arrangements have reinforced reference pricing mechanisms for lemon juice shipments to the United States, preserving price-based oversight within established antidumping frameworks. At the same time, reciprocal tariff considerations continue to affect lemons and related citrus products entering the U.S. market, creating periodic parity dynamics that intersect with domestic growing seasons and import timing.
Worldwide Citrus Concentrate Market
Beyond trade policy, food safety monitoring remains a critical operational concern. Notifications related to undeclared preservative residues in imported prepackaged lemon juice concentrate illustrate the compliance scrutiny that ingredient suppliers and formulators must navigate. For manufacturers and private-label buyers, these developments reinforce the importance of supplier verification, documentation rigor, and specification control. The study maps these regulatory and compliance threads to specific market segments and regions, helping organizations anticipate where documentation requirements, testing protocols, and sourcing constraints may influence procurement decisions.
Where Growth Is Taking Shape: Application and Segment Inflection Points
While the overall market expands at a steady pace, growth is not distributed uniformly across applications or product types. Beverages remain a central demand driver, supported by flavor intensity requirements, mixer applications, and functional beverage formulations that rely on consistent acidity and aroma delivery. Food and confectionery uses continue to contribute meaningful volume, particularly in formats where lemon concentrate serves as both flavor and preservative functional ingredient.
At the same time, cosmetics and personal care, along with pharmaceuticals and other specialized applications, represent important avenues for differentiated demand. These verticals often prioritize purity, traceability, and specific formulation characteristics, creating opportunities for suppliers that can demonstrate process control and regulatory compliance. The report assesses how these application-level dynamics interact with product type preferences, helping readers understand where cloudy and clarified concentrates are likely to see stronger pull-through and where formulation substitution may alter demand patterns over the forecast horizon.
How to Use This Study for 2026 Decision-Making
This market study is designed to support a range of strategic functions. Procurement and supply chain leaders can use the regional and pricing analyses to refine sourcing strategies, assess supplier risk concentration, and time contract negotiations more effectively. Commercial and marketing teams can leverage application and product-type insights to align product development with high-growth demand corridors and to evaluate where premium formulation claims may command stronger positioning. Strategy and corporate development teams can draw on the competitive profiles and market concentration analysis to identify partnership opportunities, evaluate market entry conditions, and benchmark internal capabilities against established participants.
The report's structure also supports scenario-based planning. By linking historical performance, raw material signals, regulatory developments, and competitive behavior to forward projections, the study provides a framework for testing strategic choices against realistic market conditions. Readers can use these insights to prioritize investments, calibrate growth assumptions, and reduce uncertainty in planning cycles that extend through 2032.
Access the Full Strategic Intelligence
The Worldwide Lemon Juice Concentrates Market study offers a comprehensive, data-grounded view of a sector undergoing meaningful structural change. For organizations operating in food and beverage manufacturing, ingredient sourcing, cosmetics formulation, or pharmaceutical supply chains, the ability to read these dynamics accurately will shape procurement efficiency, product competitiveness, and market responsiveness in the years ahead.
To access the complete segmentation analysis, full regional revenue breakdowns, detailed company profiles, regulatory timelines, and scenario models, visit the official report page for the Worldwide Lemon Juice Concentrates Market. The full study delivers the end-to-end intelligence required to translate market momentum into executable strategy for 2026 and beyond.
Worldwide Lemon Juice Concentrates Market
For detailed analysis of this topic, please visit the official page: Worldwide Lemon Juice Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com