

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global tractor autosteer market nears $3.34B by 2032 with 12.48% CAGR

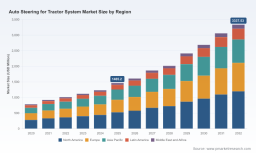
Navigating Precision: Strategic Insights into the Global Auto Steering for Tractor System Market
The agricultural machinery sector is undergoing a profound transformation, driven by the relentless pursuit of operational efficiency, labor optimization, and data-driven precision. At the forefront of this evolution is the Auto Steering for Tractor System Market, a critical segment within the broader precision agriculture ecosystem. As we move deeper into the decade, the integration of automated guidance solutions is no longer a luxury reserved for high-capital operations but a foundational requirement for competitive farming enterprises worldwide. Our latest comprehensive study, the Worldwide Auto Steering for Tractor System Market analysis, provides a definitive roadmap for stakeholders aiming to navigate the complexities of this high-growth environment.
This report is not merely a collection of statistics; it is a strategic instrument designed to empower executives, investors, and product managers with the intelligence needed to make informed decisions in 2026 and beyond. The global market has demonstrated robust resilience and expansion, reflecting the accelerating adoption of technology across diverse agricultural landscapes. Understanding the trajectory of this market is essential for capitalizing on emerging opportunities while mitigating risks associated with technological saturation and regulatory shifts.
Market Trajectory and Growth Dynamics
The historical performance of the auto steering market sets a strong precedent for future expectations. Between 2020 and 2025, the market has experienced consistent upward momentum, driven by the increasing demand for precision farming techniques. The revenue figures over this period illustrate a clear trend of expanding adoption rates among tractor operators seeking to minimize overlap, reduce fuel consumption, and maximize crop yield potential.
Looking forward, the forecast period from 2026 to 2032 projects sustained growth, with the market expected to reach significant revenue milestones by the end of the decade. The compound annual growth rate (CAGR) during this forecast window underscores the velocity of this expansion. This growth is not linear; it is influenced by a confluence of factors including technological advancements in GNSS positioning, the decreasing cost of hardware components, and the rising awareness of sustainability metrics in agriculture. For enterprises operating in this space, the implication is clear: the window for establishing market share is widening, but the competitive intensity is sharpening concurrently.
Strategic planning for 2026 requires an understanding of how these macroeconomic indicators translate into regional and segment-specific performance. While aggregate numbers provide the baseline, the real value lies in dissecting the drivers behind the numbers. The transition from basic guidance to full autonomous capabilities is becoming the key differentiator. Stakeholders must recognize that the market valuation is a function of both unit sales and the increasing value-add of software integration and service packages accompanying hardware deployments.
Segmentation and System Architecture
The market is structurally divided based on system type and application scale, each presenting unique value propositions and adoption barriers. The dichotomy between Hydraulic Autosteer Systems and Electric Motor Autosteer Systems represents a critical technological fork in the road. Hydraulic systems continue to hold strong relevance in regions and machinery where legacy infrastructure supports hydraulic actuation, offering robust performance in heavy-duty applications. Conversely, Electric Motor systems are gaining traction due to their compatibility with steer-by-wire architectures, offering faster response times and easier integration with electronic control units (ECUs) found in modern tractors.
Our analysis details the specific strengths and limitations of each architecture, helping clients decide whether to focus on retrofit kits or factory-installed solutions. The application landscape is similarly bifurcated between Large Scale Farms and Small and Medium Farms. Large-scale operations often drive volume due to the extensive acreage requiring coverage, prioritizing high-precision RTK solutions to maximize input efficiency. Small and medium farms, however, represent a growing volume segment driven by government subsidies, cooperative purchasing models, and the availability of cost-effective retrofit kits that bring precision technology to smaller holdings.
Understanding the interplay between system type and application is vital for product positioning. A solution optimized for a large-scale grain operation in North America may not fit the needs of a diversified cropping system in Asia Pacific. The report provides the framework to map these intersections without relying on oversimplified generalizations, allowing for nuanced go-to-market strategies.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of original equipment manufacturers (OEMs) and specialized aftermarket solution providers. The top ten key companies analyzed in our report dominate a significant portion of the market revenue, highlighting a moderately concentrated landscape. Leading entities such as John Deere and CNH Industrial maintain strong positions through deep ecosystem integration, offering factory-installed guidance systems like AutoTrac and AFS AccuGuide that lock customers into proprietary networks while delivering high reliability.
AGCO Corporation leverages its multi-brand portfolio to deliver flexible solutions across Fendt, Massey Ferguson, and Valtra platforms, emphasizing ISO-compliant interfaces that appeal to operators seeking compatibility. On the aftermarket and retrofit side, companies like Trimble Agriculture, Topcon Agriculture, and CHC Navigation play pivotal roles. These players enable mixed-fleet optimization, allowing operators to equip older machinery with advanced GNSS guidance without replacing entire units. CHC Navigation, for instance, has recently pushed the envelope with the launch of the NX612 automated steering system, highlighting high-quality GNSS boards supporting multiple satellite systems to enhance versatility across different field conditions.
Specialized technology firms such as Raven Industries and Hexagon Agriculture focus on modular kits and guidance products that integrate seamlessly with existing hardware, emphasizing efficiency gains through reduced overlap. CLAAS KGaA mbH continues to integrate GPS PILOT systems directly into their tractor lines, maintaining a strong footprint in European markets. The emergence of data-centric updates, such as FJDynamics' recent highlights on ISOBUS connectivity for their AS2 and AT2 series, signals a shift towards interoperable data management alongside steering control. AG Leader Technology rounds out the landscape with integrated display and steering solutions that emphasize farm data management alongside vehicle control.
For new entrants or existing players looking to expand, the key lies in identifying gaps in this ecosystem. Opportunities exist in software layers that unify disparate hardware, in regions where OEM penetration is lower, and in value-added services that monetize the data generated by these steering systems. The report analyzes the strategic moves, recent product launches, and technology highlights of these key players to illuminate potential partnership avenues or competitive threats.
Industry Dynamics: Regulation and Technology
The trajectory of the auto steering market is not solely defined by market demand but also by the regulatory and technological environment. Safety standards are becoming more rigorous. The introduction of ISO 18497-1:2024 specifies safety requirements for highly automated agricultural machines, including aspects of steering systems. While this standard excludes public road operations and specific braking requirements on roads, it sets a precedent for safety integration within field operations. Manufacturers must ensure their steering architectures comply with these evolving safety norms to maintain market access and liability protection.
On the technology front, the precision benchmark has shifted. Auto steering systems commonly achieve accuracy levels around ±2.5 cm using RTK GNSS positioning combined with IMU sensors for terrain compensation. This level of precision is becoming the baseline expectation for high-value crops and repetitive field operations. The integration of IMU sensors to compensate for terrain variations is a critical technical detail that differentiates high-performance systems from basic guidance tools. Our report delves into the technical specifications that matter most to end-users, separating marketing claims from operational reality.
Furthermore, environmental regulations are indirectly shaping the market. The EPA Greenhouse Gas Emissions Standards for heavy-duty vehicles (Phase 3), applying to model year 2032 and later, are influencing powertrain integration. While primarily focused on emissions, these standards encourage greater electronic integration and efficiency optimization within agricultural tractors, which in turn benefits the adoption of electric steering systems that can communicate more effectively with powertrain management systems. This regulatory ripple effect is a crucial consideration for long-term product roadmaps.
Worldwide Agricultural Automated Steering System Market
Strategic Value for 2026 Decision-Making
Why is this report essential for 2026 planning? The answer lies in the granularity of actionable intelligence. Market entry decisions, product development roadmaps, and investment allocations all require more than surface-level data. This study provides a comprehensive view of the total market size, historical performance, and forecast trajectories, allowing stakeholders to model various scenarios based on realistic growth parameters. The revenue unit analysis helps in financial forecasting, while the segmentation splits offer insights into where volume and value are concentrated.
For investors, the market concentration metrics provide a gauge of competition intensity and potential barriers to entry. For manufacturers, the breakdown of system types and applications informs R&D priorities and supply chain planning. For distributors and service providers, the regional dynamics and key company profiles highlight potential partnership opportunities and market gaps. The inclusion of recent developments, such as product launches and technology highlights from 2025 and early 2026, ensures that the analysis reflects the current state of play rather than outdated trends.
Moreover, the report addresses the "why" behind the numbers. It connects the dots between regulatory changes, technological capabilities, and market adoption rates. This contextual understanding is what transforms raw data into strategic advantage. In a market moving at a CAGR closing in on double digits, missing the nuance of a technological shift or a regulatory update can result in significant opportunity costs.
Worldwide Auto Steering for Tractor System Market
Conclusion: Unlocking the Full Intelligence
The Worldwide Auto Steering for Tractor System Market is poised for a defining period of growth and consolidation. The convergence of precision technology, regulatory pressure for efficiency, and the economic necessity of optimizing farm operations creates a fertile ground for innovation and investment. However, success in this environment demands more than intuition; it requires rigorous, data-backed analysis.
This overview has highlighted the magnitude of the opportunity, the complexity of the competitive landscape, and the critical dynamics shaping the future. Yet, the depth of detail required to execute a winning strategy extends far beyond a summary. The specific regional revenue breakdowns, detailed company profiles, granular segmentation splits, and comprehensive forecast tables are contained within the full report.
To truly leverage these insights for your 2026 strategic planning, we invite you to access the complete Worldwide Auto Steering for Tractor System Market research. The full document provides the exhaustive data tables, in-depth regional analysis, and detailed competitive profiling necessary to navigate this evolving market with confidence. Secure the complete intelligence today to ensure your decisions are built on the most accurate and up-to-date industry foundation available.
For detailed analysis of this topic, please visit the official page: Worldwide Auto Steering for Tractor System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com