

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Insights: Worldwide Aftercooler Market to Hit USD 3,353.57 Million by 2032, Growing at 5.82% CAGR from 2025

Strategic Thermal Management: Unpacking the Worldwide Aftercooler Market Outlook for 2026 and Beyond
In the complex ecosystem of industrial machinery, few components are as critical yet as overlooked as the aftercooler. As compressed air systems remain a backbone for manufacturing, oil and gas extraction, and chemical processing, the demand for efficient thermal management solutions is accelerating. For strategic decision-makers, understanding the trajectory of this market is not merely about tracking a single component; it is about anticipating shifts in capital expenditure, operational efficiency standards, and supply chain resilience.
This article serves as a precursor to our comprehensive Worldwide Aftercooler Market Research report. It outlines the macro-economic drivers, competitive structures, and technological mandates shaping the landscape. While we will explore the breadth of the opportunity here, the granular intelligence required to navigate specific growth corridors and risk vectors is contained within the full study, available for download on our source page.
The Macro-Economic Trajectory: Resilience Amidst Volatility
The aftercooler market has demonstrated remarkable resilience over the past half-decade. Between 2020 and 2025, the global industry expanded from approximately 1,720 million USD to 2,260 million USD. This growth was not linear; it reflected a broader industrial recovery and a renewed focus on energy efficiency across heavy industries. As we move into the forecast period spanning 2026 to 2032, the momentum is expected to sustain, driven by a projected compound annual growth rate (CAGR) that underscores steady expansion.
By 2032, the market valuation is poised to approach the 3,350 million USD milestone. This trajectory suggests that despite macroeconomic headwinds, the foundational demand for compressed air quality remains inelastic. Industries reliant on pneumatic systems cannot compromise on moisture removal without risking equipment failure and product contamination. Consequently, the aftercooler segment acts as a defensive growth investment within the broader industrial HVAC and compression sector.
However, growth is not uniform across all vectors. The market is influenced by a confluence of factors including raw material costs, regulatory standards, and regional industrial policies. For executives planning CAPEX for 2026, relying on aggregate growth figures is insufficient. Understanding which application sectors are driving volume versus value, and how regional industrialization rates differ, requires a deeper dive. Our full report dissects these nuances, providing a clear map of where capital is flowing and why.
Industry Dynamics: Regulation, Materials, and Efficiency
The operational imperative for aftercoolers has never been stronger. In modern industrial processes, compressed air quality is governed by stringent standards. The ISO 8573-1:2010 standard, for instance, defines specific purity classes for particles, water, and oil. Aftercoolers serve as the primary step to reduce moisture content immediately downstream of the compressor, often removing up to 80% of moisture before air reaches dryers and filters. This function is critical for achieving required purity classes, making aftercoolers a non-negotiable element in compliant systems.
Furthermore, energy efficiency is no longer optional. ISO 11011:2013 provides requirements for compressed air system energy efficiency assessments. Within this framework, aftercoolers contribute to overall system performance and energy optimization by reducing the thermal load on downstream components. As energy costs rise and sustainability mandates tighten, the efficiency of the heat exchange process becomes a key differentiator in procurement decisions.
On the supply side, material science plays a pivotal role. Aluminium captured approximately 43% of the aftercooler market by material in recent sector analyses. Its dominance is attributed to corrosion resistance, a high heat-transfer coefficient, and low weight. Technological advancements such as new alloys and laser-welded plate-fin cores are being deployed to reduce raw material consumption while maintaining pressure integrity. Yet, this reliance presents a risk vector. LME aluminium prices reached levels above 3,500 USD per tonne in April 2026, with U.S. all-in costs exceeding 6,000 USD per metric ton amid supply disruptions and tariffs. These cost pressures are forcing manufacturers to innovate on design longevity and material efficiency, impacting pricing strategies across the value chain.
Competitive Landscape: Fragmentation and Consolidation
The marketplace is characterized by a mix of established multinational conglomerates and specialized niche players. Market concentration metrics indicate a moderately fragmented environment. The top three companies hold roughly 32.4% of the market, while the top five expand this share to 46.5%. This structure suggests that while scale matters, specialized expertise and regional presence remain viable differentiators.
Leading the pack is Atlas Copco AB, headquartered in Stockholm, Sweden. They offer integrated aftercoolers as part of comprehensive compressed air systems, including both air-cooled and water-cooled models designed for moisture removal and temperature reduction in diverse industrial applications. Their strategy emphasizes system integration, ensuring that the aftercooler works seamlessly within the broader compressor ecosystem.
Ingersoll Rand Inc., based in Davidson, North Carolina, USA, provides significant competition through its compressed air portfolio. They supply aftercoolers via standalone and integrated units, bolstered by acquisitions such as brands like OMI (Officine Meccaniche Industriali). This acquisition strategy allows them to broaden their product reach without necessarily developing every line in-house.
European engineering prowess is also evident with Kaeser Kompressoren SE from Coburg, Germany. They manufacture air-cooled and water-cooled stand-alone aftercoolers specifically designed to complement rotary screw compressors for efficient moisture separation. Their focus on complementing existing compressor fleets makes them a key partner for industrial retrofit projects.
Parker-Hannifin Corporation, located in Cleveland, Ohio, USA, supplies the Hiross Hypercool range of air-cooled aftercoolers for compressed air and gas systems. Their technology focuses on removing water vapor downstream of compressors. Similarly, Donaldson Company, Inc., from Bloomington, Minnesota, offers aftercoolers and related air treatment solutions, including Ultrafilter-branded products, positioning themselves as a holistic air quality solutions provider.
In the realm of precision and automation, SMC Corporation of Tokyo, Japan, produces aftercoolers for compressed air applications with a focus on precision industrial automation and pneumatic systems. This signals a growing intersection between traditional heavy industry aftercooling and high-precision manufacturing needs.
Specialization continues to thrive among smaller entities. Van Air Systems in Lake City, Pennsylvania, specializes in aftercooler systems including Cool Pak PRO models with integrated filter/separator for moisture removal. AKG Thermal Systems, with operations in Hofgeismar, Germany and Mebane, NC, manufactures rugged air-cooled aftercoolers for compressed air drying and equipment protection. Meanwhile, VMAC Global Technology in British Columbia, Canada, provides mobile air aftercoolers for vehicle-mounted compressors, highlighting the importance of the mobile industry segment. Other players like Gritco in the Netherlands and Officine Meccaniche Industriali Srl (OMI) in Italy serve specific niches such as blasting applications and food/pharmaceutical industries respectively. Thermal Transfer Products (TTP) in the USA rounds out the landscape with AHP and AHPH series vertical and horizontal core aftercoolers for high-performance air-cooled heat exchange.
Segmentation: Applications and Technologies Driving Demand
The demand curve for aftercoolers is pulled by diverse application sectors. Manufacturing remains a dominant force, driven by the sheer volume of pneumatic tools, packaging machinery, and general industrial automation that rely on clean, dry air. The Oil & Gas sector follows closely, where compressed air is essential for control systems, instrumentation, and safety mechanisms in often harsh environments.
Chemicals & Petrochemicals represent another critical vertical. In these facilities, air quality standards are exceptionally high to prevent contamination of sensitive processes or hazardous reactions. The Food & Beverage industry similarly demands stringent air purity to meet health and safety regulations, often requiring aftercoolers that integrate seamlessly with sterilization workflows. Energy & Power sectors utilize aftercoolers in turbine inlet systems and general plant maintenance, while the Others category captures emerging applications in HVAC, pharmaceuticals, and textiles.
Cryocoolers Market
Technologically, the market splits between Air-Cooled and Water-Cooled solutions. Air-cooled units are often preferred for their simplicity and lower water consumption, making them suitable for regions facing water scarcity or where infrastructure is limited. Water-cooled systems, conversely, offer higher efficiency in heat rejection and are often deployed in large-scale industrial plants where water availability is not a constraint and higher thermal loads must be managed. The choice between these types is increasingly influenced by total cost of ownership calculations, including water treatment costs and energy consumption, rather than just upfront hardware prices.
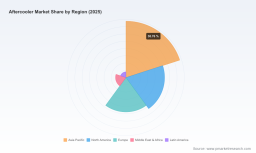
Geographically, Asia Pacific stands out as a region of significant industrial expansion, hosting a large share of global manufacturing capacity. North America and Europe maintain mature markets where replacement cycles and efficiency upgrades drive demand rather than pure new capacity expansion. Middle East & Africa and Latin America represent growth frontiers, often linked to specific industrial projects in energy and infrastructure. However, the specific revenue contributions and growth rates within these regions contain strategic insights that are detailed in the full report.
Strategic Imperatives for 2026 Decision-Making
As we navigate 2026, stakeholders must look beyond the headline numbers. The convergence of rising raw material costs, regulatory pressure on energy efficiency, and the need for system integration creates a complex buying environment. Procurement teams cannot simply compare unit prices; they must evaluate the long-term thermal performance, material durability against corrosion, and compatibility with existing compressor fleets.
For investors and market entrants, the fragmentation of the top five players suggests room for consolidation or niche specialization. Companies that can offer modular solutions, reduce aluminium dependency through alloy innovation, or provide digital monitoring of cooling efficiency may gain an edge. The trend towards mobile aftercooling, as seen in vehicle-mounted compressors, also opens avenues in the logistics and construction sectors that are often overlooked in traditional industrial analyses.
Risk management is equally critical. Supply chain disruptions affecting aluminium and steel, coupled with tariff regimes in key markets, can erode margins. Understanding how key competitors like Atlas Copco or Ingersoll Rand are hedging these risks through vertical integration or sourcing strategies is vital for benchmark planning.
Conclusion: Access the Full Intelligence
The worldwide aftercooler market is at a inflection point where operational necessity meets strategic innovation. The growth from 2,260 million USD in 2025 towards 3,353 million USD by 2032 is more than a statistic; it represents a shift in how industries value air quality and energy efficiency. However, capitalizing on this growth requires precise knowledge of segment velocities, regional risks, and competitive moves.
This article has outlined the structural dynamics, key players, and external pressures shaping the market. To transition from general understanding to actionable strategy, we invite you to access our full Worldwide Aftercooler Market Research report. There, you will find detailed segmentation data, specific regional analysis, comprehensive competitor profiling, and forecast models tailored for executive decision-making. Visit our source page to download the complete study and secure the intelligence needed to lead in 2026.
Worldwide Aftercooler Market
For detailed analysis of this topic, please visit the official page: Worldwide Aftercooler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com