

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive Coolant Heaters Market to Hit $9.8B by 2032, Growing at 14.28% CAGR

Navigating the Thermal Shift: Strategic Intelligence for the Worldwide Automotive Coolant Heaters Market (2026–2032)
The automotive industry is undergoing a fundamental re-engineering of thermal management. As powertrains transition from internal combustion to electrification, the humble coolant heater has evolved from a simple engine-pre-heating accessory into a critical component of battery thermal management, cabin comfort, and range optimization. For executives navigating capital allocation, supply chain resilience, and product portfolio strategy in 2026, understanding this shift is no longer optional—it is a prerequisite for competitive positioning.
This article serves as a strategic preview of PW Consulting's latest comprehensive study: the Worldwide Automotive Coolant Heaters Market research. Below, we outline the macro trajectory, competitive architecture, and operational intelligence embedded in the full report, while deliberately reserving granular segment splits and forward-looking volume forecasts for the complete intelligence package available on our portal.
Macro Trajectory: A Market in Accelerated Expansion
Drawing on historical performance data spanning 2020 through 2025 and extending our forecast horizon to 2032, the worldwide automotive coolant heater market demonstrates a clear, structurally supported growth curve. The market generated approximately 3,850.5 million USD in revenue during the 2025 base year, building on a consistent upward trajectory from 1,980.45 million USD in 2020. This expansion reflects sustained OEM investment in thermal efficiency, tightening global emission standards, and the rapid scaling of electrified vehicle platforms that demand sophisticated heating architectures.
Our forward-looking models project the market to reach 4,228.64 million USD in 2026, with growth compounding steadily through the end of the forecast period. By 2032, the market is positioned to exceed 9,799.45 million USD, underpinned by a compound annual growth rate of 14.28 percent. This rate is not merely a statistical projection; it reflects the convergence of regulatory pressure, electrification roadmaps, and the operational necessity of maintaining battery health and cabin comfort in sub-optimal temperature regimes.
For corporate strategists, these figures signal more than top-line opportunity. They illuminate a market where timing, technology selection, and regional deployment strategies will determine margin capture. The full report provides the analytical scaffolding to translate these macro numbers into actionable pipeline planning, capacity forecasting, and partnership evaluation.
Structural Shifts and Competitive Architecture
The competitive landscape for automotive coolant heaters is characterized by a concentrated yet dynamically evolving supplier base. Market concentration metrics indicate that the top three players command a combined share of approximately 42.15 percent, while the top five extend their dominance to 61.4 percent. This concentration underscores the capital intensity, certification requirements, and long-cycle OEM relationships that define the sector, while also leaving meaningful whitespace for specialized players and regional champions.
Key Market Participants and Strategic Positioning
The market is anchored by a cohort of established thermal management specialists and global auto-component suppliers, each pursuing differentiated technological and commercial strategies:
- Webasto (Stockdorf, Germany) has built a reputation for engine pre-heating solutions tailored to heavy-duty trucks, while simultaneously expanding its portfolio of high-voltage coolant heaters for hybrid and electric vehicle platforms deployed by global automakers.
- BorgWarner (Auburn Hills, Michigan, USA) has aggressively scaled its high-voltage coolant heater (HVCH) offerings, targeting battery thermal management, cabin heating, and range optimization across xEV, hybrid, and PHEV platforms. Recent contract awards for 400V and 800V architectures underscore its commitment to next-generation electrification roadmaps.
- Valeo (Paris, France) focuses on high-voltage coolant heaters engineered for glycol heating within EV HVAC systems, with design compatibility for heat pump architectures that enhance cabin comfort and system efficiency.
- Eberspächer (Esslingen, Germany) provides both hydronic coolant heaters and high-voltage electric coolant heaters, serving passenger cars, trucks, and commercial vehicles with emphasis on engine pre-heating and interior temperature control.
- Hotstart (Spokane, Washington, USA) maintains a strong footprint in heavy-duty applications, manufacturing in-block and thermosiphon engine coolant heaters for trucks, buses, and industrial engines aimed at reducing cold-start wear.
- Phillips & Temro Industries (PTI) (Eden Prairie, Minnesota, USA) specializes in engine heating solutions, including coolant and block heaters, across automotive, truck, and off-road applications.
- Hebei Nanfeng Group (NF) (China) has emerged as a notable producer of high-voltage PTC coolant heaters in the 3–15kW range, serving electric vehicles, buses, and fuel cell systems.
- VVKB (Victor Industries / Warmda) (China) manufactures PTC coolant heaters and Titan series engine heaters, targeting EVs, buses, and cold-weather vehicle applications.
These companies illustrate a dual-track evolution: legacy players are expanding into high-voltage electric heating to capture electrification demand, while regional manufacturers are scaling PTC-based solutions to serve cost-sensitive and volume-driven segments. The full report maps each competitor's product architecture, target vehicle segments, and reported commercial milestones, enabling buyers and investors to benchmark capability against strategic intent.
Worldwide Automotive Coolant Heaters Market
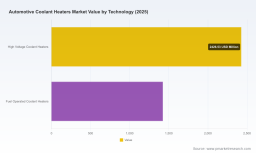
Technology Divergence: High-Voltage Electric vs. Fuel-Operated Systems
A defining feature of the current market cycle is the technological bifurcation between high-voltage coolant heaters and fuel-operated coolant heaters. High-voltage systems, typically leveraging PTC (positive temperature coefficient) ceramic elements or resistive heating technologies integrated with coolant loops, are increasingly central to EV and hybrid thermal management. These systems support battery conditioning, cabin heating, and overall range optimization, with next-generation platforms offering scalable power outputs across 400V and 800V architectures to accommodate diverse vehicle integration requirements.
Fuel-operated coolant heaters, by contrast, continue to hold relevance in commercial and heavy-duty applications where engine pre-heating, reduced cold-start wear, and minimized idling are operational priorities. The interplay between these two technology tracks is not a simple substitution dynamic; rather, it reflects a portfolio logic in which OEMs and tier suppliers must balance electrification mandates, total cost of ownership, and application-specific performance criteria.
The complete study dissects these technology pathways in detail, examining design considerations, certification pathways, integration complexity, and the raw material and component ecosystems that influence cost structures and supply continuity.
Automotive Auxiliary Heater Market
Regulatory Tailwinds and Industry Dynamics
Market expansion is reinforced by a regulatory environment that increasingly favors efficient thermal management. Stringent emission regulations in major markets are driving demand for solutions that support reduced idling and improved cold-start performance across both ICE and xEV vehicles. Simultaneously, Federal Motor Vehicle Safety Standards under 49 CFR Part 571 establish equipment requirements that indirectly shape the design and certification of heating components within automotive systems.
These regulatory currents are compounded by technical evolution. High-voltage coolant heaters for EVs typically rely on PTC ceramic elements or resistive heating technologies, integrated with coolant loops to manage battery and cabin thermal loads. Next-generation platforms are engineered to support scalable power outputs—commonly in the 3–9 kW range—across 400V and 800V architectures, enabling flexible integration within hybrid and electric vehicle thermal systems. For suppliers and OEM procurement teams, these dynamics create both compliance obligations and innovation opportunities, particularly in packaging efficiency, thermal response, and compatibility with broader HVAC and heat pump architectures.
The report's dynamics section contextualizes these forces within a structured framework, helping stakeholders separate temporary market noise from durable demand drivers.
What the Full Report Delivers for 2026 Decision-Making
PW Consulting's Worldwide Automotive Coolant Heaters Market research is designed as an operational intelligence tool, not merely a statistical summary. The complete publication integrates historical performance data, forward-looking forecasts, and segment-level analysis into a decision-ready format. Key components include:
- Market sizing and forecast architecture spanning the 2026–2032 horizon, with clearly documented assumptions, growth drivers, and sensitivity considerations.
- Technology segmentation analysis that distinguishes high-voltage coolant heaters from fuel-operated systems, mapping adoption pathways, performance trade-offs, and application fit.
- Vehicle-type segmentation insights covering passenger cars and commercial vehicles, with attention to differing thermal management requirements, duty cycles, and procurement dynamics.
- Regional market structure that identifies where demand is concentrated, how supply chains are arranged, and which local factors—regulatory, climatic, or industrial—shape deployment patterns.
- Competitive profiling of the leading manufacturers, including product portfolios, technology focus, and recent commercial developments that signal strategic direction.
- Industry context synthesis covering regulatory frameworks, safety standards, raw material and component considerations, and technology evolution trajectories that influence cost, certification, and integration risk.
- Strategic implications tailored for OEMs, tier suppliers, investors, and procurement leaders who need to align product roadmaps, sourcing strategies, and market-entry plans with the realities of a rapidly electrifying thermal management landscape.
Importantly, the full report avoids presenting segments in isolation. Instead, it connects technology choice, vehicle-type demand, and regional deployment into a cohesive analytical narrative, enabling readers to evaluate where value is created, where competition is intensifying, and where differentiation remains achievable.
Why This Intelligence Matters for 2026 Planning
As the 2026 planning cycle unfolds, automotive and supplier executives face a compressed set of decisions. Electrification timelines are firming, thermal management architectures are becoming more complex, and the cost and availability of heating components are increasingly tied to technology selection and supply chain design. In this environment, coarse market estimates are insufficient. Decision-makers need segment-aware forecasts, competitor activity tracking, and a clear view of the regulatory and technical forces that will shape demand over the next several years.
This study is built to meet that need. By combining rigorous historical analysis with structured forward-looking modeling, it provides a baseline for scenario planning, capacity evaluation, and partnership assessment. The macro figures presented here—14.28 percent CAGR, a 2032 market pathway approaching 9,799.45 million USD, and a concentrated yet competitive supplier field—offer a credible starting point. The complete report delivers the segment-level resolution, competitive intelligence, and strategic context required to convert that starting point into executable plans.
Access the Complete Intelligence Package
The overview above is intended to demonstrate the analytical depth and strategic relevance of the full study while preserving the detailed segment splits, regional breakdowns, and forward-looking estimates for the complete publication. For organizations that require precise market sizing by segment, competitor benchmarking, and a documented forecast methodology to support 2026–2032 planning, the full report is available through our research portal.
PW Consulting's Worldwide Automotive Coolant Heaters Market research equips stakeholders with the structured intelligence needed to navigate a market defined by technological transition, regulatory pressure, and accelerating demand for efficient thermal management. We invite you to access the complete report to obtain the granular data, competitive profiles, and strategic analysis that will inform your next cycle of investment, sourcing, and product strategy decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Coolant Heaters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com