

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 3D TOF Market to Hit $21.2B by 2032 as CAGR Hits 18.5%

Unlocking the Depth of Tomorrow: Inside the Worldwide 3D TOF Technology Products Market 2026–2032
The global race for precise depth perception is no longer confined to science fiction or high-end research laboratories. It has become a foundational layer of modern digital infrastructure, driving innovation across consumer electronics, automotive safety, industrial automation, and robotics. As we step into 2026, the Worldwide 3D Time-of-Flight (TOF) Technology Products Market stands at a critical inflection point, characterized by rapid technological maturation, intensifying competitive dynamics, and unprecedented capital deployment. At PW Consulting, our latest comprehensive market intelligence study maps this evolution with surgical precision, offering enterprise decision-makers a strategic compass for navigating the next seven years of transformative growth.
This article serves as a directorial preview of our full report. It outlines the architectural rationale behind our research design, distills the macro-economic currents shaping the industry, and highlights the operational intelligence embedded within our analytical framework. By the end, you will understand not only how large the market is becoming, but why its trajectory demands immediate strategic recalibration from technology providers, system integrators, and investment stakeholders alike.
The Macro Trajectory: From Established Scale to Exponential Expansion
Our longitudinal analysis tracks market performance from 2020 through 2032, capturing both the foundational growth phase and the acceleration period that defines the current cycle. The data reveals a compound annual growth rate of 18.5 percent, a figure that underscores the technology's transition from niche capability to mainstream industrial necessity. In 2025, the market crossed the six-billion-dollar revenue threshold in USD millions, and by 2026, it is projected to approach the eight-billion mark. This is not merely incremental expansion; it represents a structural shift in how machines perceive spatial relationships.
Looking further out, the forecast window paints a picture of compounding momentum. Revenue streams continue to scale through 2030, when the market is expected to surpass fourteen billion dollars, before accelerating toward the twenty-one-billion-dollar range by the close of the forecast period in 2032. Such growth trajectories are rarely driven by a single catalyst. Instead, they emerge from the convergence of hardware readiness, application proliferation, and standardization momentum. Our report dissects each of these drivers, mapping historical revenue baselines against forward-looking adoption curves to help organizations stress-test their pipeline strategies against realistic demand scenarios.
Crucially, the market's expansion is not uniformly distributed across all dimensions. The analytical architecture of our study segments the landscape across multiple operational axes, enabling clients to isolate high-velocity pockets without losing sight of the broader ecosystem. Rather than presenting static tables, we embed these dimensions into dynamic growth narratives, illustrating how component supply chains, device architectures, vertical adoption patterns, and regional deployment ecosystems interact to create compounding value chains. This multi-axis approach ensures that strategic planning accounts for cross-segment dependencies rather than isolated market snapshots.
Navigating a Consolidated Competitive Arena
A defining characteristic of the current landscape is the pronounced concentration of market share among established technology leaders. Our analysis indicates that the top three players command approximately 48.5 percent of total revenue, while the top five collectively control over 62 percent. This concentration reflects decades of cumulative R&D investment, deeply embedded customer relationships, and the high barriers associated with achieving automotive-grade reliability or mass-production scalability. Yet concentration does not equate to stagnation. The competitive arena remains highly dynamic, with incumbents continually refreshing their portfolios while niche specialists carve out defensible positions through architectural specialization.
STMicroelectronics continues to anchor its position through the FlightSense family of direct ToF sensors, with the VL53L series delivering reliable ranging capabilities across smartphone, robotics, and industrial automation applications. Their recent enhancements to the VL53L8CX multi-zone architecture, showcased at Embedded World in early 2024, demonstrate a clear focus on ambient light immunity and spatial resolution improvements. Meanwhile, ams OSRAM has expanded its multi-zone footprint with the TMF8821 six-zone sensor, targeting compact gesture and proximity applications in consumer electronics and automotive interfaces. Their TMF88xx lineage reinforces a strategic emphasis on user interaction and human-machine interface refinement.
Infineon Technologies has steadily advanced its indirect ToF portfolio, particularly through the REAL3 IRS series, with the IRS1051C emerging as a reference architecture for 3D depth imaging in automotive ADAS and robotic perception stacks. Their demonstration of next-generation REAL3 capabilities at CES 2024 signaled a clear trajectory toward automotive-grade 3D perception. Sony Semiconductor Solutions has similarly reinforced its position through stacked CMOS ToF image sensors such as the IMX556 and IMX459, engineered for high-resolution 3D sensing in mobile and automotive environments. The IMX556's achievement of AEC-Q100 Grade 2 automotive qualification in mid-2023 marked a pivotal step in bridging consumer-grade performance with automotive reliability requirements.
The competitive field extends well beyond these anchor players. pmdtechnologies specializes in indirect ToF camera modules like PicoFlexx and CamBoard nano, with a strong footprint in industrial 3D vision and AR/VR reference designs. Their September 2023 partnership to integrate ToF technology into new AR glasses architectures highlights the growing symbiosis between spatial sensing and wearable computing. Texas Instruments supplies OPT3101 and OPT8241 ToF-QVGA sensors tailored for multi-zone distance measurement in drones and IoT deployments. OmniVision Technologies delivers the OV01D10 RGBIr ToF sensor, optimized for front-facing 3D facial recognition in smartphones, while Basler AG manufactures blaze-101 and blaze-202 indirect ToF 3D cameras for factory automation and logistics workflows. Lucid Vision Labs produces the Helios2+ ToF 3D camera, delivering 30,000 points per second for machine vision in robotics, and ifm electronic offers the O3D3xx series for industrial position detection and volume measurement.
Our report does not merely catalogue these profiles. It maps their strategic postures, evaluates their product roadmaps against emerging application demands, and assesses how their positioning influences pricing architecture, supply chain resilience, and partnership ecosystems. Understanding this competitive topology is essential for organizations seeking to align their technology procurement, co-development initiatives, or market entry strategies with the players best suited to their specific operational requirements.
Structural Dynamics: The Forces Shaping Adoption Velocity
Market growth is rarely a straight line. It is mediated by technical constraints, regulatory expectations, standardization momentum, and ethical considerations that collectively determine how quickly a technology transitions from prototype to production. Our study integrates these structural dynamics into actionable intelligence, enabling stakeholders to anticipate friction points before they materialize into bottlenecks.
On the hardware frontier, resolution constraints remain a defining challenge for indirect ToF architectures. Current indirect ToF sensors are largely bounded by VGA resolution, a limitation driven by SPAD array complexity and readout speed trade-offs. This technical ceiling shapes application suitability, influencing which use cases can be served cost-effectively today versus which require architectural breakthroughs tomorrow. Conversely, direct ToF systems have demonstrated the ability to maintain error rates below five percent even under intense ambient light conditions, with modulated laser configurations at 940nm enabling reliable performance in environments approaching 100 kilolux sunlight. These contrasting performance profiles underscore why device-type segmentation remains a critical strategic variable.
Regulatory and standardization developments are equally consequential. Automotive ToF sensors must now align with ISO 26262 ASIL-B functional safety requirements for ADAS applications, a mandate that elevates qualification costs but simultaneously raises the barrier to entry, favoring players with established automotive engineering pipelines. On the interface side, the MIPI I3C specification has emerged as a standardized pathway for high-speed ToF sensor data transfer in mobile devices, reducing integration friction and accelerating time-to-market for smartphone and wearable manufacturers. These standardization efforts compress development cycles but also require suppliers to maintain specification compliance as the ecosystem matures.
Beyond engineering and regulation, ethical considerations are beginning to shape deployment architectures. Privacy concerns have prompted guidance that limits ToF usage in consumer devices to opt-in depth sensing models, explicitly avoiding raw point cloud export without user consent. This direction influences how manufacturers design data pipelines, how service providers structure value propositions, and how enterprise customers evaluate risk exposure when deploying depth-sensing technologies in public or semi-public environments. Our report contextualizes these dynamics within broader adoption frameworks, helping organizations design compliant, defensible deployment strategies.
Inside the Report: Operational Intelligence for Strategic Execution
A market research publication is only as valuable as its ability to translate macro trends into operational decisions. Our study is engineered to serve as a working document for product strategy, investment allocation, supply chain planning, and competitive positioning. Rather than offering generic commentary, we embed structured analytical modules that map directly to enterprise decision workflows.
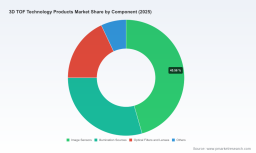
At the core of the report lies a multi-dimensional segmentation architecture that traces revenue flows across device architectures, component categories, vertical applications, and geographical deployment ecosystems. Each dimension is analyzed through the lens of growth drivers, adoption barriers, and supply chain interdependencies. Device-type analysis contrasts the trajectory of direct ToF versus indirect ToF architectures, evaluating where each excels, where integration challenges persist, and how performance trade-offs influence end-market suitability. Component-level analysis disentangles the revenue contributions of image sensors, illumination sources, optical filters and lenses, and ancillary elements, revealing where value accumulation is shifting as system designs mature.
Vertical application mapping provides a granular view of how depth-sensing technologies are penetrating consumer electronics, automotive platforms, industrial and healthcare environments, and robotics and drone ecosystems. Rather than presenting static share percentages, we examine the functional requirements driving adoption in each vertical, the qualification thresholds that govern market entry, and the partnership models that accelerate integration. This approach equips technology suppliers with vertical-specific go-to-market insights and enables system integrators to identify high-probability deployment opportunities aligned with their existing capabilities.
Competitive analysis is structured to support both offensive and defensive strategy formulation. We profile the strategic postures of the leading participants, assess their product evolution trajectories, and map recent developments that signal shifting priorities. Recent milestones, such as STMicroelectronics' enhanced multi-zone sensor showcase, ams OSRAM's six-zone sensor release, Infineon's automotive perception demonstration at CES, pmdtechnologies' AR glasses integration partnership, and Sony's automotive qualification achievement, are contextualized within broader strategic narratives. These events are not isolated news items; they are indicators of where R&D capital is flowing, which performance benchmarks are being prioritised, and how differentiation is being constructed across the value chain.
The report also integrates supply chain and standardization intelligence that directly affects procurement strategy and product roadmapping. By examining interface specifications, functional safety mandates, and resolution evolution timelines, we provide a forward-looking view of where integration complexity will decrease and where new barriers will emerge. This intelligence is particularly valuable for organizations planning multi-year platform architectures, as it enables them to anticipate component availability shifts, qualification pathway changes, and interface migration requirements before they disrupt development schedules.
3D Time-of-flight Image Sensors Market
Strategic Imperatives as the Market Enters Its Growth Acceleration Phase
As the market crosses the eight-billion-dollar revenue threshold in 2026 and accelerates toward the twenty-one-billion-dollar range by 2032, organizations face a narrowing window to align their strategies with structural growth vectors. The convergence of automotive perception requirements, industrial automation demand, consumer electronics integration, and robotics deployment is creating a multi-vector growth environment that rewards early positioning and penalizes late-stage reaction.
For technology providers, the imperative is to clarify where their architectures deliver comparative advantage and to align product roadmaps with the verticals where performance boundaries are being pushed fastest. For system integrators and OEMs, the focus must shift from technology curiosity to integration readiness, encompassing qualification pathways, interface standardization, supply chain resilience, and ethical data handling architectures. For investors and strategic partners, the opportunity lies in identifying where concentration dynamics are beginning to loosen and where specialized capabilities can command premium positioning within consolidated ecosystems.
The full report provides the depth, structure, and forward-looking intelligence necessary to execute these strategies with precision. It offers the analytical scaffolding required to evaluate market entry timing, prioritize R&D allocation, negotiate supply chain arrangements, and anticipate competitive responses. By transforming macro growth trajectories into operational decision frameworks, it enables organizations to move beyond observation into active market participation.
Accessing the Full Intelligence Base
Market intelligence of this scope is designed to serve as a foundational reference for strategic planning, product portfolio optimization, and competitive positioning. The preview outlined here captures the analytical philosophy, structural dimensions, and strategic relevance of the study, but the complete report contains the detailed segmentation architecture, competitive profiling, standardization mapping, and forward-looking scenario analysis required for execution-level decision-making. Organizations seeking to align their strategies with the accelerating trajectory of 3D TOF technology will find that the full intelligence base provides the granularity, contextual depth, and actionable framing necessary to navigate a market defined by rapid technical evolution, consolidated competition, and multi-vertical adoption momentum.
Worldwide 3D TOF Technology Products Market
The Worldwide 3D TOF Technology Products Market is no longer an emerging niche. It is a scaling infrastructure layer with measurable revenue momentum, clear competitive topology, and decisive structural dynamics. Understanding its architecture is the first step toward shaping your position within it.
For detailed analysis of this topic, please visit the official page: Worldwide 3D TOF Technology Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com