

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Oat Cereal Market Hits $14,250M in 2025, Projects 5.34% CAGR to 2032

Strategic Horizons: The Worldwide Oat-based Cereal Market Outlook for 2026 and Beyond
The global breakfast landscape is undergoing a fundamental transformation, driven by a confluence of health consciousness, shifting dietary preferences, and supply chain complexities. As we move into 2026, the oat-based cereal sector stands at a critical inflection point. For corporate strategists, category managers, and investment analysts, understanding the nuanced trajectory of this market is no longer optional—it is a prerequisite for sustainable growth.
Our latest comprehensive study, the Worldwide Oat-based Cereal Market analysis, offers a definitive look at the industry from the base year 2025 through the forecast period extending to 2032. This report is designed to equip decision-makers with the granular intelligence needed to navigate competitive pressures, regulatory shifts, and evolving consumer behaviors.
Macro Market Trajectory and Financial Forecasting
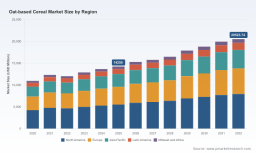
The financial narrative of the oat-based cereal market is one of resilient expansion. Historical data from 2020 to 2025 illustrates a sector that has not only recovered from global disruptions but has cemented its position as a staple in modern diets. Starting from a revenue base of approximately 10.95 billion USD in 2020, the market has climbed steadily, reaching an estimated 14.25 billion USD by 2025.
Looking forward, the momentum is set to accelerate, albeit at a measured pace that reflects market maturity. The forecast period from 2026 to 2032 projects continued growth, with the market valuation expected to surpass the 15 billion USD threshold in 2026 and approach nearly 20.5 billion USD by the end of the forecast window. This trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 5.34 percent.
For strategic planners, this CAGR signals a market that is growing faster than traditional packaged food categories but requires careful capital allocation. The incremental value creation over the next seven years suggests that while volume growth is present, value optimization through premiumization and innovation will be the primary drivers of profitability. Companies relying solely on commodity pricing strategies risk erosion in a market increasingly defined by differentiated health benefits and clean label attributes.
Segmentation Dynamics: Product and Distribution
Success in 2026 will depend heavily on how organizations align their product portfolios with specific consumption occasions. The market is not monolithic; it is fragmented across distinct product types that serve different nutritional needs and lifestyle contexts.
Rolled oats and steel-cut oats continue to represent a substantial portion of the revenue mix, appealing to consumers seeking minimally processed, whole-grain options. However, the convenience factor cannot be overstated. Ready-to-Eat (RTE) oat cereals remain a dominant force, particularly in markets where morning time poverty drives purchasing decisions. Meanwhile, granola and muesli categories cater to the snackification trend and premium breakfast segments, often commanding higher price points. Instant oat porridge serves a niche but loyal demographic focused on speed and comfort.
Distribution channels tell a parallel story of evolution. Traditional grocery retail, specifically supermarkets and hypermarkets, still accounts for the largest share of revenue flow. Yet, the digital shift is undeniable. Online retail channels have carved out a significant portion of the market, reflecting a long-term change in how consumers discover and purchase breakfast items. Convenience stores capture the on-the-go segment, while other channels provide niche access points.
Our report delves into the specific revenue contributions of each segment without relying on high-level aggregates that obscure actionable insights. We analyze the velocity of growth within each category, helping clients identify which product types are gaining traction in specific economic climates and which distribution channels offer the highest return on investment for new product introductions.
Regional Perspectives and Trade Complexities
Geographically, the market exhibits distinct maturity levels and growth drivers. North America remains a cornerstone of global revenue, supported by entrenched brand loyalty and high consumption rates of oat-based breakfast items. Europe follows as a major contributor, where regulatory frameworks and health claims play a pivotal role in product formulation and marketing.
The Asia Pacific region represents a distinct opportunity matrix. While current revenue volumes are lower compared to Western markets, the growth trajectory is influenced by rising disposable incomes and increasing awareness of functional foods. Latin America and the Middle East and Africa regions contribute to the global total with unique dynamics, often influenced by import dependencies and currency fluctuations.
Trade policies and raw material availability further complicate the regional landscape. For instance, import duties and trade agreements under frameworks like USMCA influence the cost structure for manufacturers relying on cross-border oat sourcing. Additionally, agricultural variables, such as acreage changes and yield fluctuations, directly impact input costs. Recent data indicates that oat prices in key producing regions have faced upward pressure due to reduced acreage, signaling potential margin compression for manufacturers who have not secured long-term supply contracts.
Understanding the interplay between regional demand density and supply side constraints is vital. The report provides a detailed breakdown of regional revenue contributions and growth rates, allowing strategists to assess market attractiveness and prioritize geographic expansion or contraction strategies accordingly.
Competitive Landscape and Strategic Positioning
The industry is characterized by a mix of global conglomerates and specialized niche players. Market concentration metrics indicate a moderately consolidated environment, with the top three players holding a significant share of the market and the top five commanding a majority. This structure suggests that while scale offers advantages in distribution and procurement, there is ample room for specialized brands to thrive through differentiation.
Key corporations such as General Mills and PepsiCo, through its Quaker Oats division, maintain strong positions with iconic brands that have global recognition. General Mills continues to leverage its Cheerios portfolio, recently introducing variants like Very Berry Cheerios to refresh the product line and attract flavor-seeking consumers. PepsiCo remains a formidable force with its extensive range of oat-based RTE cereals and snacks, though it has faced operational challenges. In late 2023, the company underwent an expanded recall of Quaker Oats granola bars and cereals due to potential Salmonella contamination, an event that highlighted the critical importance of supply chain safety and quality control in maintaining consumer trust.
WK Kellogg Co and Post Holdings continue to compete with strong oat-infused offerings within their broader cereal portfolios. Post Holdings, for example, positions its Uncle Sam Original Cereal as a high-fiber option, targeting the health-conscious segment.
In the natural and organic space, companies like Nature's Path Foods and Bob's Red Mill Natural Foods have carved out loyal followings. Nature's Path showcased new innovations such as Heritage Crunch at major industry events like Natural Products Expo West, signaling their commitment to organic integrity and flavor diversification. Bob's Red Mill focuses on whole grain integrity, appealing to consumers who prioritize ingredient transparency.
International presence is also shaped by players like Weetabix Ltd in the UK, whose Oatibix products are popular in Europe, and Nestlé, which adapts oat-based offerings like Fitness Oats for international markets. The Hero Group, through its Jordans and Dorset Cereals brands, maintains a strong foothold in the granola and muesli segments with premium positioning.
Our competitive analysis goes beyond brand listings. We examine the strategic moves, recent developments, and potential vulnerabilities of these key entities. By understanding the moves of competitors—whether it is a product launch aimed at capturing a flavor trend or a recall that disrupts supply—we help clients anticipate market shifts and position their own offerings to capitalize on gaps or defend market share.
Regulatory Environment and Health Claims
Regulation is a key determinant of product formulation and marketing efficacy in the oat-based cereal sector. Health claims related to oats, specifically the soluble fiber beta-glucan, are central to the value proposition of these products.
In the United States, FDA mandates regarding Nutrition Facts label updates require manufacturers to highlight specific nutritional attributes. The ability to make heart health claims linked to beta-glucan is a significant marketing lever, provided products meet the necessary compositional standards. Similarly, in the European Union, regulations authorize oat beta-glucan health claims on cereals when a minimum threshold of 0.75 grams per portion is met. Compliance with these standards is not merely a legal requirement but a competitive necessity for brands wishing to communicate functional benefits to consumers.
Furthermore, the regulatory landscape influences ingredient sourcing and labeling. As consumers become more educated about nutrition, the alignment between regulatory allowances and consumer expectations creates a framework where compliance drives innovation. Our report details the specific regulatory requirements across key regions, ensuring that product development teams and legal compliance officers have the information needed to navigate these complexities without risking reformulation costs or labeling violations.
Strategic Implications for 2026 Decision-Making
As organizations plan their strategies for 2026, several critical questions must be addressed. How will the 5.34 percent CAGR translate into category growth for specific brands? Which distribution channels will yield the highest margin expansion in an era of rising input costs? Can organic and specialty oat cereals continue to outpace conventional growth rates, or will mainstream adoption narrow the gap?
The Worldwide Oat-based Cereal Market report provides the answers to these questions through a rigorous analysis of historical performance and forward-looking indicators. It offers a complete view of the market size, segmented by region, product type, and distribution channel, along with a detailed competitive landscape that includes company profiles, recent developments, and market concentration data.
The strategic value of this intelligence lies in its granularity. High-level market estimates are insufficient for making decisions about capacity expansion, R&D investment, or M&A targets. Leaders need to know the exact revenue dynamics, the specific growth rates of sub-segments, and the precise market share positions of competitors. This report delivers that depth.
With the forecast period extending to 2032, this study also supports long-term capital planning. It allows stakeholders to model different scenarios based on potential changes in raw material costs, regulatory shifts, and consumer trend adoption. Whether you are a multinational corporation looking to optimize your global footprint or a regional player seeking to identify entry points, the data provided is structured to feed directly into strategic planning processes.
Oat Flakes Market
Conclusion: Navigating the Future of Oat-Based Nutrition
The oat-based cereal market is not just a breakfast category; it is a barometer for broader shifts in health, convenience, and sustainability. The projected growth to nearly 20.5 billion USD by 2032 underscores the enduring appeal of oats as a foundational food. However, capturing this value requires more than passive observation of market trends. It demands proactive strategy informed by precise data.
From the impact of raw material price volatility on margins to the nuances of health claim regulations in different jurisdictions, every variable affects the bottom line. The competitive intensity, exemplified by the activities of market leaders and niche innovators alike, means that standing still is not an option.
We invite industry leaders, investors, and strategic planners to review the full findings of the Worldwide Oat-based Cereal Market research. The complete report contains the detailed segmentation data, regional breakdowns, and competitive profiles necessary to turn these market insights into actionable business outcomes. Access the full intelligence to ensure your organization is positioned to lead in the evolving oat-based cereal landscape.
Worldwide Oat-based Cereal Market
For detailed analysis of this topic, please visit the official page: Worldwide Oat-based Cereal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com