

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive FPC Market to Hit $7.37B by 2032, 16% CAGR

The Flexible Backbone of Electrification: Strategic Imperatives in the Worldwide Automotive FPC Market
The automotive industry is undergoing a structural transformation unlike any seen in the past decade. As electrification accelerates and vehicles evolve into complex networks of electronic systems, the demand for lightweight, reliable connective solutions has never been more critical. Flexible Printed Circuits (FPCs) have emerged as the invisible backbone of this shift, enabling the compact integration required for modern battery management, advanced driver assistance systems, and digital cockpits. For strategic planners and C-suite executives, understanding the trajectory of this market is no longer optional—it is a prerequisite for navigating the competitive landscape of 2026 and beyond.
Worldwide Automotive FPC Market
Our latest research, the Worldwide Automotive FPC Market study, provides a comprehensive lens into this rapidly expanding sector. Covering historical performance from 2020 through the base year of 2025 and offering a detailed forecast period extending to 2032, this report is designed to inform high-stakes decision-making. By synthesizing macro-economic trends, competitive dynamics, and technological requirements, we offer a roadmap for stakeholders looking to capitalize on the growth opportunities inherent in automotive electronics.
Market Trajectory and Growth Dynamics
A Decade of Expansion
The historical data tells a story of consistent and accelerating growth. From a market size of approximately 1.05 billion USD in 2020, the automotive FPC sector has expanded steadily, reaching an estimated 2.61 billion USD by 2025. This trajectory reflects the broader industry pivot toward electric vehicles (EVs) and the increasing electronic content per vehicle. The compound annual growth rate (CAGR) projected for the forecast period stands at a robust 16.0 percent, signaling that the momentum is not slowing down.
FPC Market
Looking forward, the revenue projections suggest a significant upscale in valuation. By 2032, the market is anticipated to reach over 7.37 billion USD. This growth is not merely linear; it is driven by multiplicative factors such as the proliferation of sensors, the complexity of powertrain electronics, and the standardization of connectivity features across vehicle segments. For investors and supply chain managers, this forecast underscores the long-term viability of FPC investments despite short-term volatility.
Regional and Structural Shifts
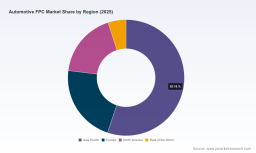
While specific regional breakdowns are detailed within the full report, it is evident that the Asia Pacific region continues to hold a substantial share of the market volume, driven by the density of automotive manufacturing hubs and EV adoption rates in key territories. However, growth is not confined to a single geography. European and North American markets are seeing renewed interest in localized supply chains, influenced by regulatory pressures and the desire for supply chain resilience.
Structurally, the market is seeing a divergence in layer type preferences. Multi-layer and double-sided FPCs are gaining traction as vehicles require higher density interconnects to support advanced computing needs. Meanwhile, rigid-flex solutions are carving out a niche in applications demanding extreme durability and space efficiency. Understanding the blend of these layer types is essential for suppliers positioning their manufacturing capabilities for future demand.
Application-Driven Demand
The demand for automotive FPCs is deeply tied to specific vehicle functions. Battery Management Systems (BMS) represent a primary growth engine, as the complexity of monitoring and managing high-voltage systems in EVs requires sophisticated, flexible circuitry. Similarly, the rise of ADAS and sensors has created a surge in demand for FPCs that can withstand harsh environmental conditions while maintaining signal integrity. Infotainment and cockpit displays, along with lighting and powertrain systems, further diversify the application landscape, ensuring that demand streams are not overly reliant on a single vehicle component.
Competitive Landscape and Key Players
Consolidation and Capability
The market exhibits moderate concentration, with key players commanding a significant portion of the revenue share. This consolidation reflects the high barriers to entry associated with automotive-grade certifications and the need for consistent quality at scale. Our report analyzes the strategic positioning of leading firms, including Nitto Denko Corporation and Sumitomo Electric Industries from Japan, who have long-established themselves as suppliers of high-reliability FPCs for instrument panels, airbags, and ADAS platforms.
In the Asian manufacturing sphere, companies like Zhen Ding Technology and Flexium Interconnect are leveraging their scale to serve the booming EV battery and display sectors. Zhen Ding, for instance, has been pivotal in producing FPCs for electric vehicle battery packs and high-speed data transmission. Meanwhile, Nippon Mektron specializes in multilayer FPCs critical for cameras, LIDAR, and battery management systems, positioning itself heavily in the autonomous driving value chain. Interflex Co., Ltd. from South Korea contributes to the ecosystem by supplying FPCs for touch panels and power distribution, while US-based Multi-Fineline Electronix (MFLEX) offers custom solutions for wearables integration and advanced driver assistance. Fujikura Ltd. rounds out the competitive field with a focus on wire harness replacement and high-frequency signal transmission.
Strategic Moves and Recent Developments
The competitive dynamics are further shaped by recent strategic moves that signal where the market is heading. In late 2025, Nitto Denko launched a high-reliability FPC series specifically for EV battery monitoring systems, ensuring compliance with AEC-Q100 standards. This move highlights the industry's focus on safety and reliability in high-voltage environments. Around the same time, Sumitomo Electric was nominated by a major OEM for FPC supply in next-generation ADAS platforms, reinforcing the importance of securing tier-1 supplier status for future technology stacks.
Collaborative development is also becoming a key theme. Nippon Mektron entered a joint development agreement with a European automaker in early 2025 to produce multilayer FPCs for autonomous driving sensors. Such partnerships suggest that the future of the market will rely heavily on co-engineering and close integration between component suppliers and vehicle manufacturers. Furthermore, validation testing completed by Zhen Ding Technology for FPCs integrated into solid-state battery packs indicates that the technology is evolving in lockstep with battery chemistry advancements.
Industry Dynamics: Risks and Regulations
Raw Material Volatility
Strategic planning must account for external pressures on the supply chain. Raw material costs have become a significant variable in recent periods. Copper foil prices, essential for FPC production, have seen sharp increases due to supply chain constraints and mining disruptions. Additionally, polyimide film supply, critical for high-temperature FPC applications, faces cost pressures from petrochemical feedstock volatility. These input cost fluctuations can compress margins if not managed through strategic sourcing or value engineering.
Labor and Production Constraints
Beyond materials, labor dynamics are influencing production economics. A skilled labor shortage in Asia-Pacific FPC assembly lines has been reported to increase production costs, adding another layer of complexity to cost modeling. For manufacturers, this necessitates investments in automation and workforce development to maintain competitiveness without sacrificing quality.
Regulatory Compliance as a Competitive Moat
Regulatory requirements are tightening, creating both challenges and opportunities. The ISO 26262 functional safety standard mandates ASIL-B compliance for automotive FPCs in safety-critical applications such as airbags. Compliance with these standards is becoming a differentiator, as OEMs prioritize suppliers who can guarantee functional safety. Additionally, EU Regulation 2019/2144 requires enhanced cybersecurity for electronic components, including FPCs, in connected vehicles. Navigating this regulatory landscape requires a proactive approach to quality assurance and design security, effectively raising the bar for market entry.
Strategic Value for 2026 Decision-Making
Why This Research Matters
In an environment defined by rapid technological change and supply chain reconfiguration, access to accurate, forward-looking intelligence is a strategic asset. This report goes beyond surface-level trends to provide actionable insights into market sizing, segmentation logic, and competitive behavior. It is designed to help stakeholders answer critical questions: Where should capital be allocated for capacity expansion? Which application segments offer the highest margin potential? How are regulatory shifts likely to reshape supplier requirements?
The inclusion of historical data from 2020 to 2025 allows for a robust analysis of post-pandemic recovery and the acceleration of EV adoption trends. The forecast period through 2032 provides a long-enough horizon to plan for product development cycles and infrastructure investments. By understanding the interplay between layer types, applications, and regional dynamics, companies can tailor their strategies to capture value in high-growth niches while mitigating exposure to volatile segments.
Operational and Investment Insights
For operations leaders, the report offers context on the factors influencing cost structures, from raw material trends to labor availability. This enables more accurate budgeting and risk assessment. For investors, the market concentration data and profiles of key competitors provide a framework for evaluating the stability and growth potential of firms within the sector. The detailed examination of recent developments, such as joint ventures and product launches, offers a real-time view of how industry leaders are responding to market signals.
Furthermore, the analysis of application-specific demand helps identify where innovation is most needed. Whether it is the durability required for powertrain systems or the signal integrity needed for infotainment displays, understanding the technical requirements of each segment allows for targeted R&D investment. The report serves as a bridge between high-level market data and the granular details required for execution.
Conclusion: Navigating the Future
The Worldwide Automotive FPC Market is poised for significant expansion, driven by the electrification of transport and the increasing digitization of the vehicle experience. However, realizing growth in this environment requires more than just capacity; it demands strategic agility, regulatory foresight, and a deep understanding of the competitive landscape.
Our comprehensive market study is engineered to provide that understanding. It equips decision-makers with the data and analysis needed to formulate robust strategies for 2026 and the years leading up to 2032. To access the full suite of forecasts, detailed segmentation analysis, and complete competitive profiles, we invite you to visit the source page. There, you will find the complete intelligence necessary to turn market complexity into strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive FPC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com