

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Power Regulator Market Hits $3.1B in 2025, Projects 6% CAGR to $4.68B by 2032

Global Distribution Power Regulator Market: Strategic Imperatives for 2026 and Beyond
As distribution networks worldwide confront the dual pressures of aging infrastructure and the rapid integration of distributed energy resources, voltage regulation has emerged as a decisive factor in grid reliability and operational efficiency. The Worldwide Distribution Power Regulator Market is undergoing a structural transformation, driven by utility modernization programs, renewable energy expansion, and evolving equipment standards. For executives navigating capital allocation, procurement strategy, and long-term grid planning, a rigorous, forward-looking market assessment is no longer optional. The latest PW Consulting Worldwide Distribution Power Regulator Market study delivers precisely the intelligence required to convert macroeconomic shifts into executable corporate strategy for 2026 and beyond.
Macro Trajectory: A Six Percent Growth Engine in a Constrained Supply Environment
The market has demonstrated consistent expansion across the historical assessment window, steadily advancing from 2,938.94 million USD in 2024 to 3,115.28 million USD in 2025. This momentum establishes a clear baseline as the industry enters the forecast period. Looking ahead, the market is projected to grow at a compound annual growth rate of 6.0 percent through 2032, culminating in a total addressable size of 4,684.23 million USD by the final forecast year. Such a trajectory signals more than incremental demand; it reflects a structural recalibration of how distribution grids manage voltage stability in an era of bidirectional power flows, intermittent generation, and digitalized control architectures.
For strategic planners, this growth curve provides a reliable foundation for capacity expansion, product roadmap alignment, and regional investment prioritization. However, translating top-line forecasts into actionable decisions requires a granular understanding of technology adoption curves, application-specific procurement cycles, and regional demand heterogeneities. These layers of insight demand a dataset that moves beyond headline figures to expose the operational mechanics of the market. The full PW Consulting report dissects these dimensions with the granularity necessary for scenario modeling, allowing leadership teams to align their 2026 budgets and long-term capital plans with realistic demand trajectories.
Technology Shifts and Application Dynamics Reshaping Procurement
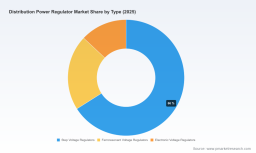
Voltage regulation technology is no longer a homogeneous utility commodity. The market is increasingly defined by divergent adoption patterns across equipment types, each carrying distinct performance profiles, cost structures, and integration requirements. Traditional electromechanical solutions continue to anchor many distribution networks, particularly where proven reliability and field-proven service records remain paramount. Simultaneously, newer electronic and ferroresonant alternatives are gaining traction in applications demanding tighter voltage control, reduced footprint, and enhanced responsiveness to fluctuating load conditions.
Worldwide Distribution Power Regulator Market
On the application side, utility networks remain the dominant consumption pillar, reflecting the ongoing imperative to maintain voltage profiles across expansive transmission and distribution corridors. Industrial facilities follow as a significant demand driver, where process-sensitive operations require stable power quality to avoid costly production interruptions. Commercial and residential deployments, while representing a smaller share of total volume, are gaining strategic relevance as distributed generation, electric vehicle charging infrastructure, and behind-the-meter storage reshape local distribution dynamics. Each application segment carries unique procurement rhythms, specification requirements, and total-cost-of-ownership considerations that directly influence vendor selection and project financing.
Copper price exposure adds another critical variable to the investment calculus. Commodity forecasts indicate that copper is expected to average approximately 11,400 USD per tonne in 2026 under base-case assumptions, directly influencing the cost structure of windings, magnetic components, and associated transformer-adjacent equipment. Companies that fail to integrate commodity trajectory analysis into their sourcing and pricing strategies risk margin compression, particularly in contracts with fixed-price clauses or long-lead procurement commitments.
Competitive Landscape: Concentration, Capability, and the Esports of Innovation
The distribution power regulator market is characterized by a moderately concentrated competitive structure, with the top three players collectively commanding roughly 42.15 percent of revenue and the top five firms accounting for approximately 58.6 percent. This concentration level suggests a market where scale, established utility relationships, and certified reliability records confer meaningful advantages, yet it also leaves sufficient space for specialized manufacturers and regional players to compete on technical differentiation, lead-time performance, and application-specific engineering support.
Several globally recognized organizations anchor the competitive field. ABB Ltd. continues to position voltage regulation within its broader electrification and grid solutions portfolio, emphasizing network-wide stabilization for utility distribution systems. Eaton Corporation Plc, including its Cooper Power Series heritage, provides single-phase and substation-grade regulators with advanced control logic tailored for modern distribution voltage management. Siemens AG and Siemens Energy leverage a long engineering lineage, offering regulators designed for dependable voltage stabilization and seamless integration with renewable generation assets. GE Vernova supplies pole-mounted and substation solutions that align with IEEE C57.15 specifications and incorporate reverse power flow capability, a critical requirement as distributed generation proliferates on distribution circuits. Schneider Electric SE delivers regulation capabilities embedded within medium-voltage distribution equipment, serving both utility and industrial end users. Hitachi Energy has expanded its line voltage regulator portfolio, including booster and feeder-based technologies that support low- and medium-voltage grids, and notably introduced its Compact Line Voltage Regulator at CIRED 2025 as a transformer-integrated approach to active voltage control.
Beyond these multinational incumbents, a diverse group of specialized and regional manufacturers strengthens the supply ecosystem. Howard Industries Inc. focuses on distribution transformers and regulators for utility power distribution systems. Toshiba Corporation and Daihen Corporation bring voltage regulation within broader energy systems and power-sector equipment portfolios. Maschinenfabrik Reinhausen GmbH’s TAPCON series underscores the importance of precision control and communication-ready architectures for distribution network voltage regulation. Belotti Variatori SRL, Hubbell Incorporated, Mitsubishi Electric Corporation, TBEA Co., Ltd., Rockwill Electric Group, and TSI Power Corporation each contribute specialized capabilities, from industrial-grade regulation and pole-mounted step regulators to precision automatic units for critical indoor and outdoor applications. This breadth of players means that procurement teams must evaluate not only brand recognition but also certification pathways, communication protocol compatibility, regional service networks, and the ability to meet evolving grid-code expectations.
Regulatory and Technical Standards as Strategic Filters
Compliance and interoperability are no longer back-office concerns; they are primary drivers of specification writing, vendor qualification, and project approval. Distribution voltage regulators must satisfy IEEE C57.15 performance expectations, while enclosure designs frequently require NEMA 4 protection for harsh outdoor environments. Reliability validation often references KEMA certification, particularly where equipment is expected to sustain performance across up to 2 million mechanical operations. These standards shape not only technical feasibility but also insurance requirements, warranty structures, and long-term maintenance planning.
Worldwide Distribution Meter Market
At the same time, distribution grids are increasingly governed by grid-code requirements that mandate voltage stability despite rising renewable penetration and distributed generation. Equipment must be capable of managing reverse power flow conditions, maintaining acceptable voltage profiles during fluctuating export scenarios, and integrating with broader distribution automation ecosystems. Communication interoperability has become a decisive differentiator. Solutions that support protocols such as IEC 61850, IEC 60870-5-101/103, DNP3, and MODBUS are better positioned for seamless integration into modern control architectures, enabling utilities and large industrial operators to deploy adaptive voltage management strategies rather than relying on static, set-and-forget installations.
What the Full Study Unlocks for 2026 Decision-Making
While the macroeconomic direction and competitive structure are clear, the operational details that determine winning strategies reside in the deeper analytical layers of the report. The complete PW Consulting Worldwide Distribution Power Regulator Market study provides a comprehensive, decision-ready architecture that includes:
- Historic performance benchmarking across the 2020 to 2025 assessment window, establishing baseline demand patterns and enabling precise year-over-year progression analysis.
- Forecast modeling that extends through 2032, with breakdowns that illuminate how growth materializes across equipment categories, end-use applications, and geographic markets without oversimplifying regional dynamics.
- Technology-type analysis that distinguishes adoption drivers, substitution risks, and specification trends across step voltage regulators, ferroresonant units, and electronic regulators, helping R&D and product management teams align roadmaps with demand realities.
- Application-level insights that separate utility procurement cycles from industrial and commercial/residential demand behavior, supporting more accurate sales forecasting, channel strategy, and service-level agreements.
- Competitive profiling that evaluates the strategic positioning, technology focus, and operational strengths of key participants, enabling M&A scanning, partnership identification, and competitive response planning.
- Recent development tracking, including product launches and technology announcements such as transformer-integrated compact regulator solutions, which signal where incumbents are directing innovation investment.
- Regulatory and standards mapping that ties IEEE, NEMA, KEMA, and grid-code expectations to specification language and procurement risk, ensuring that product selections meet both current mandates and near-term evolution.
- Commodity and cost-structure context, including copper price trajectory implications for winding costs and overall equipment economics, which supports more resilient pricing models and supply-contract negotiations.
Each analytical module is designed to feed directly into capital planning, product strategy, sourcing decisions, and market-entry evaluations. Rather than presenting abstract trends, the study translates market structure into operational indicators that executives can use to pressure-test assumptions, refine pricing strategies, and anticipate competitor moves.
Strategic Recommendations for 2026 Executions
For organizations preparing 2026 operating plans, several strategic priorities emerge from the prevailing market architecture. First, procurement and engineering teams should embed standards and interoperability requirements early in the specification process. Equipment that already aligns with IEEE C57.15, NEMA 4 enclosure expectations, and recognized reliability certifications will face fewer deployment frictions and shorter approval cycles. Second, reverse power flow capability and communication protocol support should be treated as baseline evaluation criteria rather than optional upgrades, given the accelerating integration of distributed generation. Third, commodity exposure must be managed proactively. With copper price forecasts pointing toward elevated levels, procurement contracts should consider index-linked pricing, multi-supplier qualification, and inventory strategies that buffer against volatility without locking in unfavorable fixed terms.
Fourth, competitive positioning requires a nuanced understanding of concentration dynamics. The market’s mid-level concentration means that scale players can leverage installed-base service revenue and global utility relationships, while specialized manufacturers can compete through regional responsiveness, application-specific engineering, and differentiated control architectures. Organizations should map their own capabilities against these competitive modes and determine whether to compete on breadth, specialization, service proximity, or technology integration. Finally, innovation tracking should become a recurring strategic discipline. Recent product introductions, such as transformer-integrated compact regulator concepts, indicate where the industry is moving toward more compact, multifunctional, and automation-ready equipment. Companies that monitor these signals systematically will be better positioned to influence specification language, forge strategic partnerships, or accelerate internal development programs.
Accessing the Complete Intelligence Package
A market moving at a 6.0 percent compound annual growth rate, underpinned by utility modernization, renewable integration, and evolving standards, rewards organizations that base decisions on detailed, forward-looking intelligence rather than aggregated headlines. The macro figures establish the opportunity; the segmentation logic, competitive profiling, standards mapping, and commodity context determine how effectively a company can capture it. The full PW Consulting Worldwide Distribution Power Regulator Market report provides the structured, decision-grade analysis needed to convert market potential into measurable 2026 advantage.
To explore the complete dataset, regional and application-level demand breakdowns, technology-type adoption profiles, and comprehensive competitive assessments, access the full study through the source page. Detailed intelligence of this caliber is designed for teams that need to move from market awareness to execution with precision.
For detailed analysis of this topic, please visit the official page: Worldwide Distribution Power Regulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com