

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Broadband Data Card Market to Hit $2,495M by 2032 at 2.15% CAGR

Navigating the Worldwide Broadband Data Card Market: Strategic Intelligence for 2026 and Beyond
In an era where connectivity defines operational resilience, the broadband data card market stands at a critical inflection point. As enterprises, governments, and consumers demand seamless, high-throughput wireless access, the hardware enabling these connections—USB modems, M.2 data cards, and embedded cellular solutions—has evolved from a commoditized accessory into a strategic infrastructure component. This article introduces PW Consulting's latest market research report, Worldwide Broadband Data Card Market, designed to equip leadership teams with the actionable intelligence required to navigate the 2026–2032 forecast period with confidence.
Market Evolution and Growth Trajectory
The global broadband data card market has demonstrated remarkable stability and gradual expansion over the past half-decade. Historical revenue data from 2020 through 2025 reveals a market that weathered early-pandemic supply chain disruptions and steadily recovered, reaching an estimated baseline valuation of approximately 2.15 billion USD by 2025. This figure reflects not only the recovery of consumer mobile broadband demand but also the accelerating enterprise adoption of cellular backup links and fixed wireless access solutions.
Looking ahead, the forecast period from 2026 to 2032 projects a compound annual growth rate of 2.15 percent. While this growth rate may appear measured, it underscores a market transitioning from explosive early adoption to mature, value-driven expansion. Revenue is expected to climb from roughly 2.16 billion USD in 2026 toward a projected 2.5 billion USD by 2032. This trajectory signals sustained demand for 4G LTE fallback solutions alongside the gradual but decisive shift toward 5G-enabled data cards. For strategic planners, this growth pattern suggests that competitive advantage will no longer stem from volume alone but from differentiation through performance, compatibility, and ecosystem integration.
Worldwide Broadband Data Card Market
The market's maturation is further reflected in its concentration dynamics. The top three players collectively command approximately 45.5 percent of global revenue, while the top five account for 58.2 percent. This moderately consolidated landscape indicates that scale, R&D investment, and strategic partnerships are becoming increasingly decisive. Yet the remaining market share distributed among specialized and regional players highlights ongoing opportunities for agile entrants targeting niche verticals, emerging geographies, or specialized form factors.
Segmentation Dynamics Shaping Strategic Decisions
Understanding how the market fragments across connectivity generations, end-user verticals, and geographic regions is essential for resource allocation and go-to-market planning. The research reveals distinct growth vectors that demand tailored strategies rather than one-size-fits-all approaches.
- Connectivity Transition: The market continues to balance legacy 4G LTE deployments with accelerating 5G integration. While 4G LTE maintains substantial revenue share due to its maturity, cost efficiency, and extensive global coverage, 5G data cards are capturing an increasing portion of enterprise and industrial spending. The coexistence of both generations requires manufacturers and distributors to maintain dual-track product portfolios that address varying price points, performance requirements, and regional infrastructure readiness.
- End-User Diversification: Consumer applications remain a significant revenue driver, fueled by portable hotspots, travel connectivity, and supplemental home broadband. However, enterprise and industrial segments are growing in strategic importance, as organizations deploy cellular data cards for remote monitoring, mobile workstations, vehicle telematics, and backup connectivity. Government and defense procurement adds another layer of complexity, with stringent certification, security, and longevity requirements shaping procurement cycles.
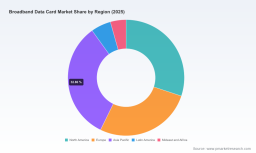
- Geographic Nuances: Regional demand patterns reflect divergent infrastructure development stages, regulatory environments, and pricing sensitivities. Established markets in North America and Europe exhibit steady replacement cycles and incremental upgrades, while Asia Pacific demonstrates dynamic expansion tied to rapid urbanization, industrial digitization, and competitive mobile broadband pricing. Latin America and the Middle East and Africa present distinct growth opportunities, often driven by infrastructure gap bridging and mobile-first connectivity strategies. The report provides granular regional analysis without oversimplifying the local regulatory, logistical, and competitive factors that influence market entry and scaling.
Importantly, this research deliberately avoids presenting oversimplified percentage splits that flatten regional and application complexity. Instead, the full report delivers context-rich segmentation analysis that connects each subsegment to enabling factors such as spectrum availability, device certification timelines, fiber infrastructure complementarity, and enterprise digital transformation budgets.
Competitive Landscape and Key Player Strategies
The competitive arena features a mix of global telecommunications equipment leaders, specialized cellular module manufacturers, and consumer-focused connectivity brands. Each player leverages different strengths—whether vertical integration, module ecosystem breadth, industrial-grade reliability, or consumer brand recognition—to capture share across the data card value chain.
Huawei Technologies continues to maintain a prominent position with its portfolio of mobile WiFi hotspots and 4G/5G broadband data cards, including the E5785 and E5885 series. These products emphasize portable high-speed connectivity via SIM card insertion, with LTE download capabilities reaching up to 300 Mbps. Huawei's scale and global distribution footprint make it a reference point for pricing and feature parity across consumer and light enterprise segments.
Telit Cinterion, following its acquisition of Sierra Wireless, has strengthened its positioning in enterprise and industrial broadband applications. Its FN990A40/A28 and FN990B40 series 5G sub-6 GHz M.2 data cards offer LTE fallback and GNSS support, targeting fixed wireless access, enterprise routers, gateways, and IoT deployments. This product strategy aligns with the broader shift toward embedded, high-reliability connectivity that can operate across volatile network conditions.
Sierra Wireless, now operating under Semtech, continues to develop cellular modules and M.2 5G data cards and routers for mobile broadband and IoT. Its multi-network 5G solutions cater to enterprise and vehicle connectivity, emphasizing interoperability and field-proven durability. This focus resonates with fleet operators, logistics providers, and industrial organizations that prioritize seamless roaming and long lifecycle support.
Inseego Corp. supplies 5G mobile hotspots and MiFi devices that function as broadband data solutions, including the MiFi X Pro series for portable and fixed wireless broadband access. Netgear complements this consumer-enterprise overlap with its Nighthawk M6 series 5G mobile hotspots and data card-compatible devices, leveraging strong brand recognition and retail distribution to capture travel and remote-work connectivity demand.
On the manufacturing and module side, ZTE Corp. produces 4G/5G broadband data cards, mobile hotspots, and CPE for wireless broadband services, while Quectel offers 5G and LTE modules including the RM50x series data cards for M.2 form factor broadband applications in routers and gateways. Fibocom rounds out the competitive field by providing 5G/LTE data cards and modules tailored for industrial and enterprise fixed wireless access, where temperature tolerance, long-term availability, and integration support are critical purchasing criteria.
These competitive dynamics are further shaped by recent industry developments. In March 2026, market analysis updates highlighted major players and technological advancements in 5G connectivity, reinforcing the importance of staying current with product roadmap shifts. Earlier, the World Broadband Association published a next-generation broadband roadmap covering 2023 through 2030, detailing advancements toward BB5.5 and BB6 standards that support higher-capacity wireless broadband—including data card applications. Meanwhile, industry rankings from sources such as PCBX have identified key component suppliers for broadband data solutions, underscoring the interconnected nature of module, card, and device ecosystems.
Regulatory, Infrastructure, and Technology Context
No strategic assessment of the broadband data card market is complete without acknowledging the external forces that shape deployment velocity, cost structures, and product lifecycle planning. Regulatory frameworks continue to influence market behavior in tangible ways. Net neutrality rules and open internet access regulations affect pricing models, service availability, and innovation incentives in mobile broadband, indirectly shaping demand for data card-based access solutions. Simultaneously, data sovereignty and regulatory compliance requirements impact IoT MVNOs and USB modem deployments, particularly for organizations operating across multiple jurisdictions with differing data localization mandates.
Spectrum allocation and device certification processes introduce additional layers of complexity. Delays or divergences in certification can affect time-to-market, create regional fragmentation, and influence obsolescence risk for 4G and 5G data cards. Manufacturers and enterprise buyers alike must factor these regulatory timelines into product roadmaps, procurement cycles, and expansion plans. On the infrastructure side, fiber optic connector markets are forecasted to grow alongside 5G rollouts and high-speed connectivity demands, reflecting the broader reality that wireless and wired broadband are increasingly complementary rather than purely competitive. FTTH share of global consumer broadband connections reached 67 percent in 2022 and is projected to rise to 77 percent by 2030, a trend that does not supplant wireless data card usage but rather defines where cellular solutions add the most value—mobile scenarios, backup links, remote sites, and rapid-deployment environments.
What This Report Delivers for 2026 Decision-Makers
The Worldwide Broadband Data Card Market report is structured to translate complex market intelligence into actionable strategic guidance. Rather than offering generic overviews, the research provides decision-makers with a comprehensive toolkit for planning, investment, and risk mitigation.
- Historical and Forecast Modeling: Detailed revenue trajectories from 2020 through 2032 enable scenario planning, inventory forecasting, and capacity allocation aligned with realistic growth expectations.
- Segment-Level Analysis: Connectivity, end-user, and regional breakdowns are contextualized with qualitative drivers, helping teams prioritize product development, sales focus, and partnership strategies.
- Competitive Profiling: In-depth assessments of key companies—including product portfolios, technological focus, regional presence, and strategic positioning—support benchmarking, competitive response planning, and identification of potential collaboration or acquisition targets.
- Regulatory and Infrastructure Mapping: Analysis of net neutrality, data sovereignty, spectrum allocation, device certification, and fiber infrastructure trends equips strategists with the context needed to anticipate compliance requirements and infrastructure dependencies.
- Industry Development Tracking: Recent events, roadmaps, and sector rankings are integrated to ensure that decision-makers understand both the current landscape and the emergent trends likely to shape the next planning cycle.
The report is designed for executives, product planners, supply chain leaders, investors, and policy-adjacent analysts who require more than headline numbers. It connects quantitative market sizing with qualitative insights about technology transitions, regulatory evolution, and competitive maneuvering. By doing so, it enables organizations to move beyond reactive adaptation and toward proactive positioning.
Why This Intelligence Matters Now
The 2026–2032 window is not merely an extension of past trends; it is a period in which connectivity choices will increasingly determine operational agility, customer experience quality, and cost efficiency. Enterprises evaluating cellular backup for critical infrastructure, manufacturers planning M.2 module integrations, distributors assessing regional expansion, and investors scanning for segment-specific opportunities all face the same fundamental challenge: distinguishing between short-term fluctuations and durable structural shifts.
Wireless Broadband Market
This research was built to address that challenge. It provides a rigorous, data-grounded foundation for strategic planning while recognizing that no single metric can capture the complexity of a market spanning consumer travel connectivity, industrial fixed wireless access, government procurement, and rapidly evolving 5G ecosystem standards. The deliberate focus on context—rather than isolated figures—reflects the reality that successful decisions depend on understanding how segments interact, how regulations reshape incentives, and how competitors adapt their portfolios in response to infrastructure and technology roadmaps.
Organizations that act on incomplete market intelligence risk misallocating resources, underestimating certification and compliance lead times, or overlooking segment-specific growth vectors. Conversely, those that ground their strategies in comprehensive, current analysis are better positioned to time product launches, align supply chains, negotiate partnerships, and allocate marketing investment where returns are most likely to materialize.
Access the Complete Strategic Assessment
The summary presented here offers a high-level view of market direction, competitive dynamics, and the strategic context shaping the worldwide broadband data card landscape. However, the full report contains the detailed segmentation analysis, regional assessments, company profiles, and forecast breakdowns necessary to support precise, confident decision-making. For teams preparing 2026 budgets, product roadmaps, market entry plans, or investment theses, the complete research delivers the granularity and contextual depth required to translate insight into action.
To explore the full dataset, access regional and application-level analysis, and review the comprehensive competitive and regulatory assessments, request the complete Worldwide Broadband Data Card Market report. The detailed intelligence within is designed to support the strategic decisions that will define your organization's connectivity posture throughout the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Broadband Data Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com