

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Augmented Bone Graft Market to Hit $6,295.06M by 2032, Expanding at 6.18% CAGR

Navigating the Augmented Bone Graft Market: Strategic Intelligence for 2026 Decision-Making
The global landscape for bone graft substitutes is undergoing a structural transformation. As surgical techniques evolve and the demand for accelerated osteoconduction grows, stakeholders across the medical device ecosystem require precise, forward-looking intelligence. PW Consulting is proud to introduce our latest comprehensive study: the Worldwide Augmented Bone Graft Market Report. This document is not merely a collection of statistics; it is a strategic roadmap designed to empower executive leadership, product managers, and investors to navigate the complexities of the 2026 fiscal year and beyond.
In an environment defined by regulatory shifts and intense competitive maneuvering, relying on outdated data is a strategic liability. Our analysis covers the historical performance from 2020 through 2025 and projects market trajectories through 2032. The base year for this study is 2025, providing a robust foundation for forecasting the immediate opportunities and challenges that will define the sector in 2026.
Market Trajectory and Growth Dynamics
Understanding the macro-economic velocity of the augmented bone graft sector is the first step in strategic planning. The market has demonstrated consistent resilience and expansion over the past half-decade. Historical data indicates a steady climb in revenue, moving from approximately 3,065.4 million USD in 2020 to a projected 4,137.15 million USD in 2025. This historical performance sets the stage for the forecast period, where the market is expected to accelerate further.
Our forecasting models identify a Compound Annual Growth Rate (CAGR) of 6.18 percent during the forecast period from 2026 to 2032. This growth rate suggests that the sector will expand from its 2026 starting position to reach significant valuation milestones by the early 2030s. For corporate strategists, this trajectory implies a expanding total addressable market (TAM), but it also signals increased competition for market share. The revenue unit for this analysis is Million USD, ensuring precision in financial modeling and ROI calculations.
It is crucial for decision-makers to recognize the inflection points within this timeline. While the general trend is upward, the forecast period includes nuanced fluctuations that our full report dissects in detail. Access to the complete dataset allows clients to align their product launch cycles and capacity planning with these projected peaks and valleys, ensuring resource allocation is optimized for maximum return.
Segmentation and Product Diversity
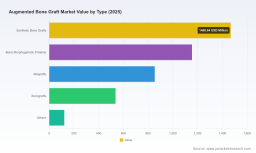
The augmented bone graft market is not monolithic. It is composed of diverse product categories, each driven by distinct clinical needs and material science advancements. Our research breaks down the market into key types, including synthetic bone grafts, bone morphogenetic proteins, allografts, xenografts, and other emerging categories. Each segment presents unique value propositions and risk profiles.
Synthetic options continue to gain traction due to their availability and reduced risk of disease transmission compared to biological alternatives. Meanwhile, bone morphogenetic proteins (BMPs) remain critical for specific high-demand applications despite ongoing safety discussions. Allografts and xenografts occupy vital niches where biological integration is paramount. Understanding the relative revenue contribution and growth potential of each type is essential for companies deciding where to focus their R&D investments.
Furthermore, the application landscape is equally varied. Spinal fusion represents a dominant force in the market, driven by the prevalence of degenerative disc disease and an aging population. Trauma and extremities applications follow closely, addressing acute care needs. Joint reconstruction and dental and craniomaxillofacial procedures also contribute significantly to global demand. Our report provides a granular analysis of how these application vectors interact with product types, revealing cross-segment opportunities that are often overlooked in broader industry reviews.
Geographical Landscape
Regional dynamics play a pivotal role in shaping market strategy. The global market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America traditionally holds a substantial share of the revenue, supported by advanced healthcare infrastructure and high adoption rates of innovative graft technologies. Europe follows as a mature market with strong regulatory frameworks influencing product uptake.
However, the Asia Pacific region presents a compelling growth story for 2026 and beyond. Emerging economies in this region are investing heavily in healthcare modernization, leading to increased procedure volumes. Latin America and the Middle East and Africa, while currently representing smaller portions of the global revenue, offer untapped potential for companies willing to navigate local reimbursement and distribution challenges. Our full report details the specific volume and value distribution across these regions, enabling clients to prioritize geographic expansion efforts based on data-driven potential rather than intuition.
Competitive Landscape and Key Players
The market is characterized by a moderately concentrated environment where strategic positioning is key to survival. Our analysis indicates a Combined Ratio of the top 3 companies at 48.6 percent and the top 5 companies at 65.2 percent. This concentration suggests that while market leaders hold significant power, there is ample room for mid-sized and specialized firms to carve out niches through innovation or specialized service offerings.
Several key companies define the current competitive landscape. Medtronic, headquartered in Dublin, Ireland, maintains a market leadership position with its Infuse Bone Graft utilizing recombinant human BMP-2 for spinal fusion and trauma. Stryker, based in Portage, MI, competes with Vitoss bioactive synthetic bone graft substitutes augmented with calcium sulfate and phosphate. Zimmer Biomet, located in Warsaw, IN, offers Mastergraft synthetic matrices and CopiOS cancellous chips as augmented bone void fillers.
Orthofix Medical, based in Lewisville, TX, specializes in Trinity DBM allografts and Amplify platelet-derived growth factor for foot, ankle, and spine applications. Integra LifeSciences, from Princeton, NJ, markets FormaGraft synthetic putty augmented with collagen. Globus Medical, in Audubon, PA, distributes NanoBone synthetic bone graft substitutes with nanostructured hydroxyapatite. DePuy Synthes (J&J), headquartered in Raynham, MA, offers DBX demineralized bone matrix putty and paste. Xtant Medical provides XCell human allograft bone matrix, while RTI Surgical supplies Tutoplast processed allografts. AlloSource, a non-profit provider in Centennial, CO, offers AlloMatrix DBM injectable, and Cerapedics, based in Westminster, CO, develops i-FACTOR PEEK augmented with P15 peptide for cervical spine interbody fusion.
Recent developments highlight the dynamic nature of this competition. In February 2024, Orthofix Medical announced 2-year ELITE study data showing a 92.3 percent fusion rate for Trinity ELITE DBM in spine surgery. Shortly after, in May 2024, Globus Medical expanded its partnership with Artoss for NanoBone synthetic graft distribution in the US spine market. Regulatory milestones were also achieved, such as Orthofix receiving Korean MFDS approval for FiberFuse synthetic bone graft in October 2023. Furthermore, Medtronic secured a multi-year supply agreement with a major US hospital system for Infuse Bone Graft in March 2024. These events underscore the importance of monitoring clinical data, partnership networks, and regulatory clearances as leading indicators of market shift.
Regulatory and Reimbursement Environment
Operating in the augmented bone graft market requires strict adherence to regulatory standards. Bone graft substitutes are generally classified as Class II devices. Specific classifications include 21 CFR 872.3930 for dental applications and 888.3010 for orthopedic uses, typically requiring 510(k) premarket notification. Compliance with these regulations is non-negotiable and impacts time-to-market strategies significantly.
Worldwide Augmented Bone Graft Market
Reimbursement policies also dictate market accessibility. Medicare reimburses morselized allograft bone grafts under CPT 20937 at an average of 1,200 to 2,500 USD per procedure within spinal fusion DRGs 460-469. Understanding these payment structures is vital for pricing strategies and hospital procurement negotiations. Additionally, sterilization standards for allografts must meet AATB standards, requiring gamma irradiation at 25-35 kGy doses to ensure a sterility assurance level of 10^-6.
Synthetic Bone Graft Market
Material costs and safety warnings also influence the landscape. Beta-tricalcium phosphate granules for synthetic grafts cost between 100 and 300 USD per 10cc unit in bulk procurement, affecting margin structures. Furthermore, safety warnings such as the black box warning for rhBMP-2 products regarding ectopic bone formation and potential malignancy risk in long bone applications must be factored into risk management and marketing communications. These detailed operational constraints are thoroughly examined in our full report to help clients mitigate compliance risks.
Strategic Value for 2026 Decision-Making
Why is this report critical for 2026 planning? The answer lies in the integration of market size, competitive intelligence, and regulatory dynamics. For product developers, the data informs pipeline prioritization. Knowing which segments are maturing versus those with high growth potential allows for smarter R&D allocation. For commercial teams, understanding the geographic distribution of revenue helps in targeting sales efforts and negotiating with distributors. For investors, the competitive concentration metrics and company profiles provide a clear view of the market hierarchy and potential acquisition targets.
The forecast period from 2026 to 2032 offers a long-term view that is essential for capital investment decisions. Whether a company is considering manufacturing capacity expansion, entering new geographic markets, or developing next-generation graft materials, the trajectory outlined in this study serves as a benchmark. The detailed breakdowns of market size by year, coupled with the segmentation analysis, allow for scenario planning under different economic conditions.
Conclusion and Access to Full Intelligence
The Worldwide Augmented Bone Graft Market is poised for continued evolution. With a CAGR of 6.18 percent and a diverse array of players competing on innovation, regulation, and clinical efficacy, the margin for error is slim. PW Consulting's latest market research is designed to eliminate uncertainty. By providing a deep dive into market size, segmentation, competitive profiles, and industry dynamics, we equip our clients with the clarity needed to execute decisive strategies.
However, the insights summarized here represent only the surface of the available intelligence. The complete report contains the specific revenue splits, detailed regional analysis, and comprehensive competitor benchmarking required to build a robust 2026 strategy. To access the full dataset, including the exact market values for each segment, region, and company profile, we invite you to visit the official PW Consulting research page. Secure your copy of the Worldwide Augmented Bone Graft Market Report today and ensure your organization is positioned to lead in the coming years.
For detailed analysis of this topic, please visit the official page: Worldwide Augmented Bone Graft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com