

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Sodium Amide Market to Grow at 4.9% CAGR Through 2032, Reaching $674.61M

Navigating the Sodium Amide Market Landscape: Strategic Intelligence for 2026 and Beyond
The global sodium amide industry stands at a critical inflection point. As chemical manufacturers, pharmaceutical developers, and agrochemical formulators confront shifting supply chains, evolving regulatory frameworks, and intensifying cost pressures, the ability to anticipate market trajectories has become a decisive competitive advantage. This comprehensive worldwide market research delivers the analytical rigor required to navigate this specialized but strategically vital chemical segment. Drawing on historical data from 2020 through 2025 and projecting forward across the 2026-2032 forecast window, our analysis provides enterprise leaders with the decision-grade intelligence necessary to allocate capital, optimize sourcing strategies, and position for sustained growth.
Worldwide Sodium Amide Market
Market Trajectory and Structural Growth Drivers
The sodium amide market has demonstrated resilient expansion over the past half-decade, with total global revenue climbing from approximately USD 385.2 million in 2020 to an estimated USD 482.64 million by 2025. This upward trajectory reflects sustained demand across pharmaceutical synthesis, agrochemical production, dyes and pigments manufacturing, and organic chemical synthesis. Looking ahead, our baseline projections anticipate the global market reaching USD 674.61 million by 2032, governed by a compound annual growth rate of 4.9 percent. This moderate yet consistent growth profile signals a maturing market where incremental gains will be driven less by volume expansion alone and more by value migration, formulation optimization, and regional capacity reallocation.
Several structural forces underpin this forecast. The pharmaceutical sector continues to prioritize synthetic efficiency, with sodium amide serving as a critical reagent in deprotonation and cyclization pathways that support active pharmaceutical ingredient development. Simultaneously, agrochemical producers are recalibrating formulations to meet tightening residue standards, sustaining demand for high-purity sodium amide grades. In the dyes and pigments segment, manufacturers are investing in coloration chemistries that rely on amide-based intermediates, particularly in textile-heavy economies. Organic chemical synthesis applications, meanwhile, are expanding as specialty chemical innovators develop new catalytic and base-mediated reaction sequences. These application-level dynamics, when combined with evolving raw material economics, shape a market environment where pricing sensitivity, purity specifications, and supply reliability are increasingly intertwined.
Competitive Dynamics and Supplier Positioning
The competitive architecture of the sodium amide market is defined by a concentrated yet diversified supplier base. Industry analysis indicates that the top three manufacturers command roughly 42.5 percent of global revenue, while the extended top five accounts for approximately 58.7 percent. This concentration reflects the technical barriers associated with high-purity production, specialized packaging requirements, and the logistics challenges inherent in handling reactive alkali metal derivatives. At the same time, a broader cohort of regional and specialty producers maintains meaningful presence across specific end-use niches and geographic corridors.
Among the established players, Alkali Metals Ltd has operated continuously since 1968 from Hyderabad, India, supplying commercial-grade sodium amide for organic synthesis, dye preparation, and related industrial applications. Shabbir Chemicals has built its export-oriented profile around extra-pure sodamide grades delivered as greyish-white powder, emphasizing reagent-grade consistency and small-packaging flexibility for international buyers. In the reagent and laboratory supply space, Kanto Chemical Co., Inc., headquartered in Tokyo, and LobaChemie Pvt. Ltd., based in Mumbai, provide high-purity offerings tailored to research, development, and specialty synthesis workflows. Natrizen Chemical Pvt Ltd has recently expanded production capacity to align with growing demand from pharmaceutical, dye, and textile segments, demonstrating the strategic importance of capacity readiness in a market where lead times and batch availability increasingly influence procurement decisions.
The global tier includes major integrated chemical enterprises as well. BASF SE supplies sodium amide through its fine chemicals division, supporting pharmaceutical and organic synthesis applications with a focus on supply consistency and technical compatibility. Merck, operating through its Sigma-Aldrich platform in Darmstadt, delivers high-purity reagent-grade sodium amide for scientific research, pharmaceutical development, and advanced organic synthesis. These multi-national suppliers contribute to market stability through established distribution networks and rigorous quality assurance, yet they also operate within a broader ecosystem where regional manufacturers are increasingly competing on cost structure, responsiveness, and localized service capabilities.
Recent Industry Developments Shaping Strategic Posture
Recent operational and investment activities highlight the market's evolving priorities. In December 2023, Natrizen Chemical Pvt Ltd completed a plant expansion that effectively doubled its sodium amide output, responding directly to heightened demand from Indian textile and pharmaceutical sectors. This capacity move illustrates how regional demand surges can accelerate infrastructure investment, particularly in markets where manufacturing clusters are consolidating around specialty chemical production. Earlier, in November 2023, KHBoddin GmbH announced a strategic investment in a renewable energy project intended to power its sodium amide production facility, reducing the operation's carbon footprint. Such sustainability-driven investments are noteworthy because they connect environmental compliance with long-term cost management, an increasingly relevant consideration as energy intensity and regulatory scrutiny rise across chemical manufacturing.
Raw material economics further complicate the procurement landscape. Sodium amide production relies on the reaction of metallic sodium with ammonia gas or liquid ammonia at elevated temperatures, typically between 300 and 350 degrees Celsius. This process configuration means that both ammonia pricing and sodium metal availability exert direct influence on production economics. In March 2026, ammonia prices in Europe reached approximately USD 0.68 per kilogram, reflecting a 7.9 percent increase tied to higher energy costs. By contrast, Northeast Asia ammonia prices stood at roughly USD 0.30 per kilogram during the same period, remaining the most price-competitive regional sourcing corridor. Meanwhile, global sodium metal import prices into the United States averaged around USD 2,470 per ton through late 2025. These divergent input cost environments create meaningful regional variability in production cost structures, influencing where capacity expansion is most economically viable and how procurement teams should evaluate make-versus-buy decisions across geographies.
Formulation, Deployment, and Application Realities
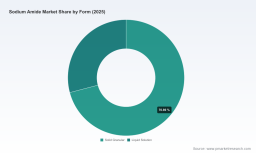
The market's form-based segmentation reflects practical deployment requirements across industrial, laboratory, and synthesis environments. Solid granular sodium amide continues to represent the dominant physical form by revenue share, favored for its storage characteristics, handling stability in controlled environments, and compatibility with bulk industrial processes. Liquid solution formats, while smaller in overall share, serve specialized applications where controlled reactivity, simplified dosing, and laboratory-scale precision are prioritized. Understanding the balance between these forms is essential for procurement planning, as form selection influences packaging specifications, shipping constraints, safety protocols, and end-use performance requirements.
Application-side demand is similarly differentiated. Pharmaceutical synthesis remains the largest end-use category, supported by the continued need for reliable, high-purity basic reagents in multi-step synthetic routes. Agrochemical production constitutes the second major demand pillar, driven by formulation complexity and the ongoing modernization of crop protection chemistries. Dyes and pigments applications contribute a meaningful share, reflecting the material's role in coloration chemistry and intermediate preparation. Organic chemical synthesis applications, while smaller in absolute terms, often exhibit higher specification sensitivity and are closely tied to innovation cycles in specialty chemicals. These application dynamics interact with regional manufacturing footprints, purity expectations, and logistics constraints, creating a market where strategic sourcing requires more than price comparison; it demands a clear understanding of grade suitability, batch consistency, and supply continuity risk.
What the Full Report Delivers for Enterprise Decision-Makers
This market research is designed to translate macro-level industry intelligence into actionable strategic guidance. The full report moves well beyond headline figures to provide the operational detail required for planning, procurement, and competitive positioning. Decision-makers will find structured analysis covering historical performance, baseline and scenario-based forecasts, segmentation by region and form, application-level demand assessment, and a detailed competitive landscape mapping that profiles the strategic posture of key manufacturers. The study also integrates raw material cost insights, production technology context, and recent corporate developments that signal where supplier capacity, sustainability investment, and regional pricing dynamics are heading.
To support practical implementation, the report includes information on pricing trends, procurement considerations, supply chain risk factors, and the strategic implications of market concentration. Readers will also find guidance on how regulatory shifts, energy cost variability, and regional ammonia pricing disparities may affect production economics and sourcing strategy. By linking forecast data to operational realities, the study equips executives, procurement leaders, and strategy teams with a framework for evaluating capacity investment, vendor selection, and market entry or expansion opportunities across the 2026-2032 horizon.
Strategic Implications for 2026 and the Forward Outlook
For organizations operating in or adjacent to the sodium amide market, the 2026 planning cycle will be shaped by three interconnected themes: supply reliability, input cost volatility, and differentiation through purity and service. The forecast growth rate suggests that the market will not experience dramatic volume shocks, but rather a steady evolution in which competitive advantage accrues to firms that manage cost structures efficiently, maintain consistent quality, and anticipate demand shifts across pharmaceutical, agrochemical, dyes, and organic synthesis applications. Regional disparities in ammonia pricing and sodium metal import costs will continue to influence where production is most economical and how procurement teams should structure multi-source strategies.
Market concentration also has strategic implications. In a market where a relatively small group of suppliers accounts for a substantial share of revenue, procurement resilience becomes as important as price optimization. Companies that build diversified supplier portfolios, validate alternative grades and forms, and monitor capacity expansion announcements will be better positioned to navigate potential bottlenecks. At the same time, sustainability-oriented investments and energy cost management are increasingly relevant, particularly for producers exposed to higher energy-price environments. Organizations that incorporate these factors into sourcing and planning decisions will gain both cost discipline and reputational alignment with evolving regulatory and customer expectations.
Sodium Cyanide Market
Conclusion: Turning Market Intelligence into Competitive Advantage
The worldwide sodium amide market is entering a phase where strategic clarity matters more than ever. With historical performance demonstrating steady growth, a forecast trajectory indicating incremental expansion through 2032, and a competitive landscape shaped by both concentrated global players and agile regional manufacturers, the market rewards organizations that approach it with disciplined analysis and forward-looking planning. This research study provides the depth, structure, and contextual insight necessary to support those decisions. To access the complete dataset, detailed segmentation analysis, competitive profiles, and forward-looking scenario assessments, request the full report and equip your team with the intelligence required to make confident, evidence-based decisions throughout the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Sodium Amide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com