

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Localized Temperature Therapy Market Hits $2.3B in 2025, Projects 5.85% CAGR to 2032

Strategic Outlook: Navigating the Worldwide Localized Temperature Therapy Product Market in 2026
The localized temperature therapy product market stands at a critical inflection point as the global healthcare landscape shifts toward value-based care, home-based treatment modalities, and precision rehabilitation protocols. Organizations operating across medical device manufacturing, clinical procurement, reimbursement strategy, and technology integration must now confront a sector defined by accelerating commercialization, evolving regulatory expectations, and increasingly differentiated therapeutic value propositions. This market intelligence framework is designed to translate high-level trajectory signals into executable strategic posture for 2026 and beyond.
Over the past half-decade, the sector has demonstrated sustained expansion, transitioning from an estimated 1.77 billion USD in 2020 to approximately 2.35 billion USD in 2025. The momentum carries forward into the forecast horizon, with valuation projections scaling toward 3.5 billion USD by 2032. This progression translates to a compound annual growth rate of 5.85 percent, a trajectory that reflects not merely incremental adoption but structural realignment in how localized thermal interventions are positioned across clinical workflows, sports rehabilitation ecosystems, and post-acute care pathways.
Enterprise decision-makers evaluating exposure to this space must recognize that aggregate growth metrics only tell a fraction of the story. The real strategic advantage lies in parsing the composition of demand, understanding where competitive intensity is compressing margins, which application verticals are experiencing adoption inflection, and how regional regulatory architectures are reshaping market entry timelines. Our latest market research synthesis addresses these dimensions directly, providing a structured lens through which procurement leaders, product strategists, and investor committees can calibrate resource allocation with greater precision.
Structural Composition and Demand Architecture
The market is fundamentally organized around three intersecting dimensions: therapeutic temperature modality, application-driven clinical need, and geographic delivery infrastructure. Each layer carries distinct purchasing behavior, reimbursement pathways, and competitive barriers.
Worldwide Localized Temperature Therapy Product Market
By therapeutic modality, bifurcated temperature interventions coexist alongside integrated centralized thermal platforms. Heat therapy products represent a substantial share of commercial activity, anchored in muscle recovery, chronic pain modulation, and prehabilitation routines. Cold therapy products constitute a parallel and highly engineered segment, emphasizing localized post-operative cooling, inflammatory control, and acute injury management. Localized thermal therapy systems occupy a more specialized tier, combining precision temperature regulation with circulation or compression mechanics, typically targeting vascular, orthopedic, and complex surgical recovery environments.
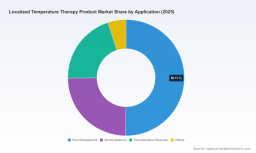
From an application lens, pain management emerges as the dominant commercial anchor, reflecting the broad prevalence of musculoskeletal disorders, aging-driven degenerative conditions, and the clinical pivot toward non-pharmacological analgesics. Sports medicine represents a high-engagement secondary layer, driven by professional and amateur athletic recovery protocols, wearable integration trends, and performance optimization demand. Post-operative recovery forms a third critical pillar, wherein localized temperature control is increasingly embedded into standardized discharge and rehabilitation pathways. Additional application categories continue to expand around specialized clinical protocols and emerging therapeutic indications, contributing incremental but strategically relevant demand.
Regional distribution reveals a mature Western anchor combined with expanding peripheral markets. North America currently commands the largest revenue concentration, supported by established reimbursement structures, strong surgical volume, and deep clinical procurement networks. Europe follows with a substantial footprint shaped by centralized healthcare procurement, strong regulatory oversight, and growing emphasis on standardized rehabilitation devices. Asia Pacific contributes a meaningful and increasingly dynamic segment, reflecting expanding private healthcare infrastructure, rising sports participation, and growing adoption of localized therapeutic devices in both clinical and consumer-adjacent settings. Latin America and the Middle East and Africa represent smaller but strategically important territories, where import pathways, reimbursement evolution, and healthcare modernization are gradually reshaping accessibility.
Competitive intensity is concentrated but not dominated. The top three players collectively account for approximately 31.45 percent of market revenue, while the top five extend this to roughly 48.2 percent. This structure indicates a market where scale, brand trust, regulatory compliance, and distribution depth matter significantly, yet where meaningful whitespace remains for specialized engineering, niche clinical indications, and differentiated reimbursement positioning.
Regulatory, Reimbursement, and Operational Dynamics Shaping 2026
Market expansion does not occur in a vacuum. The operational environment for localized temperature therapy products is shaped by a layered framework of regulatory classification, quality management expectations, electrical safety compliance, and reimbursement mechanics. These elements collectively influence product design cycles, time-to-market decisions, and commercial scalability.
Worldwide Temperature-Controlled RF Ablation Technology Market
In the United States, powered localized cryotherapy and compression devices are classified as Class II under 21 CFR 878.5980, requiring 510(k) premarket notification. For manufacturers and entrants, this classification pattern establishes a predictable but non-trivial regulatory pathway, emphasizing demonstrating substantial equivalence while accounting for evolving software, user interface, and sensor integration features. The requirement for compliance with ISO 13485:2016 reinforces the importance of disciplined quality management systems across design, production, and post-market activities. Simultaneously, electrical safety expectations for medical electrical equipment intersect with IEC 60601-1 standards, further elevating the engineering and certification burden for devices that combine thermal elements with active power, circulation, or compression functions.
On the reimbursement side, thermal modality application carries reimbursement visibility through CPT code 97010, with a national average Medicare reimbursement level around 12.06 USD. While this direct reimbursement line may appear modest in absolute terms, it functions as an important access signal for clinical adoption, particularly in outpatient, physical therapy, and post-acute contexts. More importantly, reimbursement architecture indirectly shapes purchasing behavior by influencing whether localized temperature devices are positioned as cost-effective adjuncts within a broader care episode rather than standalone revenue-generating instrumentation.
In Europe, market access is further conditioned by conformity requirements under Regulation (EU) 2017/745, with temperature therapy devices placed on the EU market expected to bear CE marking in alignment with the MDR framework. This elevates the importance of clinical documentation, risk management, and post-market surveillance planning, particularly for manufacturers operating across multiple jurisdictions with overlapping but non-identical conformity expectations.
Together, these dynamics mean that 2026 strategy must be built upon integrated assumptions rather than product-market assumptions alone. Companies that treat regulatory, reimbursement, and quality compliance as afterthoughts will face delays, margin erosion, or restricted clinical uptake. Conversely, organizations that embed these parameters into upstream product strategy, clinical evidence generation, and distribution planning can convert compliance complexity into competitive insulation.
Competitive Landscape and Strategic Positioning Signals
The competitive field includes companies that have established presence through distinct device architectures, clinical positioning, and end-user relationships. Understanding their strategic footprint helps clarify where the market is consolidating and where differentiation remains achievable.
Breg, Inc., based in Carlsbad, California, has built recognition around cold therapy platforms such as Polar Care Cube and Wave systems, with disposable pad configurations designed for localized post-operative cooling and pain management. Its product logic reflects strong emphasis on post-surgical workflows, ease of use, and consumable-driven revenue models. Enovis, operating through its DJO Global heritage in Lewisville, Texas, positions around integrated active compression and cold therapy systems such as the Game Ready GRPro 2.1, targeting acute injury and surgical recovery through combined modalities. This integrated approach underscores a broader industry tendency to bundle temperature control with mechanical support functions to increase clinical utility and differentiation.
Össur hf., headquartered in Reykjavik, Iceland, brings a compact cold therapy unit portfolio, including Cold Rush 1.0 with insulated cooler design, focused on targeted localized cooling therapy. Its presence demonstrates how portability, field usability, and targeted application design can support multi-market distribution. DeRoyal Industries, Inc., based in Powell, Tennessee, supplies CT2000 Cold Therapy Units paired with sterile wraps for localized temperature control in clinical settings, reinforcing the importance of infection-control adjacency and hospital-grade procurement compatibility. ThermoTeK, Inc., located in Flower Mound, Texas, develops CL-100 and CL-300 circulatory and therapy systems with precise temperature regulation for vascular and orthopedic localized therapy, highlighting the opportunity in highly controlled therapeutic delivery for more complex recovery scenarios.
The strategic implications of this competitive set are multifaceted. First, device functionality differentiation is increasingly tied to precision, modality combination, and clinical workflow fit rather than standalone temperature delivery alone. Second, consumable design, sterile compatibility, and post-operative usability remain important commercial levers, particularly in higher-volume surgical and rehabilitation settings. Third, distribution and clinical evidence generation are likely to separate mature incumbents from newer entrants, especially where reimbursement validation and protocol integration influence procurement decisions. Fourth, competitive dynamics will continue to reward organizations that can align engineering precision with cost-effective manufacturing, reliable supply chains, and credible clinical narratives.
What This Market Intelligence Delivers for Strategic Decision-Makers
This research publication is designed to move beyond surface-level sizing and into the operational detail that underpins corporate strategy. The analysis integrates historical evolution from 2020 through 2025 with a forecast view extending from 2026 to 2032, enabling organizations to evaluate not just where the market is heading, but how the composition of growth changes over time.
The report examines segmentation architecture across region, therapeutic type, and application, allowing readers to identify which demand clusters are expanding most rapidly, which are maturing, and where incremental value creation is most feasible. It provides an assessment of competitive positioning by mapping company profiles, product architectures, and strategic focus areas, helping readers understand the structural pressures shaping pricing, differentiation, and channel strategy.
Operational and regulatory context is embedded throughout, not treated as a peripheral appendix. The discussion of classification pathways, quality system expectations, safety standards, and reimbursement visibility is intended to support more realistic planning for product development timelines, market entry sequencing, and cost structure assumptions. For procurement and clinical operations teams, the material supports more informed evaluation of device fit within existing care pathways, consumable economics, and compliance burden. For product and innovation leadership, it offers a structured basis for determining where precision engineering, modality integration, or application-specific evidence generation may yield the strongest returns.
The research also includes scenario framing to help decision-makers interpret the range of plausible outcomes rather than relying on a single deterministic line. Given the interplay between surgical volume trends, sports rehabilitation adoption, reimbursement policy evolution, and regional healthcare modernization, a range-based view is essential for robust strategy formulation. The forecast architecture is constructed to support sensitivity exploration around adoption velocity, regulatory timing, and competitive response, especially where market participants may pursue consolidation, determine niche focus, or accelerate multi-region expansion.
Recommended Use of This Intelligence in 2026 Planning
Organizations engaging with this market should treat localized temperature therapy products as a portfolio decision rather than a single-product bet. The strategic point is not only whether to participate, but where to allocate attention across product architecture, indication focus, geographic entry, and commercial model design.
For medical device manufacturers, the immediate priority is to align product roadmaps with clinical workflow integration and compliance readiness. Devices that can demonstrate reliable temperature precision, workflow compatibility, consumable economics, and credible post-market support are better positioned to compete in an environment where procurement teams weigh both clinical trust and operational burden.
For distributors, clinical partners, and procurement leaders, the analysis should inform category strategy, supplier evaluation, and inventory planning. Understanding which application verticals show stronger demand resilience, which regions carry faster or slower adoption dynamics, and how reimbursement and regulatory expectations shape purchasing decisions will improve negotiation positioning and product mix planning.
For investors and corporate development teams, the market structure suggests value in assessing differentiation potential against a moderately concentrated field. With top-five concentration at roughly 48.2 percent, the sector is not fully saturated, but competitive advantage increasingly depends on specialized engineering, application fit, evidence generation, and distribution reach rather than scale alone. Entry and expansion decisions should therefore consider where a participant can build defensible positioning rather than competing solely on price or generic functionality.
Accessing the Full Market Intelligence Package
Aggregate growth patterns and high-level segmentation outlines provide essential orientation, but they do not replace the calibrated commercial insight required for 2026 planning. The detailed regional-demand architecture, application-level revenue structure, type-based commercial dynamics, and competitive profiling contained in the full report are designed to support specific allocation decisions, entry sequencing, and risk assessment. Those compressed summary signals cannot fully capture the nuance needed for precise product, pricing, or geographic strategy.
The complete Worldwide Localized Temperature Therapy Product Market research publication provides the deeper quantification, structural breakdowns, and competitive mapping required to translate market trajectory into operational action. Readers seeking to benchmark internal assumptions, evaluate market-entry timing, or build investment and procurement cases are encouraged to access the full analysis through the source page, where the complete dataset, segmentation detail, and strategic interpretation are available for review.
In a sector defined by steady growth, evolving compliance requirements, and increasing clinical integration, strategy quality will be determined by how precisely organizations understand the composition of demand and the distribution of competitive advantage. This intelligence framework is built to support that precision, giving decision-makers a clearer path from market signal to execution.
For detailed analysis of this topic, please visit the official page: Worldwide Localized Temperature Therapy Product Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com