

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Microscopy Targets Market Hits $285.75M in 2025, Poised to Reach $454.52M by 2032 with 6.85% CAGR

Navigating Precision: Strategic Intelligence for the Microscopy Targets Market Through 2032
Executive Overview: Navigating the Precision Imperative
The microscopy targets market stands at a critical inflection point where foundational metrology meets accelerating technological adoption. As laboratory workflows, semiconductor inspection protocols, and advanced materials characterization converge, the demand for standardized, highly accurate calibration and resolution verification tools has evolved from a routine operational necessity to a strategic competitive differentiator. Our latest market research delivers a structured, forward-looking intelligence framework designed specifically to support enterprise decision-making during the 2026–2032 forecast window. This publication is engineered to clarify trajectory, quantify structural shifts, and equip leadership teams with the analytical rigor required to allocate capital, prioritize product development, and navigate an increasingly consolidated supplier landscape.
Market momentum is already evident in the historical record. From a baseline of approximately 182.45 million USD in 2020, the sector advanced through a series of compounding growth phases, reaching 285.75 million USD by 2025. The trajectory suggests sustained expansion rather than cyclical fluctuation, with the broader market projected to scale toward 454.52 million USD by 2032. Underlying this progression is a forecasted compound annual growth rate of 6.85 percent across the 2026–2032 evaluation period. These figures are not merely retrospective summaries; they are the structural scaffolding for scenario planning, capacity forecasting, and long-term investment alignment. Understanding how this growth distributes across technological categories, end-use domains, and geographic corridors requires a granular analytical lens—one that this report systematically provides while deliberately reserving proprietary segmentation intelligence for full-access consultation.
Structural Validation: Historical Trajectory and Forecast Architecture
The 2020–2025 analytical window captures a market that has absorbed multiple overlapping catalysts: heightened emphasis on quantitative imaging reproducibility, tighter metrology traceability requirements, and the gradual migration of advanced microscopy into high-throughput industrial and semiconductor workflows. The historical progression reflects both steady baseline demand and episodic acceleration tied to equipment refresh cycles and regulatory calibration expectations. Looking forward, the forecast architecture does not assume linear continuation. Instead, it layers sensitivity variables including instrumentation adoption curves, custom substrate engineering timelines, and regional capacity expansion patterns.
Strategic planners frequently encounter a common challenge in this sector: macroeconomic headline figures obscure the underlying distribution mechanics that actually drive procurement decisions. Revenue concentration patterns indicate that a relatively small group of manufacturers commands a substantial share of global supply, with the top three firms collectively representing approximately 48.5 percent of market revenue and the top five reaching roughly 62.3 percent. This concentration has meaningful implications for supplier diversification, pricing leverage, and technology access. The research framework deconstructs these dynamics without reducing them to oversimplified rankings, instead mapping how scale, fabrication capabilities, and certification infrastructure interact to shape competitive positioning. By embedding the 2026–2032 forecast within a structured scenario envelope, the report enables organizations to test internal assumptions against market-validated boundaries rather than extrapolating from isolated pilot data.
Commercial Architecture: Technology Categories, Application Domains, and Regional Corridors
Effective market positioning requires more than total revenue visibility. It demands clarity on how the product landscape fractures across functional use cases, how procurement priorities differ by domain, and where geographic demand clusters intersect with supply-side capabilities. The commercial architecture of this market can be understood through three interlocking dimensions: technology classification, application orientation, and regional deployment patterns. Each dimension carries distinct procurement economics, validation requirements, and innovation pacing.
Worldwide Coating Target Materials Market
At the technology layer, demand is anchored by several core product families that serve complementary but non-interchangeable functions. Stage micrometers remain foundational for routine dimensional verification and workflow calibration, while calibration reticles support higher-precision optical alignment and system benchmarking. Resolution targets occupy a more specialized tier, catering to performance validation for advanced imaging modalities where pattern fidelity and structural resolution are paramount. The interplay among these categories is not merely additive; it reflects evolving laboratory standardization practices and the gradual integration of custom micro- and nano-patterned substrates into quantitative imaging pipelines.
On the application side, procurement behavior diverges sharply by industry lifecycle, regulatory environment, and instrumentation density. Life sciences research continues to drive consistent baseline demand, particularly where reproducibility and quantitative phase measurement are becoming standard expectations. Materials science applications impose different performance criteria, emphasizing structural characterization and calibration reliability across varied sample morphologies. Semiconductor inspection introduces tighter tolerance thresholds and higher throughput expectations, reinforcing the need for targets that can withstand repeated verification cycles without degradation. Industrial quality control rounds out the application spectrum with use cases centered on repeatability, cost efficiency, and integration with existing inspection infrastructure. The report maps these application streams to procurement drivers and technology adoption pathways, providing decision-makers with a functional view of where demand is structurally anchored versus where it remains opportunistic.
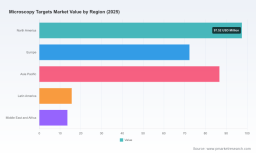
Regional distribution further shapes competitive strategy. Demand concentration intersects with local metrology ecosystems, instrument manufacturing footprints, and certification accessibility. North American, European, and Asia-Pacific corridors each present distinct procurement rhythms and supplier engagement models, while Latin American and Middle East/Africa markets reflect more targeted, application-specific adoption patterns. The analysis preserves this geographic nuance while avoiding reductive regional breakdowns, instead emphasizing how regional demand interacts with supply-chain resilience, import dependencies, and localized calibration standards. For organizations evaluating expansion, partnership, or sourcing realignment, this layered perspective provides a practical starting point for market-entry prioritization without exposing the full segmentation matrix that forms the core of the paid intelligence package.
Competitive Dynamics and the Consolidation Imperative
The supplier landscape is defined by a blend of specialized instrumentation experts, precision fabrication specialists, and broad-distribution optics providers. Competitive advantage in this sector does not emerge from volume alone; it is increasingly determined by fabrication precision, certification readiness, and the ability to deliver customized calibration substrates at scale. Several recurring capability themes differentiate the players that are actively shaping market direction.
Leading suppliers are distinguished by their micro- and nano-patterning infrastructure. Companies leveraging electron-beam lithography and high-resolution patterning processes are positioning themselves at the upper end of the resolution envelope, with structural feature sizes reaching into the nanometer range. This capability directly supports advanced microscopy applications where conventional calibration tools no longer satisfy validation requirements. At the same time, broader-tier suppliers maintain market relevance through standardized test charts, chrome-on-glass patterning, and widely adopted resolution references that serve high-volume laboratory and industrial users. The coexistence of these approaches creates a market with multiple entry points but also rising expectations for calibration traceability and pattern reproducibility.
Beyond fabrication, certification and traceability have become central competitive signals. Stage micrometers and calibration standards increasingly require documentation aligned with recognized metrology frameworks, with traceability pathways connected to national calibration institutions and compliant quality systems. Suppliers that can demonstrate consistent certification processes, audit-ready documentation, and alignment with ISO expectations gain measurable advantage in regulated procurement environments. This dynamic is especially pronounced in applications where measurement integrity directly affects downstream analysis, including life sciences imaging and industrial quality control.
Competitive positioning is further shaped by recent ecosystem developments. In March 2026, ZEISS introduced a new VR-based microscopy training program developed in partnership with universities, focused on system components and workflow integration. While operating in a related instrumentation space, this initiative reflects a broader industry movement toward structured knowledge transfer, standardization of operational practices, and deeper alignment between equipment vendors, end users, and academic training pipelines. Training and workflow enablement are increasingly viewed as complements to hardware performance, reinforcing the importance of suppliers that can offer not only calibration targets but also the procedural context needed to deploy them effectively.
Against this backdrop, the market exhibits a clear consolidation dynamic. Scale players continue to consolidate supply advantages through broad product portfolios, established distribution channels, and recognized certification credentials. Specialized manufacturers, meanwhile, compete through custom engineering, advanced patterning, and domain-specific target design. The strategic question for buyers and investors alike is not simply who holds the largest share, but how the competitive architecture will evolve as fabrication precision becomes more accessible, certification expectations tighten, and end users demand tighter integration between calibration, training, and imaging workflows. The report provides a structured competitive mapping that highlights operational strengths, capability boundaries, and likely pressure points without flattening the landscape into a simple leaderboard.
Regulatory Anchors and Calibration Ecosystems
The credibility of microscopy targets is inseparable from the regulatory and standards environment that surrounds them. As quantitative imaging and high-resolution characterization become embedded in more critical workflows, calibration verification has shifted from optional best practice to operational expectation. Certified stage micrometers and calibration reticles are increasingly supplied with documentation that supports traceability claims and alignment with recognized quality frameworks. This is not a peripheral compliance issue; it is a core component of procurement justification in environments where measurement integrity directly affects research reproducibility, process validation, or inspection reliability.
Traceability expectations are particularly pronounced where calibration standards must be demonstrably connected to national metrology institutions. Certification pathways that support documented traceability reinforce confidence in measurement accuracy and reduce ambiguity in cross-site or cross-instrument comparison. In practice, this means the market is rewarding suppliers that can integrate fabrication precision with validation rigor, rather than treating certification as an afterthought. The research evaluates how these standards realities influence supplier selection, procurement cycle timing, and the commercial value of certification-ready product lines. This section is especially relevant for procurement teams seeking to align purchasing decisions with institutional quality requirements while avoiding hidden validation risks.
Strategic Utility for 2026 Decision-Making
This research is structured to translate market complexity into actionable strategic clarity. For executive teams, the report functions as a decision-support instrument across several core planning dimensions: revenue forecasting, product portfolio alignment, supplier diversification, and technology investment sequencing. Rather than presenting static snapshots, the analysis is designed to help organizations test assumptions, bound uncertainty, and identify where strategic intervention will yield the highest return.
In practice, the report supports 2026 decision-making through several concrete applications. First, it provides a market-validated growth context that can anchor internal projections and investment scenarios, allowing leadership to benchmark plans against an evidence-based trajectory rather than internal extrapolation alone. Second, it maps the structural relationships among product categories, application domains, and regional demand patterns, enabling more precise segmentation of addressable opportunity. Third, it examines the competitive field through capability-based lenses, helping organizations identify where supplier concentration creates vulnerability, where specialized partnerships can accelerate product validation, and where certification alignment is becoming a gatekeeping requirement. Fourth, it integrates regulatory and traceability dynamics into commercial analysis, clarifying why certain product lines command premium positioning and how compliance expectations shape procurement behavior.
The publication is deliberately constructed to balance depth with discipline. It delivers enough analytical rigor to establish credibility and demonstrate methodological precision, while preserving the core segmentation data, detailed company-level assessments, and granular forecast breakdowns for the full licensed research package. This approach ensures that readers gain a clear understanding of market architecture and strategic implications, while recognizing that precise percentage splits, regional revenue allocations, and application-specific volume estimates are reserved for the complete intelligence release. The intent is not to withhold insight, but to structure it in a way that supports executive evaluation while maintaining the commercial integrity of the proprietary dataset.
Scope of Operational Intelligence and Access Path
The full research package extends well beyond the structural overview presented here. It delivers operational-ready content designed for cross-functional use across strategy, product management, procurement, and market development teams. Core components include a detailed segmentation architecture that disaggregates market value across technology types, application verticals, and regional corridors, supported by historical baselines and forward projections through 2032. The report also incorporates supplier profiling, capability mapping, and technology differentiation analysis that connects fabrication methods, certification readiness, and product families to real-world commercial positioning.
Additional operational content covers procurement dynamics, validation expectations, and the practical implications of certification traceability for sourcing decisions. Scenario frameworks are included to help organizations evaluate demand sensitivity under differing adoption assumptions, equipment refresh cycles, and regulatory evolution paths. For teams evaluating entry, expansion, or partnership opportunities, the research provides the structural context necessary to prioritize where precision, scale, and certification alignment will matter most.
Microscopy Targets Market
Strategic readers seeking the complete segmentation matrix, district-level market allocations, application-specific revenue detail, and proprietary competitive benchmarking will find the full licensed version engineered for direct integration into planning workflows. The published excerpt establishes the analytical foundation and strategic relevance; the complete report converts that foundation into a deployable intelligence asset.
Conclusion
The microscopy targets market is expanding within a framework defined by rising precision expectations, increasingly formalized calibration standards, and a supplier landscape where scale and specialization are both influencing commercial outcomes. With historical growth establishing a durable trajectory and the 2026–2032 forecast signaling continued expansion toward a materially larger addressable base, the strategic window for aligned decision-making is open now. Organizations that understand the interplay between product categories, application demand, certification requirements, and competitive concentration will be better positioned to allocate resources, manage supplier risk, and capture value as the market matures. This research provides the structured intelligence necessary to make those decisions with confidence, while preserving the detailed segmentation intelligence for teams ready to convert insight into execution.
For detailed analysis of this topic, please visit the official page: Microscopy Targets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com