

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Paper Cup Sleeve Market to Hit $916.19M by 2032, 5.19% CAGR (2025-2032)

Strategic Intelligence for 2026: Navigating the Worldwide Paper Cup Sleeve Market
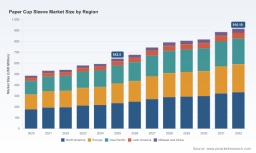
The global paper cup sleeve market stands at a critical inflection point as 2026 begins. Between 2020 and 2025, the total addressable market expanded from approximately USD 485.2 million to a reaffirmed USD 642.5 million, reflecting a compound growth trajectory that underscores durable end-market demand, shifting consumer packaging expectations, and tightening operational efficiency requirements across foodservice supply chains. Looking ahead to the 2026 to 2032 forecast horizon, the market is projected to reach USD 916.19 million, guided by a five-year CAGR of 5.19 percent. These are not abstract statistics. They represent a decision architecture for procurement leaders, sustainability officers, product developers, and competitive strategists who must allocate capital, design supply resilience, and position portfolios against evolving regulation, material economics, and channel fragmentation. This article outlines the strategic logic embedded in our latest Worldwide Paper Cup Sleeve Market study and explains why the full report is essential reading for companies planning through the remainder of the decade.
At its core, this market is no longer a commodity wrap-around. It is a functional interface between thermal performance, brand expression, material compliance, and consumer experience. Sleeve specifications now influence beverage handling safety, perceived quality, cup compatibility, and downstream recyclability narratives. As chains scale operations and independent cafes defend differentiation, packaging decisions that once lived in the background now sit directly in the path of cost management, ESG reporting, and customer retention. Decision-makers therefore need more than directional market color. They need a structured map of how demand is forming, where margins concentrate, which capabilities command pricing power, and how regulatory momentum will reshape sourcing and design choices in each major geography.
Macro Trajectory and Decision Relevance
The trajectory from 2020 through 2025 shows a market that has repeatedly absorbed macroeconomic variance and still advanced. After a 2020 baseline of USD 485.2 million, the market moved to USD 531.1 million in 2021, USD 538.75 million in 2022, USD 579.77 million in 2023, USD 593.08 million in 2024, and USD 642.5 million in 2025. That progression indicates sustained absorption of sleeve volume across both high-frequency beverage channels and broader institutional deployment, even as inflation, freight volatility, and input-cost swings challenged margin discipline. The forecast path reinforces the same structural signal: from USD 677.12 million in 2026 to USD 743.97 million in 2027, USD 790.85 million in 2028, USD 805.91 million in 2029, USD 817.98 million in 2030, USD 885.76 million in 2031, and USD 916.19 million in 2032. The consistency of this expansion curve is strategically important because it tells executives that volume growth is not a one-time reopening artifact or a temporary consumer fad. It reflects a more persistent alignment of hot-beverage consumption patterns, on-the-go service models, and packaging decisions that prioritize insulation, handling comfort, and branding real estate.
Worldwide Paper Cup Sleeve Market
For 2026 planning, this trajectory matters in three practical ways. First, it sets a realistic envelope for capacity investment and working-capital planning, helping leaders avoid overbuilding or undercommitting against a market that is expanding, but not exploding. Second, it establishes a reference frame for performance benchmarking, enabling companies to ask whether their own growth rate, margin profile, and share movement are consistent with the broader market’s direction or whether they are gaining or losing relative ground. Third, it frames the timescale over which product strategy, supplier consolidation, and compliance readiness will mature. A 5.19 percent CAGR may appear moderate in isolation, yet it compounds into meaningful share shifts over multi-year horizons, particularly when paired with regulatory deadlines, material-price cycles, and retailer-driven specification changes. Companies that treat the forecast as an operational baseline rather than a marketing statistic will be better positioned to time product launches, renegotiate supply terms, and prepare for evolving customer requirements.
From Aggregate Growth to Operational Insight: What the Report Delivers
Aggregate figures provide direction, but durable strategy is built on segment logic, competitive posture, and the operational levers that convert demand into margin. Our study is structured to translate market movement into decision-grade intelligence across the dimensions that actually shape commercial outcomes. The report examines material architecture and design trade-offs, including the thermal, structural, and printability implications of corrugated paperboard, kraft paper, and smooth or embossed paper formats. These choices influence insulation performance, stacking behavior, machine runnability, label compatibility, and consumer tactile perception, and they also interact with recycling and composting narratives in ways that increasingly affect customer acceptance and compliance exposure. The analysis addresses application deployment across Coffee Shops and Cafes, Quick Service Restaurants, and Commercial and Institutional channels, with attention to volume concentration, specification sensitivity, purchasing cycles, and the differing ways each channel balances cost pressure against branding and functional performance. Regional deployment is mapped in a manner that helps executives understand where demand intensity, supply localization, and regulatory exposure converge, without reducing regional complexity to static percentage snapshots that obscure change dynamics.
Beyond segmentation, the report provides practical frameworks for sourcing strategy, cost volatility management, and channel-specific value proposition design. It assesses how manufacturers and converters are aligning product portfolios with sustainable fiber-based materials, recycled-content options, and certification positioning, while also evaluating where customization, print capability, and thermal engineering become sources of differentiation rather than table stakes. The study further incorporates recent market activity that signals where investment and partnership momentum is forming, including product launches that extend compostable and plant-based solutions, collaborative arrangements linking insulated packaging with enhanced thermal performance and recyclability, and closed-loop recycling initiatives tied to municipal and circular-economy objectives. These developments are not treated as isolated press items. They are read as indicators of how competitors are constructing future relevance and where buyers should expect specification pressure, volume reallocation, and compliance-linked purchasing criteria to intensify.
Competitive Posture and Strategic Positioning
The competitive landscape is shaped by a diverse set of participants, each approaching the sleeve market through a different combination of regional reach, product technology, sustainability positioning, and customer intimacy. Huhtamaki Oyj operates from Espoo, Finland, with insulated paper cup sleeves integrated into a global foodservice packaging portfolio that emphasizes recycled content and hot-beverage insulation. Dart Container Corporation, based in Mason, Michigan, focuses on paper and insulated sleeves for hot beverages in foodservice and quick-service contexts, building on thermal protection solutions tailored to high-throughput beverage service. Graphic Packaging International, headquartered in Atlanta, Georgia, manufactures paper-based packaging solutions that include cup sleeves, with a strong emphasis on sustainable fiber-based materials and conversion capability. Pactiv Evergreen Inc., located in Lake Forest, Illinois, supplies paper cup sleeves and related foodservice disposables, including products with sustainability attributes designed for hot drink applications. Benders Limited, based in Wellingborough, UK, produces paper cups and complementary sleeves using sustainably sourced materials and FSC certifications, giving it a credentials-led position in segments where environmental assurance influences procurement decisions.
The competitive field also includes firms with clearer emphasis on customization, branding, and export-oriented scale. Zhejiang Pando EP Technology Co., Ltd., in Zhejiang, China, specializes in wholesale paper sleeves for coffee cups, including kraft and custom options, with distribution reaching Europe, the US, and other markets. Suzhou Accum Packaging Co., Ltd., in Suzhou, China, manufactures custom paper cup sleeves with design flexibility for food and beverage packaging, supported by FSC and ISO certifications. HotShot Sleeves, based in the USA, concentrates on custom printed paper coffee sleeves and related beverage packaging for branding in the US market. Ibex Packaging, also US-based, supplies custom printed paper cup sleeves tailored for branding and insulation needs. LBP Manufacturing LLC, operating in the USA, offers insulated paper cup sleeves designed for hot beverage thermal protection in foodservice. Together, these players illustrate a market in which insulation performance, print personalization, certification credibility, and regional service capability all compete for relevance against price and scale.
The market structure itself reinforces the importance of careful positioning. With CR3 at 18.5 percent and CR5 at 24.2 percent, the industry is not dominated by a small number of universal incumbents. Instead, it rewards capability depth, customer-specific responsiveness, and supply reliability in ways that can enable focused players to hold defensible positions even as larger portfolios expand across adjacent categories. This fragmentation matters for strategy because it means share dynamics can move through product differentiation, customer lock-in, regional fulfillment quality, and compliance-driven specification changes rather than through sheer scale alone. The report uses this competitive context to help leaders identify where consolidation pressure is likely to build, where customer bargaining power may intensify, and where specialized positioning can be defended through technology, service, or sustainability credentials.
Regulatory Momentum, Material Economics, and Operating Conditions
Strategy in this market cannot be separated from the operating environment. Two structural forces are reshaping how paper cup sleeves are specified, sourced, and evaluated: regulation and raw-material economics. On the regulatory side, the EU Packaging and Packaging Waste Regulation entered into force in February 2025 and applies from August 2026, mandating extended producer responsibility schemes with modulated fees based on recyclability for packaging that includes paper products. In parallel, as of 2025, seven US states, including California, Colorado, Maine, Maryland, Minnesota, Oregon, and Washington, have enacted packaging EPR laws covering paper products and foodservice ware, with reporting and fee obligations now in play. California SB 54 further requires 100 percent of single-use packaging and food service ware to be recyclable or compostable by 2032, a requirement that directly affects sleeve design choices, material selection, and end-of-life narratives for hot-beverage packaging. These developments are not remote risks. They are becoming purchase criteria, cost drivers, and design constraints that influence supplier selection and product architecture well before the compliance horizon closes.
Worldwide Insulated Cup Sleeves Market
Material economics add a second layer of strategic sensitivity. Paper cup sleeves primarily use kraft paper or corrugated paperboard as the raw material for thermal insulation and structural integrity, so input cost behavior feeds directly into margin performance and pricing strategy. In this context, kraft paper prices in the first quarter of 2026 varied regionally, with China at USD 891 per metric ton and France at USD 1462 per metric ton. That range is more than a data point. It signals that sourcing geography, logistics structure, hedging behavior, and specification flexibility can determine whether a company absorbs cost pressure or passes it through. It also reinforces the value of understanding which material formats and design specifications provide the best combination of performance, compliance readiness, and cost control in each operating environment. The report builds these dynamics into its analysis so that readers can evaluate not just where the market is going, but how operating conditions will shape profitability along the way.
Why the Full Study Is Essential for 2026 Decision-Making
The worldwide paper cup sleeve market is expanding on a credible, multi-year curve, but growth alone does not create strategy. Competitive advantage will come from the ability to interpret segmentation shifts, anticipate specification pressure, manage material volatility, and align product portfolios with regulatory and customer expectations before those expectations harden into procurement mandates. The full study gives decision-makers the detailed segmentation logic, competitive context, development signals, and operating-condition analysis needed to turn that opportunity into action. It is designed for teams that must answer practical questions about where to invest, how to position for compliance, which customer segments carry the best value-and-risk balance, and how to build sourcing and product strategies that hold up under changing regional conditions. To access the complete segmentation analysis, forecast architecture, competitive profiles, and decision frameworks, visit the source page for the Worldwide Paper Cup Sleeve Market research and obtain the full intelligence set built for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Cup Sleeve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com