

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Managed Security Services Market to Hit $86.78 Billion by 2032, Growing at 11.5% CAGR

Strategic Intelligence for 2026: Navigating the Managed Security Services System Landscape
The enterprise security paradigm has fundamentally shifted. In an environment where threat vectors evolve faster than internal teams can patch, the Managed Security Services System market has emerged as a critical infrastructure layer for organizations of every scale. Our latest market research report provides a comprehensive, data-grounded evaluation of this sector, designed specifically to equip executive decision-makers with the situational awareness required for 2026 strategy formulation and capital allocation.
Drawing on historical performance spanning 2020 through 2025 and projecting through 2032, this analysis maps a market trajectory that has demonstrated remarkable resilience and compounding growth. The sector expanded from approximately 23.5 billion USD in 2020 to 40.5 billion USD by the base year of 2025, with forward modeling indicating a climb toward 44.27 billion USD in 2026 and a projected 86.78 billion USD by 2032. These figures reflect a compound annual growth rate of 11.5 percent throughout the forecast period, signaling sustained demand that outpaces broader IT services growth. For procurement leaders, CFOs, and security architects, this trajectory is not merely a number; it is a structural signal that managed security is transitioning from an optional outsourcing convenience to a non-negotiable operational requirement.
This report functions as a strategic compass. Rather than offering superficial vendor comparisons, it delivers operational frameworks, competitive mapping, and regulatory context that enable organizations to align their security outsourcing decisions with broader business objectives. The insights enclosed are structured to answer the questions that keep executives awake at night: Which service models will deliver sustainable ROI? How is the competitive landscape consolidating, and what does that mean for contractual leverage? And where should capital be deployed in 2026 to future-proof security operations without overcommitting to legacy architectures?
Macro Market Dynamics Shaping 2026 Decision-Making
The growth narrative of the Managed Security Services System market is being rewritten by intersecting technological, regulatory, and operational forces. At the center of these dynamics is the overwhelming security talent shortage that continues to widen globally. Organizations of every size are discovering that building and sustaining an in-house security operations center is increasingly cost-prohibitive, politically difficult within corporate budgets, and operationally fragile when key personnel depart. Managed service providers fill this gap by delivering continuous monitoring, threat hunting, incident response, and compliance oversight at a scale that internal teams simply cannot match.
Simultaneously, the regulatory environment has intensified dramatically. In early 2026, more than 300 data center-related bills were introduced across 30 US states, addressing energy costs, grid reliability, and special tariffs for large energy consumers such as data centers supporting security services. This regulatory wave directly influences the operating cost structures of providers delivering always-on monitoring and cloud-native security platforms. Complementing this state-level activity, the US White House Ratepayer Protection Pledge now requires hyperscalers and AI or data center operators to cover the full costs of energy generation and infrastructure, ensuring that household ratepayers are not burdened by the power demands of digital infrastructure expansion. For organizations evaluating managed security contracts, these policies introduce new considerations around where services are hosted, how data sovereignty requirements intersect with energy cost pass-throughs, and which providers have already optimized their infrastructure for regulatory resilience.
Cross-border data governance continues to evolve as another defining constraint. The United States has increasingly challenged foreign data sovereignty and localization requirements in recent trade reports, aiming to support cross-border managed security and cloud services. At the same time, the US Department of Justice Bulk Data Rule, effective from 2025, mandates stringent cybersecurity controls for certain bulk personal data transactions involving foreign parties. This creates a complex compliance matrix that managed security partners must navigate, and it elevates the strategic value of providers who can attest to jurisdictional awareness, audit readiness, and data handling architecture that satisfies both domestic and international regulators.
These dynamics are not isolated observations. They are embedded throughout the report's analysis of market concentration, service adoption patterns, and provider positioning, giving readers a realistic foundation for scenario planning rather than optimistic projections untethered from operational reality.
Competitive Ecosystem and the Providers Defining the Next Phase
The competitive landscape of managed security services is characterized by a blend of established technology conglomerates, specialized pure-play MSSPs, and emerging platform-native operators. Market concentration data indicates that the top three providers collectively command approximately 22.4 percent of total revenue, while the top five reach roughly 34.1 percent. This moderate concentration suggests an environment where scale players exert influence but significant differentiation and regional specialization remain possible, preventing complete market consolidation.
Managed Security Services System Market
Several organizations define the strategic contours of this space. IBM Security provides 24/7 Managed Security Services encompassing monitoring, management, and response to advanced threats, risks, and compliance needs across hybrid cloud environments, positioning itself as a provider capable of operating at enterprise complexity. Verizon leverages its global network infrastructure to deliver Managed Security Services that span threat detection, mitigation including DDoS, SASE capabilities, and incident response for enterprises and government clients, using network scale as a core competitive advantage. LevelBlue, formed from the combination of AT&T Cybersecurity and Trustwave, operates as a pure-play MSSP delivering 24/7 MDR, managed security, offensive security, and FedRAMP-authorized services, an architecture that appeals particularly to regulated and public sector buyers. Tata Communications delivers global Managed Security Services with a focus on network-integrated security monitoring and threat management, bringing international connectivity expertise into the security operations layer.
On the detection and response side, Secureworks provides managed threat detection and response services through its Taegis XDR platform, Arctic Wolf offers a Concierge Security team for 24x7 managed detection and response across endpoints, networks, and cloud, and eSentire delivers MDR with 20/7 expert-led security operations. Each of these organizations brings a distinct operational philosophy—platform-led, concierge-led, or network-integrated—creating meaningful differentiation for buyers with varied risk appetites and internal maturity levels.
Recent developments in 2025 and early 2026 illustrate how rapidly this competitive field is evolving. NWN launched an AI-enabled managed security operations suite in April 2026, incorporating MDR, offensive security services, ransomware protection, and vCISO services alongside new platform integrations, signaling a broad consolidation of advisory and defensive capabilities into unified operations platforms. Beyond was named the 2026 Google Cloud Security Managed Security Service Provider for EMEA, recognized for agentic SOC capabilities, underscoring the growing relevance of automated and semi-autonomous response architectures in regional markets. LevelBlue was named a Representative Vendor in the 2026 Gartner Market Guide for Outsourced Managed Security Services, reinforcing the credibility of pure-play MSSPs within analyst-recognized frameworks. Palo Alto Networks introduced Next-Generation Trust Security with certificate lifecycle automation designed to support managed security resilience, demonstrating how traditional platform vendors continue to reshape the managed services ecosystem through infrastructure trust mechanisms.
The report maps these players and developments not as a static vendor directory but as a living competitive topology. It examines how service bundling, platform automation, and partnership ecosystems are reshaping procurement leverage, contract flexibility, and long-term vendor stickiness. This framing enables organizations to evaluate providers against operational fit rather than marketing claims.
Report Architecture and Operational Content
The research has been constructed to serve as a working reference rather than a high-level summary. Content is structured across multiple analytical dimensions that directly support strategy, procurement, and risk management functions.
Service Model and Solution Coverage
The analysis examines the dominant managed security service categories shaping buyer demand. Managed Firewall and Network Security, Managed IDS and IPS, Managed Threat Intelligence and Response, and Vulnerability and Compliance Management each receive dedicated evaluation regarding adoption momentum, integration complexity, and the operational outcomes they deliver. The report contextualizes how these service lines intersect with broader architectures such as SASE, XDR, and agentic SOC models, enabling readers to assess which capabilities align with their current maturity and which gaps require staged investment.
Organization Size and Procurement Dynamics
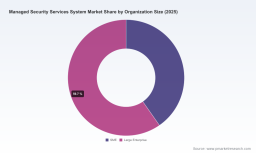
The market serves both small and mid-sized enterprises and large enterprises, but the purchasing behavior, risk tolerance, and service expectations differ substantially between these cohorts. The report disentangles these patterns, exploring how organizational scale influences contract structures, service bundling, internal resource supplementation strategies, and the financial justification for outsourcing versus building internal capabilities. This provides procurement leaders with a clearer lens for segmenting their organization's needs and matching them to service arrangements that reflect actual operational reality.
Regional Context and Cross-Border Considerations
Regional analysis is presented with attention to the operational and regulatory forces that shape deployment decisions, rather than as isolated market share tables. The interplay between energy policy, data sovereignty, localization requirements, and cross-border service delivery is examined in a way that helps organizations anticipate friction points in multi-region security operations. This regional framing is especially relevant for multinational enterprises and for providers expanding their managed security footprint across jurisdictions with diverging compliance expectations.
Competitive Benchmarking and Vendor Strategy
Beyond company profiles, the report delivers a structured competitive assessment that evaluates provider positioning, service differentiation, partnership ecosystems, and recent strategic moves. It explores how AI-enabled operations, certificate lifecycle automation, agentic SOC capabilities, and offensive security service integration are reshaping vendor offerings and buyer expectations. This competitive mapping is intended to support vendor evaluation, negotiation strategy, and long-term partnership selection, giving readers a defensible basis for decision-making in a crowded and fast-moving market.
Regulatory and Cost-Structure Implications
Regulatory developments are not treated as footnotes but as structural drivers that alter provider economics and buyer risk exposure. The analysis integrates the latest policy context surrounding data center energy regulation, hyperscaler cost obligations, data sovereignty challenges, and bulk data transaction controls to illustrate how these forces influence service pricing, hosting architecture, compliance overhead, and contract terms. By connecting regulatory dynamics to operational consequences, the report equips leaders to incorporate policy risk into their security outsourcing calculus.
Scenario Planning and 2026–2032 Outlook
The forecast period is treated as a range of plausible trajectories rather than a single deterministic line. Forward modeling incorporates historical performance from 2020 to 2025 and projects growth through 2032, enabling organizations to stress-test investment scenarios, capacity planning, and service evolution roadmaps. This scenario-oriented outlook supports budgeting discipline and strategic flexibility, allowing leaders to align security outsourcing commitments with the pace of organizational transformation and threat environment evolution.
Strategic Imperatives for Enterprise Decision-Makers
The core message of this research is that managed security services are entering a phase of maturation where differentiation is driven less by whether organizations outsource security and more by how precisely they select, govern, and integrate managed capabilities into their broader risk and operations strategy. The data confirms sustained market expansion, but the strategic value for 2026 lies in understanding which service models, provider archetypes, and contractual structures will deliver durable value as the competitive field consolidates and regulatory pressure intensifies.
Leaders evaluating this market in 2026 should treat the following as guiding priorities: aligning managed service scope with actual internal capability gaps, scrutinizing provider architectures for data handling and jurisdictional compliance, evaluating the operational maturity of provider SOC and response functions rather than relying on portfolio breadth alone, and anticipating cost-structure shifts driven by energy policy and infrastructure obligations. The organizations that approach these decisions with disciplined analysis will be better positioned to convert managed security from a compliance expense into a strategic operational advantage.
Manned Security Services Market
Complete access to the full dataset, detailed segmentation analysis, vendor benchmarking frameworks, and scenario models is available through the full report. The executive summary provided here is intended to establish the analytical foundation and demonstrate the depth of coverage, while encouraging decision-makers to consult the complete intelligence package for the granular data required to translate strategic direction into actionable procurement and investment plans.
For detailed analysis of this topic, please visit the official page: Managed Security Services System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com