

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sapphire Powder Market Hits USD 545.0M in 2025, Forecasts USD 889.56M by 2032

Strategic Intelligence for the 2026 Market Cycle: Navigating the Worldwide Sapphire Powder Landscape
The global sapphire powder market is entering a critical inflection point. As industries from semiconductor manufacturing to advanced optics demand higher purity, tighter specifications, and more sustainable supply chains, the strategic decisions made in 2026 will define competitive positioning for the rest of the decade. Our latest Worldwide Sapphire Powder Market research report provides a comprehensive, data-backed foundation for those decisions, combining historical trajectory analysis with forward-looking forecasts that extend through 2032.
This briefing outlines the core insights embedded in the full study, demonstrates how macroeconomic and segmentation dynamics shape operational strategy, and highlights the competitive and regulatory forces that procurement leaders, R&D directors, and corporate strategists must monitor. The objective is straightforward: equip executive teams with the contextual intelligence needed to allocate capital, secure feedstock, and align product roadmaps with where the market is actually heading.
Market Trajectory and the 2026 Decision Window
Sapphire powder has evolved from a niche industrial material into a strategic enabler across multiple high-technology sectors. Historical data from 2020 through 2025 reveals a consistent upward trajectory, with market revenue climbing steadily as downstream demand matured and manufacturing capabilities expanded. The base year of 2025 anchors this growth narrative, and our forecast period from 2026 through 2032 projects continued expansion at a compound annual growth rate of 7.25 percent.
By 2026, the market is positioned to cross significant revenue thresholds, and the momentum carries forward with measurable acceleration in later forecast years. This trajectory is not merely a function of volume growth; it reflects structural shifts in how sapphire-based materials are specified, sourced, and integrated into advanced manufacturing workflows. For decision-makers, the implication is clear. Planning cycles that treat sapphire powder as a stable commodity input will underestimate both the cost volatility and the performance differentiation emerging in the supply base.
The forecast model accounts for multiple macro variables, including downstream capacity expansions, purity specification tightening, and regional supply-demand rebalancing. Rather than presenting a single static number, the full report maps a range of scenario-dependent outcomes that allow strategists to test assumptions around capacity utilization, pricing tolerance, and technology adoption timelines.
Segmentation Dynamics That Shape Sourcing Strategy
Understanding where demand originates and how purity requirements are evolving is essential for building resilient procurement strategies. The market is segmented across three analytical dimensions that our research evaluates in depth: geography, purity level, and application.
Geographically, the market reflects a highly uneven distribution of consumption and production capacity. Demand is concentrated in regions with mature electronics manufacturing ecosystems, advanced ceramic producers, and established optical component supply chains. The full report unpacks the regional architectures that drive this distribution, including logistics constraints, localized feedstock availability, and the strategic behavior of regional distributors and manufacturers. These regional dynamics directly affect lead times, qualification cycles, and total cost of ownership for end users.
Purity classification is equally decisive. The market separates into standard grade material, high-purity ranges typically spanning 4N to 5N, and ultra-high purity categories exceeding 5N. As sapphire crystal growth and semiconductor-adjacent applications push performance boundaries, the premium attached to higher purity grades is intensifying. Material specified for defect-sensitive crystal growth or alpha-emission-sensitive ceramic components cannot simply be substituted with standard offerings without risking yield, contamination, or performance degradation. The report quantifies how purity segmentation interacts with pricing behavior, qualification barriers, and supplier capability matrices.
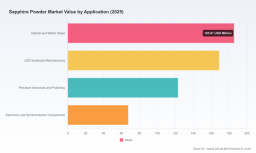
Application segmentation further refines the strategic picture. Demand streams include optical and watch glass production, LED substrate manufacturing, precision abrasives and polishing workflows, and electronic and semiconductor component fabrication. Each application places distinct requirements on particle morphology, carbon content, phase composition, and batch consistency. The full study connects these application requirements to downstream adoption patterns, enabling readers to identify which demand pockets are most likely to expand, which are vulnerable to substitution, and where supplier relationships carry the greatest strategic weight.
Worldwide Sapphire Powder Market
Internal data details for each segment, including exact regional values, purity-level splits, and application-specific revenue contributions, are reserved for the complete report. This deliberate structure allows executives to first absorb the strategic architecture before drilling into the figures that matter most for their specific operating context.
Competitive Landscape and the Rise of Differentiated Supply
The sapphire powder supply base is not monolithic. It includes integrated crystal growers, specialized high-purity alumina producers, enhanced-process manufacturers, and global distributors. Our research tracks a core set of companies whose technological positioning, product architecture, and recent commercial moves illustrate the broader competitive dynamics shaping the market.
Polar Performance Materials, based in Oakville, Ontario, Canada, has built its offering around high-purity alumina powders designed as consistent, defect-resistant feedstock for synthetic sapphire crystal growth. Its CRYSTALGuard portfolio reflects a clear strategic emphasis on feedstock reliability, an increasingly important factor for growers seeking to reduce defect rates and stabilize growth cycles. The company also supplies tailored HPA powders for technical ceramics and adjacent applications, signaling a diversified but technically coherent product strategy.
Alpha HPA Ltd, headquartered in Sydney, Australia, has emerged as a company to watch because of its combination of process differentiation and aggressive capacity expansion. Its Ultra AAP series includes high-sintering, low-alpha alumina powders produced through a proprietary solvent extraction route, alongside Ultra Sapphire low-carbon synthetic sapphire materials. Recent disclosures show Japanese semiconductor customers upgrading letters of intent for high-piry alumina volumes, with additional increases anticipated. At the same time, the company has raised its sapphire sector order book for sintered HPA tablets and announced the commencement of high-volume alumina dispersion production for CMP slurries at its Stage 1 facility. These moves suggest a supplier that is simultaneously scaling volume and deepening qualification penetration in semiconductor-adjacent channels.
AdValue Technology LLC, located in Tucson, Arizona, supplies high-purity alumina powders produced via an enhanced Bayer process. Its material portfolio is positioned for sapphire and ruby crystal growth, as well as advanced ceramic and high-temperature applications. This manufacturing pathway provides a distinct cost and scalability profile, making the company relevant for buyers evaluating the trade-offs between process origin, purity consistency, and supply availability.
Juropol Sp. z o.o., with its POLYCOR subsidiary based in Ozarow Mazowiecki, Poland, approaches the market from the crystal growth side rather than the pure powder supplier angle. It sources and refines ultra-pure alumina feedstock using proprietary technology designed specifically for high-quality sapphire crystal production in LED and semiconductor applications. This vertical integration illustrates a broader tendency in the market: a growing number of participants are tightening control over feedstock specifications to protect crystal quality and reduce variability.
Goodfellow Corporation operates as a globally connected distributor of high-purity sapphire and alumina materials. Its role is particularly relevant for research, prototyping, and smaller-scale industrial applications where flexibility, material variety, and rapid fulfillment matter more than bulk commodity pricing. Distributors like Goodfellow remain important nodes in the value chain, especially for buyers who require broad material access without committing to large dedicated supply contracts.
The full report places these companies within a wider concentration framework, showing how market share is distributed among leading participants and what that concentration implies for pricing power, supply security, and negotiation leverage.
Industry Dynamics, Cost Drivers, and Sustainability Signals
Pricing, energy intensity, and environmental performance are increasingly intertwined in sapphire powder sourcing decisions. Several developments illustrate why this is no longer a peripheral concern.
On the cost side, specialized high-purity alumina grades used in sapphire growth and advanced ceramics trade within a meaningful price band that varies by purity, phase, and form factor. The range reflects not only material specifications but also the process complexity required to produce low-carbon, low-alpha, and low-impurity variants. Buyers who understand these cost drivers can better evaluate whether a premium price is justified by yield improvement, qualification risk reduction, or downstream performance gains.
Energy intensity in upstream alumina production remains a structural cost pressure. Bauxite-derived alumina production consumed a substantial share of global energy in recent years, and that baseline energy demand contributes to volatility in feedstock economics. For sapphire powder buyers, this translates into a need to anticipate cost pass-through effects, especially where conventional process routes dominate supply.
Sustainability differentiation is becoming a competitive variable rather than a compliance checkbox. One notable example is a proprietary low-carbon alumina process that lowers emissions substantially compared with traditional methods. In a market where downstream brands and semiconductor customers are increasingly scrutinizing supplier environmental profiles, such differentiation can influence sourcing decisions, qualification priority, and long-term partnership strategy. The report incorporates these signals into its broader dynamics assessment, connecting environmental performance to commercial outcomes rather than treating it as a standalone narrative.
Regulatory and specification-driven requirements are also tightening in sensitive application areas. Certain high-purity alpha alumina powders must meet strict non-detect alpha emission thresholds for use in components where uranium and thorium contamination must be minimized. These specifications add qualification complexity, but they also raise barriers to entry and reward suppliers with proven process control. The full research examines how such technical requirements shape market access and supplier selection.
Why the Full Report Matters for 2026 Strategy
Executive teams cannot afford to rely on fragmentary market signals when making sourcing, expansion, or technology-adoption decisions. The Worldwide Sapphire Powder Market research is designed to function as an operational decision-support tool, not simply a high-level overview. It integrates historical performance, forward forecasts, segmentation logic, competitive profiling, and industry dynamics into a single analytical framework.
The report's practical content includes market sizing and growth projections anchored to a clear base year and forecast horizon, segmentation analysis that distinguishes regional, purity, and application drivers, and a competitive assessment that connects company capabilities to market behavior. It also examines market concentration patterns and the implications for supply security and negotiation strategy. For strategists, this means the report can be used to answer questions such as:
- Where is demand most likely to expand, and which specification shifts are accompanying that expansion?
- How do purity and application requirements influence supplier qualification, total cost, and substitution risk?
- Which competitors are scaling capacity, pursuing differentiation, or deepening relationships with demanding downstream customers?
- What dynamics are likely to affect pricing, energy-related cost pressure, and sustainability-driven sourcing preferences?
- How concentrated is the supply base, and what does that concentration mean for procurement resilience?
The content is structured so that both broad strategic planning and functional decision-making can be supported from the same source. Corporate development teams can use it to assess market entry or partnership opportunities. Procurement and supply chain leaders can use it to map risk concentration and qualification pathways. R&D and product leaders can use it to align material specifications with market-available purity and phase options.
From Insight to Action: Accessing the Complete Intelligence
The macroeconomic trajectory, segmentation architecture, competitive signals, and dynamic cost and sustainability factors described here are only the beginning of what the full study contains. The report goes further by presenting detailed sizing tables, segmentation splits, concentration metrics, and company-level profiles that connect strategic narrative to actionable figures. These deeper layers are essential for teams that need to quantify opportunity, benchmark suppliers, and model demand under different operational assumptions.
To access the complete dataset, segmentation detail, and competitive intelligence described in this briefing, explore the full Worldwide Sapphire Powder Market research. The study is intended for decision-makers who need validated market context before committing resources in 2026 and beyond. With demand continuing to broaden across optics, LED substrates, precision abrasives, and electronic components, the organizations that act on accurate, structured intelligence will be best positioned to manage cost, quality, and supply resilience in a rapidly maturing market.
Sapphire Glass Market
For detailed analysis of this topic, please visit the official page: Worldwide Sapphire Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com