

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Carbon Composite Tubes and Pipes Market Hits $496.5M in 2025, 8.5% CAGR to 2032

Navigating the Structural Shift: Strategic Intelligence for the Worldwide Carbon-Carbon Composite Tubes and Pipes Market in 2026
The global industrial landscape in 2026 is defined by a convergence of extreme-performance material requirements and geopolitical supply chain recalibration. At the intersection of these forces lies the worldwide market for carbon-carbon composite tubes and pipes. This sector is no longer a niche supplier to specialized furnace builders; it has become a critical enabler for semiconductor capacity expansion, next-generation aerospace platforms, and high-efficiency industrial thermal systems. For executives, capital allocators, and R&D directors, understanding the trajectory of this market is not merely an academic exercise. It is a prerequisite for securing supply, mitigating tariff exposure, and positioning product portfolios for the decade ahead.
Worldwide Carbon Carbon Composite Tubes and Pipes Market
Carbon-Carbon Composite Material Market
Our latest market research, Worldwide Carbon Carbon Composite Tubes and Pipes Market, is designed to convert complex market signals into actionable strategy. Below, we outline the structural dynamics, competitive fault lines, and regulatory inflection points that will define decision-making throughout 2026 and the broader forecast horizon.
The Macro Trajectory: Sizing the Window of Opportunity
Over the historical window from 2020 through 2025, the worldwide revenue base for carbon-carbon composite tubes and pipes expanded from a baseline of approximately 330.5 million USD to 496.5 million USD in the most recent base year. This growth path reflects a compounding demand environment where performance tolerances are tightening and replacement cycles for high-wear thermal components are accelerating. Looking forward, the market is projected to continue its expansion through 2032, with revenue scaling toward a trajectory that underscores both volume growth and value migration toward higher-specification grades.
The forward arc is characterized by a sustained compound annual growth rate of 8.5 percent across the forecast period from 2026 to 2032. To put this in operational context, a mid-teens growth trajectory sustained over multiple years implies that the market will more than double its scale relative to the 2025 base before the close of the forecast horizon. For strategists, the implication is clear: backlog visibility, capacity reservation, and technology road-mapping must be locked in now rather than reactive to spot-market tightness later.
Embedded within this headline trajectory is meaningful volatility by segment and region. The aggregate figure masks a competitive battleground where process economics, material availability, and application-specific qualification cycles diverge sharply. This is precisely why disaggregated visibility matters. Managers who rely on top-line aggregates risk over-indexing on growth sectors that are margin-dilutive or under-indexing on stable, high-margin pockets where supplier lock-in and engineering partnerships dictate market access. Our report isolates these layers without exposing the granular figures prematurely, reserving the full dataset for clients who need to build supply plans, pricing models, and go-to-market roadmaps.
Structural Realities Shaping 2026 Strategy
Three structural forces converge to redefine how buyers and suppliers will operate in 2026 and beyond. Each carries consequences for sourcing strategy, product architecture, and regional footprint.
- Raw material architecture is stratified by precursor chemistry. PAN-based precursors continue to dominate carbon fiber production used in carbon-carbon composites, reflecting broad-based demand across non-aerospace sectors and broader composite ecosystems. At the same time, pitch-based carbon fiber precursors, valued for high-modulus and thermal properties in specialty carbon-carbon applications, are projected to grow significantly in targeted high-performance segments. This bifurcation means that tube and pipe manufacturers cannot treat raw material strategy as a commodity call. Grade selection, precursor sourcing, and densification method choice interact directly with qualification timelines and end-market acceptance.
- Regulatory friction is entering the cost equation in new ways. In the United States, effective March 2025, tariffs on carbon fiber materials from targeted countries increased to 25 percent for raw carbon fiber tow and 17.5 percent for prepreg materials under a Section 301 expansion. For a market where reinforcement materials are foundational inputs, this is not an administrative detail; it is a pricing and sourcing variable that reshapes landed cost comparisons across origins. Simultaneously, the EU Carbon Border Adjustment Mechanism is scheduled to impose fees on selected imports for greenhouse gas emissions starting in 2026. As production footprints and logistics routes are reconsidered, the carbon intensity of upstream material flows becomes a competitive variable, not just a compliance one.
- Demand-side end-use intensity is accelerating qualification and substitution. In semiconductor and solar silicon production, thermal uniformity and chemical inertness requirements are intensifying as wafer processes scale and throughput expectations rise. In aerospace and defense systems, weight-to-performance ratios and extreme-temperature resilience continue to drive engineering adoption of carbon-carbon solutions where metallic alternatives fall short. Industrial furnace operators face pressure on energy efficiency and component life, while medical and laboratory equipment manufacturers seek high-precision, low-contamination tubing for specialized thermal and vacuum environments. Each vertical carries a distinct barrier-to-entry profile, and understanding where qualification risk can be compressed versus where it remains a durable moat is central to market participation.
A recently observed market entry reinforces the innovation and commercialization tempo. In October 2025, Super Carbon Composites Technologies (SCCT) launched as a startup focused on commercialization of ultra high-density carbon/carbon composites using FAST/SPS densification for aviation, space, industrial, semiconductor, and automotive applications. New entrants pursuing advanced densification routes are not merely adding optionality; they are signaling that production economics, cycle times, and achievable density windows are still being actively contested. For incumbents and buyers alike, this underscores the need to monitor process differentiation, not just brand names.
The Competitive Architecture
The competitive field is shaped by a blend of integrated manufacturers, material suppliers, and specialized converters. Market concentration data indicate that the top three competitors collectively hold about 42.5 percent of revenue, while the top five reach approximately 58.3 percent. This profile suggests a market that is meaningfully consolidated at the top yet still broad enough in the tail for specialized players to command attractive niches through engineering depth, regional proximity, or proprietary process know-how.
Strategic mapping of the core companies reveals several archetypes that matter for 2026 planning:
- High-temperature component specialists with direct tube and pipe output. CFCCARBON CO. LTD, based in Beijing, manufactures carbon-carbon composite rods, tubes and pipes using carbon fiber reinforced carbon matrix for high-temperature applications. SHJ Carbon, headquartered in China, produces carbon-carbon composites including tubes and components for thermal applications with more than 25 years of experience in high-temperature carbon materials. Bost Carbon Materials Co. Ltd., in Hunan, operates as a high-tech enterprise producing carbon-carbon composite materials alongside rigid and soft felts for high-temperature insulation and structural applications. These players anchor the production-side base where application-specific thermal performance is the primary value driver.
- Integrated and premium-class tube manufacturers in Europe. SGL Carbon, based in Wiesbaden, Germany, is an integrated manufacturer offering carbon-based products and solutions applicable to high-performance carbon-carbon composite tubes and pipes. Carbon Composite AG, in Germany, manufactures premium-class carbon precision tubes made in Germany, focusing on high-rigidity lightweight carbon composite tubing. Epsilon Composite, located in Gaillan-en-Médoc, France, is a specialist in high-performance lightweight carbon fiber tubes and profiles via pultrusion and pullwinding, with capabilities extending to advanced carbon composites. In a context of tariff escalation and border adjustment pressure, such European-based capacity can carry strategic advantages for customers with regional compliance and logistics priorities.
- Carbon fiber and reinforcement material leaders shaping the input base. Toray Industries in Tokyo is a global leader in carbon fiber materials used as key reinforcement for carbon-carbon composite tubes and pipes in advanced applications. Teijin Limited, also in Tokyo, supplies advanced carbon fiber raw materials and prepregs supporting production of carbon-carbon composite tubes and pipes. Mitsubishi Chemical, likewise headquartered in Tokyo, provides carbon fiber divisions and materials for composite tube and pipe manufacturing including carbon-carbon variants. Hexcel Corporation, in Stamford, Connecticut, manufactures advanced composite materials including carbon reinforcements for high-performance carbon-carbon composite tubes. For downstream tube producers, the relationship with these material houses influences grade availability, qualification support, and cost stability.
The competitive reality in 2026 is not simply about who has the largest revenue base. It is about who can align reinforcement supply, densification choice, and application qualification into a defensible commercial offering. This is where our report’s competitive profiling and capability mapping become operational tools rather than static lists.
What the Report Delivers for Decision-Making
The full study is constructed to support executive, procurement, engineering, and investor use cases simultaneously. It is organized to convert macro signals into segment-level clarity, then into competitive posture and strategic options. Among the core deliverables are:
- Market sizing and forecasting that contextualizes historical evolution from 2020 through 2025 and maps the projected trajectory through 2032, with attention to the growth rate and revenue scale that frame capacity and investment discussions.
- Segment-level decomposition by region, by process type, and by application, allowing managers to isolate the pockets where volume, margin, and qualification dynamics differ and to align sourcing and product roadmap decisions accordingly.
- Process-type comparison across chemical vapor infiltration and liquid phase impregnation, including the operational and commercial implications of each route for throughput, property profiles, and application fit.
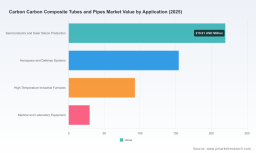
- Application-level analysis spanning semiconductor and solar silicon production, aerospace and defense systems, high-temperature industrial furnaces, and medical and laboratory equipment, with a focus on adoption drivers and barriers in each vertical.
- Regional assessment covering North America, Europe, Asia Pacific, and the rest of the world, framed by the interaction of demand geography, production location, and the tariff and border-adjustment environment.
- Competitive profiling of the core companies, with capability summaries, geographic alignment, and strategic positioning relevant to partnerships, sourcing, and market entry evaluation.
- Contextual dynamics on raw material precursors, regulatory developments, and recent industry developments such as new venture launches, woven into the market narrative to support scenario interpretation.
Crucially, the report is built to prevent over-reliance on headline numbers. Because segment splits, regional shares, and application-level revenue concentrations carry the operational nuance that top-line totals cannot, the study unpacks these layers with the level of granularity needed to inform procurement timing, negotiation leverage, and product positioning. The full detail set is available through the source page, where the complete segmentation tables, company profiles, and scenario framing can be accessed in full.
Why 2026 Is the Decision Year
The current moment is not simply another year in a growth curve. Several converging conditions make 2026 a pivotal planning window:
- Tariff and border-adjustment structures are moving from announcement to effect, altering landed-cost comparisons and prompting re-evaluation of supply origins, inventory buffers, and dual-sourcing strategies.
- Precursor mix dynamics are shifting in relevance as end-use applications demand more differentiated modulus and thermal behavior, making grade selection and supplier qualification more consequential than ever.
- Innovation entrants are advancing densification and processing options that could reshape cost and property trade-offs, meaning incumbents and buyers need to monitor technical disruption, not just price.
- Application-side demand intensity is rising across high-value verticals, increasing the importance of qualification speed, delivery reliability, and engineering partnership quality as competitive differentiators.
In this environment, executives who wait for fully matured market clarity will find themselves reacting to price spikes, allocation constraints, and qualification windows that have already closed. Those who build strategy on the back of integrated market intelligence, competitive mapping, and regulatory scenario alignment will be positioned to secure capacity, choose the right reinforcement and process architecture, and align product roadmaps with the demand cycles that matter most.
Accessing the Full Intelligence
This article is intended as a strategic preview: a demonstration of the analytical depth, structural framing, and competitive context that underpin our Worldwide Carbon Carbon Composite Tubes and Pipes Market research. It is not the full decision-support package. The complete study contains the detailed segmentation data by region, process type, and application, together with the company-level profiles, market concentration analysis, and regulatory and raw-material context needed to build sourcing plans, pricing models, and investment theses for 2026 and the forecast period through 2032.
For teams responsible for supply strategy, product development, regional expansion, or competitive positioning, the full report provides the granularity and scenario framing necessary to move from awareness to execution. The source page is where the complete dataset, segmentation splits, and detailed profiles can be reviewed and integrated into internal planning workflows. In a market where timing, qualification, and input-cost exposure are decisive, the difference between reactive and proactive strategy often comes down to data resolution. That resolution is available in the full study, and 2026 is the year to put it to work.
For detailed analysis of this topic, please visit the official page: Worldwide Carbon Carbon Composite Tubes and Pipes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com