

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mining Valve Market Hits $5.87B in 2025, Set to Reach $7.8B by 2032 at 4.15% CAGR

Strategic Intelligence for the Mining Valve Market: Navigating Growth and Complexity in 2026
Executive Overview: The Strategic Imperative
The mining sector stands at a critical inflection point. As operational environments become increasingly harsh and regulatory scrutiny intensifies, the infrastructure supporting fluid control and material handling demands unprecedented reliability. Valves are no longer mere components; they are critical determinants of operational uptime, safety compliance, and cost efficiency. For executives and strategic planners, understanding the trajectory of the mining valve market is essential for securing supply chains and optimizing capital expenditure.
PW Consulting's latest market research provides a comprehensive lens into this evolving landscape. This study is designed not merely as a data repository but as a decision-making toolkit for 2026 and beyond. By analyzing historical performance and projecting future trends, we offer the clarity needed to navigate a market characterized by volatile raw material costs and shifting environmental mandates.
Macro Market Trajectory: Growth and Stability
The overarching narrative of the mining valve market is one of steady, resilient expansion. Based on historical data spanning from 2020 to 2025, the market has demonstrated a consistent upward trend in revenue value. The overall market size has grown from approximately 4,820 Million USD in 2020 to an estimated 5,867 Million USD in the base year of 2025. This five-year historical analysis establishes a robust baseline for understanding current market health.
Looking forward, the forecast period from 2026 to 2032 suggests continued growth, albeit with nuanced fluctuations typical of capital-intensive industries. The market is projected to reach significant valuation milestones by the end of the forecast window. Our analysis indicates a Compound Annual Growth Rate (CAGR) of 4.15 percent during the forecast period. This rate reflects a balance between increasing mining output in key regions and the technological upgrades required to meet modern safety and efficiency standards.
For strategic planners, this trajectory implies that demand will not contract but will instead evolve in complexity. The growth is not uniform across all segments, requiring a nuanced approach to market entry or expansion. The data underscores the importance of timing in procurement and inventory management, as market valuations are expected to see notable shifts between 2026 and 2032.
Segmentation Dynamics: Types, Applications, and Geography
Understanding where value is generated within the market is crucial for targeted strategy. Our research dissects the market into three primary dimensions: product type, application, and region. However, the strategic value lies not just in the size of these segments but in the interplay between them.
By product type, the market encompasses a variety of valve solutions, including ball valves, gate valves, butterfly valves, knife gate valves, and other specialized types. Each type serves distinct functional requirements within mining operations. For instance, knife gate valves are often critical for slurry handling, while ball valves may dominate in general fluid control. The distribution of revenue across these types highlights varying levels of technological sophistication and maintenance requirements.
Mining Valve Market
In terms of application, the market serves diverse mining activities. Key application areas include mineral fuels, iron and ferro-alloys, non-ferrous metals, and industrial minerals. The demand drivers differ significantly across these applications. High-volume extraction sectors may prioritize cost-effectiveness, while processing-intensive sectors might focus on precision and durability. Understanding the revenue contribution of each application helps companies align their product portfolios with the most lucrative opportunities.
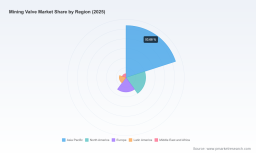
Geographically, the market is distributed across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa. Regional dynamics are influenced by local mining output, infrastructure development, and regulatory environments. While some regions show higher volume consumption due to extensive mining operations, others may exhibit higher value density due to stricter compliance requirements or advanced technological adoption. Our detailed segmentation analysis reveals these regional nuances without exposing specific sensitivity data that could compromise strategic advantage.
Competitive Landscape: Key Players and Strategic Moves
The market structure is moderately concentrated, with a Competitive Ratio of 3 (CR3) at 28.5 percent and a CR5 at 42.3 percent. This indicates that while major players hold significant influence, there is substantial room for specialized providers and regional manufacturers. The competitive arena features a mix of global industrial giants and niche specialists, each vying for advantage through product innovation and service excellence.
Several key companies define the current competitive landscape. Emerson Electric Co., headquartered in St. Louis, Missouri, offers a suite of solutions including Clarkson knife gate valves and Fisher control valves. Their focus on severe service solutions for abrasive slurries and tailings positions them strongly in harsh mining environments. Recently, Emerson has demonstrated a commitment to innovation, such as the implementation of Fisher CV500 eccentric plug valves in ore mining water addition processes in October 2025, aimed at improving control and reducing costs. Furthermore, their expansion of Fisher FIELDVUE digital valve controllers with advanced cybersecurity features in November 2025 highlights a shift towards smart, connected valve systems.
The Weir Group PLC, based in London, UK, provides Delta Industrial knife gate valves designed for heavy-duty, abrasive, and high-temperature slurry applications. Their engineering focus aligns with the need for durability in mineral processing. Similarly, Metso from Helsinki, Finland, specializes in knife gate valves, dart valves, and slurry valves for minerals processing, covering grinding circuits and tailings management.
Regional players also play a vital role. NewCon Company in Hibbing, Minnesota, manufactures abrasion-resistant knife gate slurry valves using USA steel and iron, catering to severe service needs. John Valves, located in Ballarat, Victoria, Australia, leverages over 130 years of experience to supply high-quality valves tailored for the Australian mining industry. Flowserve Corporation in Irving, Texas, and Velan Inc. in Montreal, Canada, further contribute to the supply of industrial and high-performance valves for mining and severe service environments.
Recent product launches, such as Emerson's Fisher Valve Series 9000 heavy-duty ball valves in January 2024, illustrate the ongoing race to engineer solutions that withstand harsh mining conditions. These developments signal to the market that reliability and specialization are key differentiators.
Market Dynamics: Cost Pressures and Regulatory Shifts
External factors significantly influence market behavior and require constant monitoring by industry stakeholders. Raw material costs remain a primary concern. Fluctuations in prices of stainless steel, cast iron, and specialty alloys used in mining valves significantly impact production costs. Steel and high-alloy material costs continue to pressure valve manufacturers due to global commodity price trends affecting carbon steel and stainless steel valve bodies. This volatility necessitates agile supply chain strategies and potentially long-term material sourcing agreements to stabilize margins.
Regulatory environments are another critical dynamic. Stricter environmental regulations drive demand for valves meeting specific emission standards and supporting water recovery and tailings management in mining. As governments impose tighter controls on environmental impact, mining operators must upgrade their infrastructure to comply. This creates a pull-through demand for valves that facilitate water recovery and ensure safe tailings management. Companies that can certify their products against these emerging standards will gain a competitive edge.
These dynamics create a complex operating environment where cost management and compliance are equally important. The interaction between raw material price trends and regulatory requirements shapes the overall profitability and growth potential for valve manufacturers and suppliers.
Internalizing Intelligence: Practical Applications for 2026
This market research is structured to provide actionable intelligence across several functional areas. The report delves into technical specifications, supplier capabilities, and performance metrics that allow procurement teams to evaluate vendors beyond price alone. By understanding the engineering nuances of different valve types, organizations can reduce failure rates and maintenance downtime.
For product development teams, the segmentation analysis offers insights into unmet needs within specific application areas. Whether it is enhancing corrosion resistance for certain chemical environments or improving flow coefficients for high-volume slurry transport, the data guides R&D priorities. The competitive profiling section helps identify gaps in the current market offerings, revealing opportunities for differentiation.
Valves Market
Strategic planners will find value in the forward-looking forecasts. The projected market size and growth rates allow for more accurate budgeting and capacity planning. Knowing the anticipated demand trajectory helps in negotiating better terms with suppliers and securing capacity in advance of market tightness. Furthermore, the regional breakdowns assist in assessing market entry risks and opportunities for geographic expansion.
The study also addresses the integration of digital technologies. As seen in recent developments regarding digital valve controllers and remote diagnostics, the industry is moving towards predictive maintenance and real-time monitoring. Our research evaluates the adoption rates and benefits of these technologies, helping companies decide on their own digital transformation roadmaps.
Conclusion: Navigating the Future with Precision
The mining valve market in 2026 presents a landscape of opportunity tempered by complexity. The steady growth projected through 2032 offers a favorable backdrop for investment and expansion. However, success depends on the ability to navigate raw material volatility, meet stringent regulatory standards, and leverage technological advancements. The competitive landscape remains dynamic, with established players continually innovating to maintain their position.
PW Consulting's Mining Valve Market study provides the foundational intelligence required to make informed decisions in this environment. By combining macro-level market data with deep dives into competitive strategies and market dynamics, this report equips stakeholders with the tools needed to optimize their operations and strategy. For those seeking to fully capitalize on the market's potential, accessing the complete dataset and detailed analysis is essential. We invite you to explore the full report to unlock the specific insights that will drive your organization's success in the coming years.
For detailed analysis of this topic, please visit the official page: Mining Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com