

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Percutaneous Nephroscope Market Hits $557.24M in 2025, 6.19% CAGR to 2032

Strategic Intelligence: Navigating the Global Percutaneous Nephroscope Market (2026-2032)
The landscape of urological intervention is undergoing a paradigm shift, driven by an aging global population, the rising prevalence of nephrolithiasis, and the relentless adoption of minimally invasive surgical techniques. For stakeholders positioning themselves in the medical device sector, the Worldwide Percutaneous Nephroscope Market represents a critical vector of growth and competitive intensity. PW Consulting is pleased to introduce our comprehensive market research initiative, designed to decode the complex dynamics defining this specialized segment through 2032.
Our latest analysis indicates that the global market for percutaneous nephroscopes reached a valuation of USD 557.24 Million in 2025. Looking ahead, the trajectory suggests sustained momentum, with the market projected to expand to USD 575.56 Million in 2026 and further accelerate to USD 849.02 Million by 2032. This growth corresponds to a Compound Annual Growth Rate (CAGR) of 6.19 percent over the forecast period. These macro-level figures underscore a robust demand environment, yet they only scratch the surface of the strategic opportunities available for agile market participants.
Executive Context: The Foundation of Urological Care
Percutaneous nephroscopy remains a cornerstone procedure in the management of complex kidney stones. The procedure, known as percutaneous nephrolithotomy (PCNL), requires precise instrumentation to access the renal collecting system. As healthcare systems worldwide prioritize cost-efficiency and patient outcomes, the instruments used in these procedures must balance durability, optical clarity, and ergonomic functionality. Our research delves into how these clinical requirements intersect with manufacturing capabilities and reimbursement frameworks to shape market viability.
The period from 2020 to 2025 provided a rich historical baseline for our analysis. Revenue grew from USD 412.5 Million in 2020 to USD 557.24 Million in 2025. This five-year historical evolution reflects not only increased surgical volumes but also the gradual upgrading of equipment in established healthcare markets. As we transition into the forecast period of 2026 to 2032, the drivers of growth shift slightly, influenced by regulatory adaptations, technological integration, and regional healthcare infrastructure development.
Competitive Architecture: Key Players and Strategic Movements
The market is characterized by a moderately concentrated competitive landscape. Our analysis highlights a Competitive Ratio of the top three companies at 58.4 percent, while the top five players collectively account for 72.15 percent of the market share. This concentration suggests that incumbents hold significant sway over pricing and technology standards, yet there remains space for specialized innovators to carve out niches based on product differentiation.
Several key entities define the operational standards of this industry. Karl Storz SE & Co. KG, headquartered in Tuttlingen, Germany, continues to lead as a primary provider of rigid percutaneous nephroscopes. Their product lines, including the NAGELE and PARRECA models, are optimized for PCNL procedures with integrated camera systems. In March 2024, Karl Storz showcased updated IMAGE1 S-compatible percutaneous nephroscopes at the EAU 2024 Congress, signaling a commitment to optical enhancement technologies.
Olympus Corporation, based in Tokyo, Japan, maintains a strong presence through its OES Pro percutaneous nephroscopes. These instruments come in various sizes, such as the 24 Fr model, designed for kidney stone fragmentation and extraction. In November 2023, Olympus updated its global urology catalog to include new 22 Fr percutaneous nephroscope variants with enhanced optics, demonstrating a strategy focused on expanding size options to accommodate diverse anatomical requirements.
Richard Wolf GmbH, located in Knittlingen, Germany, specializes in urological endoscopes including percutaneous nephroscopes like the 26 Fr model with continuous irrigation for PCNL applications. In September 2023, the company received an updated EU MDR certification for its percutaneous nephroscope lineup, ensuring compliance with stringent European safety regulations. This regulatory milestone underscores the importance of compliance in maintaining market access within the European Union.
Other notable contributors include PENTAX Medical (HOYA Group), also headquartered in Tokyo, which provides rigid nephroscopes such as the VNL-24N2 model designed for percutaneous access and stone management. In the United States, Cook Medical, based in Bloomington, Indiana, supplies percutaneous nephroscopy kits including access sheaths compatible with standard nephroscopes for urological interventions. These companies collectively shape the supply chain, influencing everything from material selection to distribution networks.
Strategic Implications of Recent Developments
The recent activities of these market leaders offer valuable insights for strategic planning. Product launches at major congresses, such as the EAU Congress, serve as barometers for technological trends. The integration of imaging compatibility and the expansion of size variants suggest a market demand for versatility and superior visualization. Furthermore, regulatory updates, such as the EU MDR certification received by Richard Wolf, highlight the evolving compliance landscape that manufacturers must navigate to sustain operations in key regions.
Companies must also consider the implications of product lifecycle management. As older models are phased out or updated to meet new standards, procurement teams in healthcare facilities face decisions regarding capital expenditure and standardization. Our report provides detailed analysis on how these lifecycle events impact supply stability and cost structures for end-users.
Market Dynamics: Regulation, Reimbursement, and Material Standards
Understanding the percutaneous nephroscope market requires a granular appreciation of the external forces that govern commercial viability. Regulatory classification plays a pivotal role. Percutaneous nephroscopes are classified as Class II devices requiring 510(k) clearance under FDA 21 CFR 876.1500. This regulatory pathway influences time-to-market for new entrants and ensures that established players maintain rigorous quality control standards. Simultaneously, in Europe, the EU MDR requires Notified Body certification, such as from TÜV, for all percutaneous nephroscopes sold in the region. These regulatory hurdles create barriers to entry that protect incumbent revenue streams but also necessitate robust compliance teams for any organization seeking expansion.
Reimbursement policies directly affect procedure volumes and, by extension, instrument utilization. In the United States, CPT code 50081 reimburses percutaneous nephrostolithotomy procedures involving nephroscope use at an average Medicare rate of 4,200 dollars in facility fees. This reimbursement structure incentivizes hospitals to maximize the efficiency of each procedure. Consequently, there is a preference for reliable, high-performance instruments that minimize complications and reduce operating time. Our analysis examines how reimbursement trends in major healthcare systems shape purchasing patterns across different regions.
Worldwide Percutaneous Nephroscope Market
Material science and sterilization protocols also define the operational parameters of these devices. Medical-grade 316L stainless steel is used for nephroscope sheaths, often incorporating fiber-optic bundles for imaging according to ISO 7153-1 Standard. For reusable nephroscopes, sterilization is critical. These instruments must withstand steam sterilization at 132-134 degrees Celsius for 3 to 4 minutes per AAMI ST79 guidelines. The durability required to meet these sterilization cycles without degradation influences the lifecycle cost of the equipment. Hospitals must balance the initial purchase price against the longevity and maintenance requirements of reusable versus single-use or hybrid options.
Segmentation Synopsis: Type, Application, and Geography
While the aggregate market figures provide a high-level view, the true strategic value lies in understanding the segmentation drivers. The market is divided primarily by type and application. In terms of type, the market splits between Rigid Nephroscopes and Flexible Nephroscopes. Rigid models have traditionally held a significant share due to their robustness and cost-effectiveness in standard PCNL procedures. However, flexible options are gaining traction for accessing complex calyceal anatomy, driving a nuanced shift in procurement preferences.
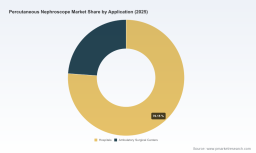
By application, the market serves Hospitals and Ambulatory Surgical Centers. Hospitals remain the dominant venue for these procedures, given the requirement for advanced sterilization facilities and immediate access to emergency care. However, the growth of Ambulatory Surgical Centers reflects a broader industry trend toward outpatient care settings. This shift creates specific demands for instruments that are easier to handle in streamlined environments and compatible with faster turnaround times.
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents distinct challenges and opportunities. Developed markets in North America and Europe are characterized by established reimbursement frameworks and high regulatory standards. In contrast, emerging markets in Asia Pacific and other regions offer volume growth potential driven by expanding healthcare infrastructure and increasing adoption of urological interventions. Our report provides a detailed breakdown of regional revenue contributions and growth trajectories without disclosing specific sub-regional percentages, ensuring that the full geographic intelligence remains exclusive to our clients.
Forecast Horizon: Strategic Outlook for 2026-2032
The forecast period from 2026 to 2032 is expected to be defined by technological refinement and market consolidation. With the market projected to grow from USD 575.56 Million in 2026 to USD 849.02 Million in 2032, the absolute dollar growth represents a significant expansion opportunity. However, capturing this growth requires more than simply riding the wave of increasing procedure volumes.
Strategic priorities for manufacturers and investors should include monitoring regulatory changes, particularly regarding EU MDR and FDA classifications, which may impact product roadmaps. Additionally, the integration of digital imaging capabilities and compatibility with advanced visualization systems will likely become a key differentiator. Companies that can demonstrate superior ergonomics, durability under sterilization conditions, and compatibility with existing hospital workflows will be better positioned to secure long-term contracts.
There is also the potential for niche innovation. While the market is concentrated, specific needs such as pediatric applications or specialized access sheaths may offer avenues for smaller players or diversified divisions of larger corporations. Understanding where these gaps exist requires the type of deep-dive analysis provided in our full report.
Digital Ureteroscopes Market
Conclusion: The Value of Comprehensive Intelligence
The Worldwide Percutaneous Nephroscope Market is a dynamic arena where clinical necessity, regulatory rigor, and competitive strategy intersect. The data suggests a healthy growth trajectory, but the path to success is nuanced. For executives, procurement leaders, and investors, relying on high-level summaries is insufficient. The granular details regarding segmentation splits, competitive share specifics, and regional revenue breakdowns are essential for making informed decisions.
This article serves as a preview of the depth and rigor found in PW Consulting's full market research report. We have outlined the historical context, the competitive players, the regulatory environment, and the macro-economic forecast. However, the specific numerical allocations across regions, the precise revenue shares of each application segment, and the detailed competitive benchmarking data are reserved for our subscribers. Accessing the complete report will provide the actionable intelligence needed to navigate this market with confidence.
As the industry moves toward 2032, those equipped with precise, verified, and strategically framed data will be best prepared to capitalize on the evolving opportunities in urological device manufacturing and deployment. We invite you to explore the full findings of our study to secure a comprehensive understanding of the Worldwide Percutaneous Nephroscope Market.
For detailed analysis of this topic, please visit the official page: Worldwide Percutaneous Nephroscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com