

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Liquid Cooling Couplings Market Hits $610.15M in 2025, Projected 18.52% CAGR to $2B by 2032

Navigating the Thermal Frontier: Strategic Imperatives in the Global Liquid Cooling Couplings Market
The infrastructure underpinning artificial intelligence and high-performance computing is undergoing a fundamental thermal transformation. As chip power densities escalate beyond the viable limits of air cooling, liquid cooling has transitioned from a niche consideration to a core architectural requirement for hyperscale data centers, AI clusters, and next-generation industrial systems. At the mechanical heart of these thermal loops lies a critical enabling component: the liquid cooling coupling. These quick disconnects, blind-mate interfaces, and non-spill connectors are no longer passive plumbing accessories. They are engineered subsystems that determine leakage risk, maintenance downtime, coolant compatibility, and ultimately the operational reliability of million-dollar compute deployments.
Our latest Worldwide Liquid Cooling Couplings Market study maps this rapidly consolidating landscape with a forward-looking lens calibrated for 2026 executive decision-making. The market has already demonstrated remarkable momentum, climbing from approximately 195.4 million USD in 2020 to an estimated 610.15 million USD in 2025. The trajectory does not plateau. Demand is projected to reach 715.52 million USD in 2026, accelerating toward a 2,004.38 million USD endpoint by 2032, underpinned by a compound annual growth rate of 18.52 percent. These figures are not abstract forecasts. They represent capital allocation signals, procurement strategy inflection points, and technology roadmap anchors for engineering leaders, supply chain directors, and corporate strategists who must act before the market repricing becomes irreversible.
From Historical Acceleration to 2026 Strategic Alignment
The growth narrative is rooted in a structural shift rather than a cyclical upturn. Rapid data center construction, sustained hyperscaler capital expenditure, and the operational necessity of direct-to-chip and immersion cooling architectures have transformed liquid cooling couplings into high-volume engineering components. The historical baseline from 2020 through 2025 reveals compounding adoption, with revenue moving from 230.56 million USD in 2021 to 274.98 million USD in 2022, then 344.5 million USD in 2023, and 465.21 million USD in 2024. Each interval reflects broader deployment cycles, but the acceleration intensifies as AI server rack power densities continuously push thermal design requirements upward.
For 2026 planning cycles, this historical momentum translates into three decision-critical realities. First, procurement teams must anticipate volume scaling that outpaces traditional catalog purchasing models, pushing organizations toward qualified supplier partnerships and long-lead capacity reservations. Second, engineering groups face mounting pressure to standardize on interconnect architectures that support hot-swap maintenance, minimize pressure drop, and prevent fluid loss during operator intervention. Third, sustainability and coolant compatibility mandates are tightening material selection criteria, making corrosion resistance, seal longevity, and fluid compatibility non-negotiable evaluation parameters. The market growth rate confirms that thermal management is no longer a facilities afterthought; it is a board-level operational priority that demands coordinated strategy across R&D, procurement, and infrastructure planning.
Where Capital, Compute, and Coolant Intersect: Core Market Drivers
The demand architecture is shaped by multiple concurrent forces. Rising power densities in AI servers and hyperscale data centers are driving adoption of non-spill and blind-mate liquid cooling couplings designed to support efficient thermal management and maintenance with minimal service interruption. Behind this operational push lies a standardization wave that is reshaping procurement expectations and supplier evaluations. The Open Compute Project released an updated UQD specification in late 2025, enforcing more rigorous testing protocols, tighter flow-performance limits, and standardized mechanical geometry to improve interoperability across quick disconnect interfaces. This specification evolution is more than a technical footnote. It directly influences qualification cycles, interoperability risk, and the speed at which data center operators can integrate new cooling loops without custom validation overhead.
Material engineering is simultaneously reinforcing demand durability. Liquid cooling couplings commonly utilize 303 or 304 stainless steel bodies with EPDM seals to achieve broad coolant compatibility and corrosion resistance in data center environments. As data center construction and associated cooling infrastructure sustain demand for high-grade stainless steel into 2026, structural and fluid-handling components are increasingly tied to the same material supply dynamics as the couplings themselves. The practical implication for strategists is clear: component sourcing is becoming inseparable from broader industrial material availability, tolerance windows, and lead-time planning.
The operational consequences are equally important. Hot-swap capability reduces mean time to repair, blind-mate designs reduce accidental spill risk during tray insertion or removal, and non-spill architectures protect sensitive electronics and facility flooring during routine service. These are not fringe benefits; they are total cost of ownership drivers that increasingly determine which coupling platforms win in competitive data center deployments. Decision-makers evaluating cooling ecosystems in 2026 must therefore evaluate couplings not simply by connection form factor, but by their contribution to uptime, maintenance cadence, and system-level thermal reliability.
Competitive Architecture: The Players Defining the Next Phase
Market leadership in liquid cooling couplings is being shaped by organizations that combine precision fluid-handling engineering with active participation in interoperability standards. The competitive field is concentrated, with the top three players accounting for 42.5 percent of market share and the top five reaching 58.75 percent. This concentration signals a market where scale, specification alignment, and application-specific engineering create meaningful barriers for late entrants, while rewarding incumbents who can deliver standardized, validated, and service-ready coupling portfolios.
Couplings Market
Stäubli International AG continues to position itself at the intersection of fluid connection hardware and open-standard development. Its portfolio spans universal quick disconnects, blind-mate couplings, and compact connectors supporting liquid cooling in AI data centers and IT infrastructure, alongside active contributions to OCP standards for non-spill, leak-free thermal management solutions. In late 2025, the company introduced a Mini-QD connector optimized for next-generation optical pluggable modules in liquid-cooled AI data centers and contributed to a UQD specification update with tighter testing, geometry, and interoperability requirements. This dual focus on product advancement and standards alignment illustrates the strategic posture now expected from market leaders.
Colder Products Company brings a broad material and configuration range to the market, with its Everis series covering liquid cooling quick disconnects including LQ, BLQ blind-mate, and UQD/UQDB variants in brass, aluminum, stainless steel, and polymer. These solutions are engineered for high-performance computing, data centers, and cold plate applications, emphasizing non-spill, dripless performance. The material breadth is strategically significant: it gives system architects flexibility to match coupling bodies and seals to specific coolant chemistries, pressure regimes, and weight or cost constraints without abandoning a consistent interface philosophy.
Parker Hannifin Corp has deepened its focus on data center thermal management with non-spill quick disconnects and UQD/UQDB couplings optimized for server and supercomputer liquid cooling. Its flat-face designs target high-reliability thermal management, and in mid-2025 the company advanced UQD and blind-mate couplings aligned with OCP specifications, including compact cartridge solutions. The emphasis on compact implementation and specification alignment reflects a market reality: data center floor space, service access, and standard conformance are as decisive as raw flow performance.
Danfoss, through its thermal management lineup, manufactures quick disconnects including UQD variants, UQDB blind-mate couplings, FD83 full-flow series, and MQD/MQDB offerings, with 100 percent helium-leak testing and compatibility with data center coolant loops. Its participation in regional data center events highlights the increasing importance of localized technical engagement for operators deploying liquid cooling across diverse geographies. CEJN AB contributes hand-mate UQD platforms, UQDB variants, and blind-mate quick connect couplings for CDU, direct liquid cooling, and immersion applications. Its emphasis on high flow, minimal pressure drop, and hot-swap capability aligns directly with the operational priorities of high-density cooling deployments.
Additional participants broaden the application envelope. Gates Corporation focuses on full-flow quick disconnect couplings engineered for direct-to-chip liquid cooling loops in data centers, with an emphasis on durability and compatibility. The Specialty Mfg. Co. produces SafeWay thermal management couplings and custom liquid cooling quick disconnects for data center infrastructure and ORv3 blind-mate applications, addressing niche but high-value integration scenarios. Amphenol Industrial Operations provides a wide connector portfolio spanning UQD, UQDB Rev 2.0, BMQC, LQC, MQD, and SHQD series for server trays, CDUs, and high-flow architectures in AI data centers and EV applications, underscoring the cross-application relevance of standardized fluid interconnects.
For strategists, this competitive map reveals a dual imperative. On one side, specification-aligned platforms reduce integration risk and accelerate deployment. On the other, material versatility, leak-test rigor, and serviceability features increasingly differentiate suppliers in competitive bids. Companies expecting to scale liquid cooling deployments in 2026 should evaluate partners against this combined lens rather than treating couplings as commoditized consumables.
What the Research Delivers: Decision-Ready Intelligence for 2026
This market study is constructed to convert market complexity into actionable planning inputs. It traces the revenue path from the 2020 baseline through the 2025 current year and extends the forecast horizon to 2032, giving leadership teams a structured view of growth inflection points and capacity-planning horizons. Beyond macro sizing, the analysis dissects the market across type, application, and regional dimensions so that procurement and engineering leaders can identify where demand intensity is concentrating and how deployment contexts differ in specification requirements and service expectations.
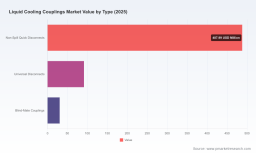
The segmentation assessment provides a practical framework for understanding how non-spill quick disconnects, universal disconnects, and blind-mate couplings occupy distinct roles within cooling architectures. Each category addresses different operational priorities, from leak prevention during service events to repeated mating cycles in modular infrastructure. The application perspective connects coupling demand to end-use contexts such as data centers and high-performance computing, electric vehicle infrastructure, industrial and manufacturing environments, and medical equipment. This application-level structure helps decision-makers map coupling requirements to deployment realities rather than evaluating components in isolation.
Worldwide Liquid Cooling Couplings Market
The regional view enables supply chain and market-entry strategists to understand where demand activity is clustering and what localization, certification, or partnership considerations may shape go-to-market execution. The concentration data adds another layer of strategic clarity by quantifying how consolidated the supplier base is, helping organizations assess negotiation leverage, supply continuity risk, and the realistic pace at which new specification-aligned entrants can reshape availability.
Just as important, the research integrates recent corporate developments and industry context that directly affect procurement timing and technical evaluation. These include product launches, specification contributions, trade show engagements, and materials and standards updates that collectively shape the 2026 buying environment. The report is designed for teams that need to align engineering requirements, volume planning, and supplier qualification with a market that is moving faster than traditional component evaluation cycles.
Strategic Actions for 2026: Procurement, Engineering, and Competitive Positioning
Leaders entering 2026 should treat liquid cooling couplings as a strategic interface category rather than a commodity line item. Several actions can convert this market momentum into durable advantage. First, standardize early on specification-aligned coupling architectures to reduce validation overhead and improve interoperability across Cooling Distribution Units, server trays, and direct-liquid loops. Interoperability alignment shortens integration cycles and reduces the risk of stranded assets when cooling architectures evolve.
Second, embed material and seal compatibility into the initial design review instead of deferring it to procurement. Coolant chemistry, corrosion resistance, and seal longevity directly influence maintenance frequency and failure modes. As stainless steel and engineered elastomers remain tied to broader industrial demand, advance material qualification can protect deployment timelines from supply-side volatility.
Third, evaluate suppliers on the combined weight of specification participation, leak-test rigor, hot-swap performance, and application-specific engineering support. In a market where the top five players already command a majority share, partnerships with suppliers that can demonstrate standards engagement and application credibility often outperform price-only comparisons over multi-year deployment horizons.
Fourth, build procurement lead times around volume scaling expectations. The growth path from 715.52 million USD in 2026 toward the 2032 forecast indicates sustained demand expansion rather than a short-term spike. Organizations that secure qualified supply, reserve capacity, and synchronize coupling selection with broader cooling infrastructure planning will be better positioned to avoid bottlenecks as deployment programs accelerate.
Finally, use the market structure to inform competitive positioning. In data center densification, EV thermal infrastructure, and industrial cooling modernization, the ability to specify reliable, standardized, and service-ready couplings contributes to total system credibility. Companies that align their thermal strategies with the coupling ecosystem's evolution can improve uptime narratives, reduce integration risk, and strengthen their posture in competitive infrastructure bids.
Conclusion: Convert Thermal Complexity into Strategic Advantage
The Worldwide Liquid Cooling Couplings Market is expanding at a pace that rewards foresight. Growth from 195.4 million USD in 2020 to an estimated 610.15 million USD in 2025, followed by a projected climb to 2,004.38 million USD by 2032, reflects more than component demand. It reflects a structural transformation in how high-density computing, advanced manufacturing, and electrified infrastructure manage heat. In this environment, couplings are enabling hardware, specification-sensitive components, and long-term operational risk managers all at once.
For enterprises operating in 2026, the decisive question is whether thermal infrastructure planning keeps pace with deployment ambition. The organizations that succeed will be those that integrate coupling strategy into engineering standards, procurement readiness, and supplier evaluation frameworks before market momentum forces reactive decisions. Our full research study provides the detailed segmentation, competitive mapping, application context, and forward forecast needed to make those decisions with confidence. Access the complete report to obtain the granular intelligence required to translate this market trajectory into procurement precision, engineering alignment, and durable strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Cooling Couplings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com