

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Emergency Road Service Market Hits $28.5B in 2025, Poised for 5.2% CAGR Through 2032

Navigating the Road Ahead: Strategic Imperatives in the Global Emergency Road Service Market
The emergency road service sector stands at a critical inflection point in 2026. As vehicle populations expand, testing protocols mature, and operational frameworks tighten, organizations that rely on roadside assistance, distribution networks, and insurance integration must look beyond headline growth figures and understand the structural forces reshaping how breakdowns are predicted, dispatched, and resolved. Our latest worldwide market research was built to serve that exact need: a decision-grade intelligence platform that translates historical momentum into actionable forward guidance for operators, investors, fleet managers, and policy stakeholders.
This overview outlines why the study matters for 2026 planning cycles, what analytical depth it delivers, and how competitive and regulatory signals are converging to redefine service economics. The goal is not to overwhelm with data points, but to equip senior teams with the right questions, the right benchmarks, and the right strategic framing before capital, partnerships, or technology investments are committed.
Why 2026 Demands a Fresh Analytical Lens
The emergency road service market has demonstrated steady expansion over the past half-decade, moving from a 22.15 billion USD base in 2020 to an estimated 28.5 billion USD in 2025. That trajectory reflects more than incremental demand growth. It signals shifting customer expectations, deeper insurer-provider integration, and an expanding service menu that now spans conventional towing, battery support, fuel delivery, and lockout or tire replacement assistance.
Looking ahead, the forecast window through 2032 maps a continued upward path, with the market projected to approach 40.64 billion USD by the end of the period. The implied compound annual growth rate of 5.2 percent may appear measured at first glance, but in a mature, operationally intensive sector, that pace carries meaningful consequences for capacity planning, labor strategy, pricing architecture, and technology adoption. Growth at this level is not automatically profitable; it must be earned through dispatch efficiency, network reliability, reimbursement optimization, and disciplined cost control.
For 2026 decision-makers, the strategic question is no longer whether demand will persist. It is how growth will be distributed across service categories, provider models, and geographies, and which operational levers will separate resilient performers from squeezed middle suppliers. Our research is designed to answer those questions without forcing organizations into generic industry narratives.
What the Research Delivers: From Macro Signals to Execution Detail
A strong market study must do more than report numbers. It must create a usable map of the operational terrain. This report was structured around that principle, combining longitudinal sizing with segmented analysis, provider and buyer dynamics, and competitive profiling that can be directly referenced in planning meetings, investment memos, and service-design workshops.
Worldwide Emergency Road Service Market
At the core of the study is a multi-year historical view that anchors the forecast in observed market behavior rather than assumptions alone. That historical foundation is then extended through a forward model that accounts for demand normalization, service adoption patterns, and the evolving economics of roadside response. Importantly, the analysis does not treat the market as a single block. It breaks the landscape into the dimensions that actually shape go-to-market choices and operating strategy.
Readers will find structured examination across:
- Service-type demand patterns, including the relative scale and trajectory of towing, battery support, fuel delivery, and lockout or tire replacement activity
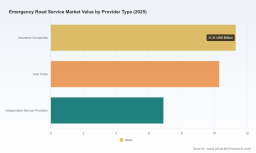
- Provider-side competitive posture, spanning insurance-affiliated models, automobile club ecosystems, and independent service networks
- Regional demand distribution and the operational implications of mature versus emerging market conditions
- Concentration dynamics that reveal how much of the market is shared among leading players and where fragmentation still creates entry or consolidation opportunities
Beyond segmentation, the study connects market structure to real operating pressures. Labor availability and wage inflation influence dispatch economics. Regulatory requirements shape tracking, data handling, and compliance costs. Reimbursement patterns affect provider willingness to serve certain customer segments and the profitability of claim-adjacent services. These are not side issues; they are central to understanding where margin will come from in 2026 and beyond.
The report also includes practical frameworks for evaluating service-level commitments, network coverage, technology readiness, and partnership design. Whether an organization is assessing a new roadside offering, expanding into a new region, renegotiating insurer contracts, or evaluating acquisition targets, the analysis is intended to reduce reliance on anecdote and increase confidence in structured comparison.
Competitive Architecture: Who Shapes the Market and How
The emergency road service landscape is defined by a mix of large membership organizations, insurer-linked service programs, technology-forward dispatch platforms, and specialized independent operators. Each group competes on different axes: membership reach, insurance integration, dispatch efficiency, geographic coverage, and service reliability. Understanding how these players position themselves is essential for any organization trying to anticipate channel behavior, pricing pressure, or partnership opportunities.
In North America, several established names anchor the customer-facing and B2B layers of the market. AAA remains a dominant reference point for membership-based roadside assistance, with a broad service portfolio and enormous member base across the region. Allstate Motor Club illustrates the insurer-integrated model, where roadside support is packaged alongside insurance products and delivered through nationwide service relationships. On the B2B side, Agero functions as a connective platform linking insurers and automakers to service networks, handling a substantial volume of annual dispatch requests across towing, winching, and fuel delivery. Honest Networks and Ursus Roadside Service represent the operational backbone that many insurers and commercial fleets rely on, maintaining scalable provider networks for towing, tire repair, battery service, and extrication.
In Europe, the competitive structure leans heavily on automobile club ecosystems and established recovery organizations. RAC illustrates a member-centric model with digital service request capabilities and wide coverage across the UK. ADAC operates at a scale that makes it one of the most influential roadside and vehicle recovery organizations in Europe, with a large member base and cross-border relevance. TCS demonstrates how national clubs extend services beyond basic recovery into broader European mobility support, including repatriation and mobile workshop capabilities.
What makes this competitive set especially important in 2026 is not simply scale, but the accelerating divergence in operational models. Some organizations are deepening insurance integration. Others are investing in digital member experiences and service discovery tools. Still others are building dispatch infrastructure that can route work more efficiently across dispersed provider networks. These choices are creating differentiated cost structures and service-level profiles, which means competitive benchmarking must go beyond membership counts or brand recognition and examine how service fulfillment is actually engineered.
24 Hour Emergency Roadside Assistance Market
Recent Moves That Signal the Market’s Direction
The most informative indicators in a sector like this are often not static market shares, but operational updates that reveal where incumbents are placing their bets. Recent developments across the competitive set point to three recurring themes: technology-enabled dispatch, electric vehicle readiness, and faster, more targeted response in hard-to-reach situations.
One notable shift comes from the dispatch layer. Agero expanded its partnership with GEICO to enhance roadside dispatch using AI-driven predictive routing, with the stated aim of improving response times. This kind of integration matters because it shows how routing intelligence is becoming a source of competitive advantage, not just an internal efficiency tool. Faster and more accurate dispatch can reduce idle time, improve member experience, and help providers manage the same workload with tighter operational margins.
On the member-facing side, AAA upgraded its mobile application to include integrated EV charging locator and battery health diagnostics for roadside service. That update reflects a broader reality: as electric vehicle adoption grows, roadside assistance must evolve from mechanical recovery toward battery-related support, charging access, and diagnostic capability. Service providers that treat EV readiness as an afterthought risk losing relevance in a segment that will increasingly define roadside demand.
In Europe, ADAC introduced a drone-assisted breakdown scouting pilot in rural Germany, aimed at accelerating response for remote emergency calls. The initiative is a good example of how established organizations are experimenting with tools that improve situational awareness before a service vehicle arrives. In rural or low-visibility scenarios, faster assessment can reduce unnecessary travel, improve resource allocation, and strengthen the perceived reliability of the service promise.
Taken together, these developments indicate that the market’s next phase of competition will be shaped by information flow, routing quality, and service adaptability, not merely by the number of trucks or service locations a company can claim.
Operating Pressures Redefining Margin and Execution
Market growth alone does not guarantee sustainable profitability. Several structural dynamics are reshaping the cost and compliance environment for roadside service providers, insurers, and fleet operators. Any 2026 strategy that ignores these pressures will likely underestimate the true difficulty of scaling service quality while protecting margin.
Labor cost is one of the most immediate pressures. In the United States, the average hourly wage for tow truck operators rose 5.2 percent to 24.50 USD in 2025, driven in part by driver shortages. This matters because roadside assistance is labor-intensive and spatially dispersed. Wage inflation affects not only direct operating cost, but also retention, scheduling flexibility, and the economics of lower-density service areas. Organizations that rely on manual dispatch and fragmented provider networks may find it harder to maintain service consistency as labor markets tighten.
Regulatory change is adding another layer of complexity. In the European Union, revised road transport directives require real-time GPS tracking for all roadside assistance vehicles, effective 2025. This mandate improves transparency and dispatch accountability, but it also raises the bar for operational compliance and data integration. Providers must ensure their fleets, dispatch systems, and reporting processes can support continuous location tracking without introducing new friction into service execution.
Reimbursement patterns are also shifting the incentive structure behind roadside claims. US insurers reimbursed 92 percent of roadside claims in 2024, with an average value of 250 USD per incident, up from 220 USD in 2023. Higher reimbursement rates can improve provider viability, but they can also intensify scrutiny on claim validity, service necessity, and cost containment. For providers and insurers alike, the operational challenge is to align service delivery with reimbursement logic while avoiding inefficiencies that erode trust or margin.
Data compliance is becoming increasingly central as well. Updated guidance from European data protection authorities requires roadside service providers to anonymize location data within 24 hours after a service call. In practice, this means that digital operations, mobile platforms, and dispatch analytics must be designed with privacy compliance embedded into the workflow, not treated as a separate legal afterthought. For organizations building data-rich dispatch or member-facing tools, this constraint influences architecture, storage, and retention policies directly.
These pressures do not cancel out growth; they discipline it. The organizations that will benefit most in 2026 are those that treat labor, regulatory, reimbursement, and data-compliance dynamics as integral parts of the business model rather than external noise.
Strategic Takeaways for 2026 Decision-Making
The emergency road service market is expanding, but expansion is not uniform, and the winners will be defined by how effectively they convert demand into efficient, compliant, and differentiated service delivery. For senior teams planning around 2026, several strategic priorities stand out.
First, service portfolios must be assessed for future demand mix, not just current volume. Towing remains a central part of the landscape, but battery support, fuel delivery, and lockout or tire replacement activity each carry different operational requirements and margin profiles. Understanding where demand is tightening, where it is expanding, and where service thresholds are changing is essential for capacity planning.
Second, provider and partnership strategy should be evaluated against dispatch efficiency and network reliability. Whether an organization operates through insurer relationships, automobile club membership, or independent provider networks, the quality of routing, coverage, and response consistency will increasingly determine market position.
Third, technology investment should be viewed as a service-level differentiator. Predictive dispatch, EV-aware member tools, remote assessment capabilities, and compliant data handling are no longer optional enhancements in every context; they are becoming baseline expectations in competitive segments.
Fourth, regional strategy should account for regulatory divergence and labor environment differences. A model that works in one market may not translate directly to another if compliance obligations, workforce availability, or reimbursement practices differ materially.
Finally, competitive intelligence must be updated continuously. Market structure is being reshaped by partnerships, product updates, pilot programs, and operational experiments that may not immediately show up in headline sizing but can influence service economics over the next several years.
Move From Direction to Detail
This article has outlined the strategic context surrounding the worldwide emergency road service market and explained why a structured, forward-looking study is valuable for 2026 planning. The macro trajectory is clear: the market has grown steadily from 2020 through 2025 and is projected to continue expanding toward 2032, with a 5.2 percent CAGR shaping the pace of opportunity. Yet the real decisions facing organizations depend on segmentation behavior, competitive positioning, operating costs, regulatory requirements, and technology-driven service evolution.
Those details are where the full report adds its greatest value. It provides the segmentation breakdown, provider analysis, regional comparisons, concentration insight, and competitive profiles needed to move from general market awareness to specific strategy design. For teams evaluating expansion, partnership, investment, or operational redesign, the complete study offers the structured intelligence required to reduce uncertainty and support confident decisions.
To access the full market research, including the complete segmentation landscape, company profiles, and forward forecast framework, visit the source page for the Worldwide Emergency Road Service Market study and obtain the full intelligence package for 2026 planning.
For detailed analysis of this topic, please visit the official page: Worldwide Emergency Road Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com