

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cylindrical Clutch Market to Hit $1.77B by 2032 at 5.14% CAGR

Global Cylindrical Clutch Market 2026–2032: Strategic Imperatives for Industry Leaders
The worldwide cylindrical clutch market stands at a critical inflection point. As industrial automation accelerates, power transmission systems face mounting demands for reliability, compact form factors, and continuous high-speed operation. For executives, procurement directors, and engineering leaders navigating 2026 and beyond, understanding the trajectory of this specialized component category is no longer optional. Our newly released Worldwide Cylindrical Clutch Market research delivers a comprehensive, data-driven blueprint designed specifically to support high-stakes strategic decisions. This overview outlines the macro trajectory, competitive intensity, raw material headwinds, and the actionable intelligence embedded in the full report.
Market Trajectory: From Base-Year Momentum to a Decade of Steady Expansion
The market has demonstrated consistent resilience and structural growth over the past half-decade. Starting from a base of approximately 985.4 million USD in 2020, revenue expanded steadily through successive years, reaching 1,245.8 million USD by 2025. The forecast horizon extends to 2032, projecting a compound annual growth rate of 5.14 percent across the analysis window. By the close of the forecast period, the market is expected to surpass 1.77 billion USD, reflecting sustained capital allocation into heavy machinery, material handling systems, and next-generation automation platforms.
Worldwide Cylindrical Clutch Market
This growth is not merely a function of nominal expansion. It reflects deeper structural shifts in how industrial and mobility sectors approach power transmission. Cylindrical roller and sprag designs continue to gain favor in applications requiring dependable unidirectional control, overrunning protection, and backstopping under continuous duty cycles. As original equipment manufacturers tighten performance specifications and service intervals lengthen, the demand for engineered clutch solutions with predictable engagement characteristics and low maintenance footprints is accelerating. The report quantifies these dynamics across a full historical and forecast timeline, enabling stakeholders to model capacity planning, inventory positioning, and capital expenditure with greater precision.
Segmentation Architecture: Where Value Concentration Actually Lies
Beneath the headline figures, the market reveals distinct concentration patterns that merit careful strategic attention. The product landscape is anchored by three primary design families. Roller type cylindrical clutches command the largest share of industry revenue, reflecting their widespread deployment in continuous-duty industrial environments. Sprag type designs follow as a meaningful second pillar, prized for their simplicity, compact packaging, and reliability in overrunning and backstop roles. Wedge type cylindrical clutches occupy a smaller but strategically important niche, often selected for specific torque and engagement profiles where alternative geometries do not suffice.
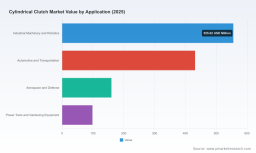
Application-wise, the market distributes across four core domains. Industrial machinery and robotics represent the largest revenue pool, driven by conveyor systems, material handling equipment, and automated production lines that demand fail-safe rotational control. Automotive and transportation constitutes the second major pillar, encompassing heavy-duty drivetrain components and specialized transmission systems. Aerospace and defense forms a high-value segment where qualification rigor, weight efficiency, and extreme-environment reliability justify premium engineering investment. Power tools and gardening equipment round out the application mix, serving OEM platforms that require cost-effective, high-cycle clutch mechanisms for consumer and professional-grade equipment.
Regional distribution further shapes competitive strategy. Asia Pacific accounts for the largest revenue concentration, reflecting dense manufacturing ecosystems, expanding infrastructure projects, and growing domestic demand for industrial automation. North America and Europe follow as mature but still growing markets, where replacement cycles, upgrade programs, and high-specification industrial projects sustain steady demand. Latin America and the Middle East and Africa represent smaller but strategically relevant corridors, often tied to mining, energy recovery, and heavy equipment operations. The full report provides granular regional and application-level breakdowns, allowing readers to calibrate go-to-market priorities without relying on broad estimates.
Competitive Landscape: Incumbents, Specialization, and the Battle for Engineering Trust
The cylindrical clutch segment is characterized by a moderately concentrated competitive field. The top three players collectively hold approximately 38.45 percent of market revenue, while the top five extend that share to 52.3 percent. This structure indicates a market where scale and distribution matter, but engineering differentiation, application-specific expertise, and long-term service relationships remain decisive.
Several established manufacturers anchor the landscape. Marland Clutch, based in Warren, Michigan, specializes in completely enclosed cylindrical roller clutches engineered for continuous high-speed operation in demanding industrial settings such as cement kilns, fans, pumps, and energy recovery systems. Its inclined cam plane design emphasizes reliable backstopping and overrunning performance under sustained load. Formsprag Clutch, operating under Regal Rexnord and Altra Motion, stands as a leading manufacturer of overrunning, backstopping, and bi-directional sprag and ramp-and-roller clutches. Its cylindrical roller designs serve aerospace, mining, steel, and heavy machinery sectors where power transmission integrity is non-negotiable.
Tsubaki, with its U.S. operations headquartered in Wheeling, Illinois, offers cam clutches and BS/BS-F series backstop cam clutches that utilize cam and roller mechanisms for unidirectional rotation prevention in conveyors and industrial equipment. WPT Power Corporation, based in Wichita Falls, Texas, manufactures heavy-duty pneumatic, hydraulic, and mechanical industrial clutches for power transmission in oil and gas, mining, and marine applications, with high-torque cylindrical-style engagement designs tailored for extreme-duty environments. Lowell Corporation produces one-way roller clutches and ratchet arm assemblies for OEM and industrial use in power transmission and material handling. Mach III Clutch, Inc. supplies industrial clutches including designs suitable for cylindrical engagement in automation and power transmission. Tolomatic, Inc., headquartered in Hamel, Minnesota, manufactures industrial cone and power transmission clutches, alongside related cylindrical-style components for automation in aerospace, agriculture, and utilities.
Recent corporate activity underscores how actively these players are refining their value propositions. In August 2025, Marland Clutch released an updated CECON clutches product catalog, detailing completely enclosed cylindrical roller clutches for continuous operation, including size selection guidance, service factor recommendations, and high-speed application parameters. In February 2026, WPT Power Corporation published an application note focused on tough products for asphalt milling, highlighting updated clutch pack designs with thin center plates to achieve compact, high-torque cylindrical-style engagement in heavy-duty milling machines. These moves signal a broader industry pattern: manufacturers are investing in application-specific documentation, compact packaging, and torque-density improvements to capture share in niche but high-value deployments.
Macro and Input Dynamics: Steel, Trade Tensions, and Procurement Realities
Strategic planning for cylindrical clutch markets cannot be isolated from the broader input cost and geopolitical environment. Global steel demand is projected to stabilize at roughly 1.75 billion tonnes in 2025, followed by a modest 1.3 percent rebound to approximately 1.773 billion tonnes in 2026. This trajectory is underpinned by continued infrastructure investment, yet it remains tempered by trade tensions that are Weighing on machinery-intensive export economies. For cylindrical clutch producers and buyers alike, steel availability and price stability directly influence bill-of-materials planning, lead-time predictability, and final assembly competitiveness.
In the near term, US Midwest hot-rolled coil steel prices have traded in the range of 980 to 1,060 dollars per short ton in early 2026. Procurement teams have indicated expectations of flat to slightly rising prices over subsequent weeks, with energy and freight cost pressures contributing to margin vigilance. These conditions favor companies that can secure resilient supply agreements, optimize material utilization in clutch housings and roller assemblies, and communicate transparent lead-time frameworks to downstream customers. The report incorporates these input dynamics into its forward-looking analysis, helping readers stress-test sourcing strategies against plausible price and availability scenarios.
Trade policy uncertainty adds another layer of complexity. Escalating trade tensions and geopolitical risks are negatively impacting steel demand in economies reliant on exporting steel-intensive goods such as industrial machinery and automotive components. For cylindrical clutch stakeholders, this environment necessitates scenario planning around tariff exposure, alternative sourcing corridors, and demand volatility in export-sensitive end markets. The full research delivers structured assessments of these dynamics, enabling leadership teams to align procurement, pricing, and market-entry decisions with realistic macroeconomic pathways.
Automotive Clutch Market
What the Full Report Delivers: Operational Intelligence for 2026 Decision-Making
The Worldwide Cylindrical Clutch Market research is built for practitioners who need more than directional commentary. It translates macro trends into decision-ready frameworks across product strategy, capacity planning, supplier evaluation, and regional prioritization. The report includes detailed segmentation analysis across type, application, and region, allowing readers to isolate the highest-opportunity pockets without relying on aggregate averages. Historical data from 2020 through 2025 establishes a rigorous baseline, while the 2026–2032 forecast window supports multi-year planning for product roadmaps, inventory positioning, and capital allocation.
Competitive profiling extends beyond basic company summaries. Each key player is evaluated through the lens of product architecture, application focus, recent catalog and product updates, and implied strategic direction. This approach helps buyers benchmark incumbent capabilities, helps manufacturers identify whitespace in under-served applications, and helps investors gauge where engineering differentiation is translating into durable revenue share. The market concentration metrics are contextualized within the segmentation data, providing a clearer picture of where scale advantages exist and where specialized players can compete effectively.
The report also integrates raw material and macro trend analysis into its forward view, linking steel demand stabilization, hot-rolled coil pricing behavior, and trade tension impacts to procurement and margin planning. By connecting input cost trajectories to segment-level demand patterns, the research equips teams to evaluate risk exposure, time sourcing commitments, and align product specifications with realistic cost pathways. This integrative perspective is especially valuable for organizations managing complex bill-of-materials or serving multiple geographies with varying trade and logistics conditions.
Strategic Takeaways: Positioning for the 2026–2032 Cycle
As the cylindrical clutch market moves through its next growth phase, several strategic priorities emerge. First, application-specific engineering will increasingly differentiate suppliers. Buyers in industrial machinery, robotics, and heavy equipment are looking for clutches that balance compactness, torque capacity, and continuous-duty reliability. Companies that can articulate clear service factor guidance, high-speed application parameters, and compact-packaging innovations will be better positioned to capture premium share. Second, procurement and sourcing strategies must account for input cost volatility and trade-related uncertainty. Locking in resilient supply arrangements, diversifying where feasible, and aligning product design with material efficiency can protect margins in an environment of flat-to-rising steel prices and freight pressure.
Third, regional focus should be calibrated to end-use density and replacement dynamics. Mature markets offer steady demand from upgrade and replacement cycles, while higher-growth regions present volume opportunities tied to infrastructure, automation expansion, and heavy equipment deployment. Understanding which applications and regions compound fastest enables more efficient resource allocation and sharper go-to-market messaging. Finally, competitive intelligence should be treated as an ongoing input rather than a one-time exercise. Recent catalog releases, application notes, and design refinements from leading manufacturers indicate that the competitive frontier is shifting toward documentation clarity, torque-density improvements, and application-tailored solutions. Organizations that monitor these signals systematically will be better prepared to anticipate share shifts and adjust positioning accordingly.
Access the Complete Intelligence Package
The insights summarized here represent a strategic preview of a much deeper research asset. The full Worldwide Cylindrical Clutch Market report contains detailed segmentation revenue breakdowns, regional and application-level growth trajectories, company-specific capability assessments, recent development timelines, and integrated macro and raw material analysis designed to support executive deliberation, procurement planning, and product strategy formulation. For decision-makers who need precise figures, scenario-ready segmentation, and actionable competitive context, the complete report provides the granularity required to move from directional awareness to execution-ready planning.
Explore the full dataset, segmentation matrices, and competitive profiles to align your 2026 strategy with the market's most current trajectory and to secure the intelligence needed for confident, evidence-based decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Cylindrical Clutch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com