

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
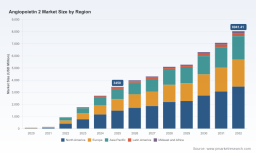
PW Consulting: Angiopoietin 2 Market to Hit $8,041.41M by 2032, 12.85% CAGR

The Angiopoietin 2 Market: Strategic Imperatives and Growth Trajectories Through 2032
The therapeutic and diagnostic landscape surrounding Angiopoietin 2 is undergoing a structural transformation that demands immediate executive attention. Over the past half-decade, the market has transitioned from a niche research domain into a commercially significant segment driven by dual-pathway vascular targeting, expanding retinal indications, and a maturing pipeline of bispecific modalities. For corporate strategists, portfolio managers, and investment committees, the current inflection point represents both a valuation opportunity and a competitive risk. Understanding where capital is flowing, which mechanisms are gaining clinical traction, and how regulatory pathways are shifting will define market positioning through the end of the decade.
This analysis draws from comprehensive forecasting models that map historical consolidation against forward-looking demand signals. The data reveals a sector that has moved beyond experimental validation into commercialization scaling, with clear implications for drug development, diagnostic manufacturing, reimbursement strategy, and competitive positioning. What follows is a disciplined examination of the forces shaping the Angiopoietin 2 ecosystem, designed to equip decision-makers with the structural clarity required to allocate resources, time market entry, and anticipate displacement dynamics.
Macro Trajectory: From Validation to Commercial Scaling
Historical revenue patterns across the 2020 to 2025 window illustrate a market that has accelerated decisively once clinical and commercial proof points aligned. Early baseline activity gave way to a pronounced expansion phase as dual-inhibition strategies demonstrated differentiated efficacy in retinal vascular disease, while parallel diagnostic demand matured around standardized quantification workflows. By the 2025 base year, the market had reached a consolidated valuation of approximately 3,450 million USD, reflecting both therapeutic uptake and robust research-grade tooling adoption.
Forward projections indicate sustained momentum rather than a transient peak. The forecast horizon through 2032 models a compound annual growth rate of 12.85 percent, culminating in a market valuation that meaningfully expands the commercial ceiling for both branded therapeutics and supporting research infrastructure. This trajectory is not uniformly distributed across time; it is shaped by label expansions, dosing flexibility adoption, regional access dynamics, and the maturation of next-generation molecular formats. For executives, the critical implication is that growth is structurally embedded in the mechanism of action rather than dependent on isolated product cycles.
The growth curve also reflects a market that is consolidating around higher-value interventions. Revenue concentration signals a landscape where a limited set of commercially advanced assets and diagnostic platforms command disproportionate share, reinforcing the need for precise competitive mapping. Organizations entering or expanding within this space must account for both the velocity of adoption and the barrier created by established dual-pathway franchises.
Segmentation Architecture: Where Value Is Concentrated
The Angiopoietin 2 market does not grow as a monolith. Its expansion is distributed across therapeutic indications, molecular formats, and geographic demand centers, each with distinct adoption drivers and commercialization requirements. Understanding these structural layers is essential for product planning, pricing strategy, and go-to-market sequencing.
Therapeutic Indications: Retinal Disease Dominance and Adjacent Expansion
Retinal vascular disease remains the principal demand engine. Neovascular AMD and diabetic macular edema together anchor the majority of therapeutic revenue, driven by high prevalence, recurrent treatment cycles, and the clinical advantage of addressing vascular instability through dual-pathway modulation. The revenue distribution across these indications underscores a market where retinal specialists are increasingly comfortable with flexible dosing paradigms that reduce treatment burden while preserving efficacy.
Beyond retinal disease, oncology and other inflammatory disorders represent a strategically important but structurally distinct segment. Here, the value proposition shifts from chronic vascular stabilization to tumor microenvironment modulation and combination immunotherapy sequencing. The commercial opportunity in this adjacent segment is contingent on clinical differentiation, biomarker enrichment, and reimbursement adjudication for combination regimens. For developers, this indicates a bifurcated strategy: optimize retinal uptake through dosing and access, while building oncology evidence through targeted trial design and partnership structures.
Drug Class Dynamics: The Bispecific Ascendancy
Molecular format is a defining axis of market value. Bispecific antibodies have emerged as the dominant commercial class, reflecting their ability to simultaneously neutralize VEGF-A and Angiopoietin 2 within a single molecular architecture. This design directly addresses the clinical rationale of combined vascular pathway inhibition, supporting both efficacy and dosing flexibility in practice. The revenue weighting toward bispecific formats signals that the market is rewarding mechanism convergence rather than incremental monotherapy optimization.
Monoclonal antibodies and small molecule inhibitors occupy more specialized positions within the landscape. Monoclonal approaches remain relevant where established manufacturing, regulatory familiarity, or combination logic favor single-target precision. Small molecule inhibitors serve differentiated niches, particularly in settings where oral administration, cost structure, or specific biomarker profiles create selective demand. The stratification across drug classes indicates that future competition will hinge not merely on target engagement but on format-level differentiation in pharmacokinetics, dosing convenience, manufacturing economics, and clinical positioning.
Geographic Demand Architecture
Regional demand patterns reveal a market shaped by healthcare infrastructure maturity, specialty physician density, reimbursement frameworks, and access to advanced retinal and oncology care. North America accounts for the largest revenue contribution, reflecting the concentration of high-value retinal practices, early adoption of flexible dosing regimens, and robust commercial infrastructure for novel biologics. Europe follows as a substantial demand center, supported by differentiated access pathways and strong clinical adoption in retinal disease management.
Asia Pacific represents a structurally important growth vector. The region’s expanding patient populations, growing specialty care networks, and increasing penetration of advanced diagnostics create a multi-layered demand environment. Latin America and the Middle East and Africa contribute more modest shares today but function as incremental growth markets where access expansion, pricing strategy, and diagnostic availability will determine the pace of adoption. For global strategists, regional planning must account for differing reimbursement rhythms, competitive entry timing, and the diagnostic ecosystem that supports both research and clinical quantification workflows.
Competitive Landscape: Differentiated Positioning Around a Dual-Pathway Core
The competitive structure of the Angiopoietin 2 market is characterized by clear stratification between therapeutic innovators, diagnostic and research tool providers, and organizations operating at the intersection of both. Market concentration indicates that a small cohort of commercially advanced players commands a dominant share of therapeutic value, while a broader ecosystem of research suppliers supports the scientific and clinical infrastructure underlying biomarker quantification and drug development.
F. Hoffmann-La Roche Ltd, through its Genentech portfolio, anchors the therapeutic side of the market with faricimab, a bispecific antibody designed to inhibit both VEGF-A and Angiopoietin 2. The strategic importance of this asset extends beyond its current label footprint. Recent regulatory expansion into macular edema secondary to retinal vein occlusion, alongside product format innovations such as prefilled syringe availability, reflects a deliberate effort to broaden usability, reduce administration friction, and extend real-world adoption. The dual-pathway mechanism supports flexible dosing regimens that address a persistent clinical pain point in retinal care, reinforcing the asset’s positioning as a therapy built for chronic management rather than episodic intervention.
Boehringer Ingelheim represents a distinct competitive vector through its development of BI 836880, a bispecific nanobody targeting VEGF and Angiopoietin 2 in clinical evaluation for solid tumors. This approach illustrates how Angiopoietin 2 targeting is being translated into oncology combination strategies, where nanobody architecture, tumor microenvironment engagement, and immuno-oncology pairing may create differentiated value. The publication of early-phase clinical data signals a pipeline that is actively exploring the boundaries of the mechanism beyond retinal disease.
On the research and diagnostic side, a parallel competitive field has formed around reliable quantification and reproducible assay infrastructure. R&D Systems, Abcam, Thermo Fisher Scientific, Sigma-Aldrich, and Sino Biological each contribute to a market ecosystem that depends on consistent biomarker measurement across serum, plasma, cell culture supernates, and other sample types. ELISA kits, recombinant proteins, and antibody reagents form the backbone of both drug development workflows and clinical research operations. In this segment, competition is driven by assay robustness, sample versatility, supply reliability, and the ability to navigate raw material price volatility in bioreagents. As global demand and manufacturing constraints continue to influence input costs, suppliers that can maintain consistency and scale will consolidate advantage in the research tooling layer.
The broader implication for strategists is that the Angiopoietin 2 market is not a single competitive arena but a linked system. Therapeutic adoption reinforces diagnostic and research demand; diagnostic reliability supports clinical evidence generation; and evidence generation, in turn, shapes regulatory and reimbursement trajectories. Organizations that understand these interdependencies are better positioned to anticipate downstream effects of product launches, label expansions, and pipeline readouts.
Worldwide INF2 Antibody Market
Market Dynamics: Regulation, Reimbursement, and Input-Side Pressure
Several structural dynamics are reshaping how value is created and captured in this market. Regulatory breadth is expanding the addressable patient population. Faricimab has already achieved approval across more than 100 countries for neovascular AMD and diabetic macular edema, and across more than 30 countries for macular edema following retinal vein occlusion. This global regulatory footprint reduces market fragmentation risk for the leading dual-pathway asset and establishes a high bar for entrants seeking comparable geographic coverage.
Reimbursement dynamics are increasingly intertwined with clinical convenience. Angiopoietin 2 inhibitors that target dual pathways and support flexible dosing regimens create value not only through efficacy but through treatment burden reduction. In practice, flexible dosing can influence adherence, clinic throughput, and total cost of care, making reimbursement adjudication sensitive to real-world administration patterns as well as clinical endpoints. For commercial teams, this means that access strategy must be built around dosing flexibility, site of care considerations, and the economic logic of chronic management.
On the supply side, raw material volatility presents an ongoing operational consideration. ELISA kit production and broader bioreagent manufacturing face price pressure linked to global demand and manufacturing constraints. This dynamic affects both diagnostic suppliers and drug developers who rely on consistent reagent quality for assay development, biomarker quantification, and quality control workflows. Organizations that embed supply resilience, dual sourcing, and inventory agility into their operating models will be better insulated from input-side disruption.
Strategic Implications for 2026 Decision-Making
For executives evaluating exposure to the Angiopoietin 2 market in 2026, the strategic question is no longer whether the mechanism has clinical relevance. That question has been answered by regulatory approvals, commercial uptake, and expanding indication coverage. The decisive questions now concern sequencing, differentiation, and ecosystem positioning.
First, therapeutic entrants must assess whether they can compete on dual-pathway convenience, dosing architecture, and regional access, or whether they should pursue differentiated niches in oncology, inflammatory disease, or combination regimens. The revenue concentration in the market suggests that broad retinal uptake will be contested by established bispecific franchises, while adjacent indications may offer more targeted entry points for developers with distinct molecular formats or partnership advantages.
Second, diagnostic and research suppliers should treat biomarker quantification infrastructure as a strategic layer rather than a commoditized support function. Demand for reliable Angiopoietin 2 measurement will remain tightly coupled to drug development activity, clinical research, and real-world evidence generation. Competitive advantage will accrue to suppliers that can deliver reproducible performance across sample types while managing input volatility and scaling efficiently.
Third, market participants should plan around the interaction between regulatory expansion, reimbursement logic, and regional adoption. A global approval footprint accelerates market maturity in leading regions, but incremental indications and format innovations can reshape local demand curves. Strategic planning should therefore incorporate both the timing of label changes and the practical economics of administration, site of care, and access negotiation.
Angiopoietin 2 Market
What the Full Study Provides
This article outlines the structural logic of the Angiopoietin 2 market and the strategic questions that matter for 2026 planning. The full market research study extends this framework into a detailed, decision-ready intelligence package. It provides granular market sizing across the forecast window, segmentation analysis by region, indication, and drug class, and a competitive profile set that maps product positioning, development activity, and recent commercial and regulatory milestones. The study also examines market concentration, dynamic drivers across regulation, reimbursement, and raw material supply, and the interaction between therapeutic adoption and diagnostic demand.
For teams that need to convert market awareness into actionable strategy, the complete report offers the depth required to support portfolio prioritization, entry timing, pricing and access design, and competitive response planning. The macro trajectory, segmentation architecture, and competitive dynamics described here are intended to establish the analytical foundation; the full study delivers the operational specificity necessary to move from direction to execution.
The Angiopoietin 2 market is advancing along a structurally strong growth path, supported by dual-pathway clinical rationale, expanding regulatory coverage, and a competitive field that spans both therapeutics and research infrastructure. Organizations that analyze this landscape with precision will be better equipped to capture value, manage risk, and position for the next phase of commercialization through 2032.
For detailed analysis of this topic, please visit the official page: Angiopoietin 2 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com