

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Vacuum Cleaner Bags Market to Reach US$3,553M by 2032, Growing at 3.2% CAGR

Strategic Intelligence for the Evolving Filtration Landscape: Inside the 2026 Vacuum Cleaner Bags Market Research
In an era where supply chain volatility, regulatory shifts, and changing consumer preferences converge, the global vacuum cleaner bags market requires more than surface-level observation. At PW Consulting, we recognize that filtration consumables represent a strategic interface between appliance OEMs, aftermarket distributors, and end-users who increasingly demand respiratory health, allergen control, and operational efficiency. Our latest Worldwide Vacuum Cleaner Bags Market research is designed to equip executives, product planners, procurement leaders, and investment analysts with the structured intelligence needed to navigate 2026 decision cycles with confidence.
The market has reached an inflection point. Between 2020 and 2025, global revenue expanded from approximately USD 2,435 million to USD 2,850 million, reflecting a measured but resilient trajectory shaped by post-pandemic household investment, professional cleaning sector recovery, and the sustained deployment of bagged systems in commercial environments. Looking ahead, the forecast period from 2026 through 2032 projects continued expansion, with revenue anticipated to approach USD 2,893 million in 2026 and gradually progress toward higher valuation thresholds as regional adoption patterns, product innovation cycles, and distribution optimization mature. The compound annual growth rate across the forecast window is positioned at 3.2%, a figure that underscores steady underlying demand while highlighting the necessity of precise portfolio positioning, cost discipline, and channel strategy execution rather than broad-brush volume assumptions.
This research is not a static data sheet. It is an operational framework that translates macro trajectory into actionable strategy, enabling organizations to anticipate margin pressures, evaluate competitive vulnerability, and identify where value creation will be won or lost over the next seven years.
The Structural Forces Shaping 2026 Market Arithmetic
Understanding why the vacuum cleaner bags market moves the way it does requires attention to interconnected pressures that rarely appear in isolation. Our analysis maps several dynamics that will define competitive outcomes in 2026 and beyond.
- Upstream material economics now play a more visible role in cost structuring. Nonwoven polypropylene fabric, a critical input for synthetic and microfiber filtration bags, recorded a year-over-year price increase of 12% to reach approximately $1,450 per metric ton. This shift places pressure on manufacturers of synthetic-based bags and compels portfolio rebalancing between material categories, pricing architecture, and value-added filtration claims.
- Regulatory architecture continues to anchor product standards. The EU Ecodesign Directive 665/2013 mandates minimum dust pick-up and filtration efficiency for replaceable vacuum bags, reinforcing performance as a baseline expectation rather than a differentiator. Compliance is no longer optional; it is a market entry condition that shapes design cycles, testing protocols, and cross-border commercial strategy.
- Trade policy introduces asymmetry in sourcing and pricing. U.S. Section 301 tariffs impose duties of up to 25% on vacuum cleaner bags imported from China, altering landed-cost calculations for imported supplies and encouraging regional sourcing strategies, inventory repositioning, and channel-specific pricing adjustments.
- End-user technology preferences exert structural tension on bagged segments. Bagless vacuum models captured 65% of global sales in 2023, pressuring bagged segment margins and accelerating the need for filtration upgrades, system compatibility clarity, and compelling total-cost-of-ownership narratives that justify consumable replacement cycles.
- Quality and safety continuity supports market steadiness. As of Q1 2026, there are no active recalls on vacuum cleaner bags, with the last notable incident involving Hoover type Y bag delamination in 2018. This environment rewards manufacturers and aftermarket suppliers who institutionalize consistency, traceability, and transparent compatibility guidance.
These forces do not operate in parallel; they overlap, interact, and frequently demand trade-offs. The strategic question for 2026 is not whether the market will grow, but which players can convert complexity into defensible positioning.
What the Report Delivers: A Practitioner’s Roadmap
PW Consulting’s study is structured to support decision-making at multiple organizational levels. Rather than offering a single aggregated narrative, the research decomposes the market into analytically rigorous dimensions that executives can deploy directly in planning sessions, investment committees, and product reviews.
Coverage Architecture
The report maps the market across material segmentation, distribution pathways, and geographic reach. This allows clients to evaluate where growth is concentrated, where substitution risk is most pronounced, and where channel economics create durable advantage. The analysis is designed to support questions such as:
- Which material categories are being reshaped by cost structures, filtration expectations, and reusable-versus-disposable usage patterns?
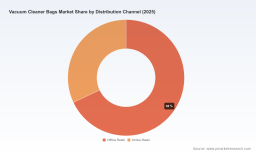
- How do offline and online retail channels differ in margin profiles, assortment logic, and consumer purchase behavior for replacement bags?
- Where do regional demand patterns, appliance base composition, and channel maturity create differentiated opportunities for localized product strategy?
Strategic Applications
Beyond segmentation, the report provides context that supports practical interventions. Readers will find guidance relevant to portfolio pruning, SKU rationalization, compatibility positioning, aftermarket substitution dynamics, and supplier selection criteria. The study also connects market structure to operational considerations such as packaging evolution, product lifecycle management, and the role of performance claims in driving repeat purchase behavior.
Vacuum Cleaner Market
For organizations seeking to align commercial planning with market reality, the report serves as a reference point for scenario development, pricing strategy calibration, and competitive response planning. It is built to be revisited throughout the planning cycle rather than read once and archived.
Analytical Discipline
Our methodology emphasizes comparability, transparency, and relevance. Historical data from 2020 through 2025 is integrated with forward-looking projections through 2032, enabling trend validation and sensitivity discussion. The report maintains consistency in valuation language and forecast framing so that internal teams can discuss growth, share shifts, and channel contribution with a common vocabulary. Importantly, the research is constructed to support decisions, not merely to describe them.
Competitive Landscape: Ten Profiles, One Contested Arena
The vacuum cleaner bags market is shaped by a mix of appliance-linked manufacturers, specialty filtration producers, and aftermarket suppliers that compete on compatibility, performance claims, packaging, and channel access. The study profiles ten companies whose strategies illustrate how value is created and defended in a market where substitution risk, proprietary fittings, and filtration expectations continually reset commercial priorities.
Miele & Cie. KG represents the premium air-quality segment with its AirClean vacuum cleaner bags, engineered for high-efficiency filtration across Miele canister and upright platforms, including Type G/N, U1, and S500 series. Its October 2024 introduction of next-generation AirClean FJM Luftreiniger bags with enhanced allergen filtration for U1 models demonstrates how performance refinement can reinforce brand positioning and extend replacement-cycle relevance. SEBO America, LLC operates with a focused product logic around ET-1, ET-2, and ET-C microfiber vacuum bags optimized for SEBO commercial and residential models with S-class filtration, and its September 2024 exhibition of updated ET-C Comfort bags at the ISSA Show North America highlighted the continued importance of professional cleaning channels and trade visibility.
Electrolux Group supplies type E, EL, and S bags for Electrolux, Eureka, Zanussi, and Sanitaire bagged vacuum cleaners, reflecting the role of broad appliance portfolios in consolidating replacement demand across multiple brands and end-use settings. Nilfisk Group manufactures GM and RFM series bags for Nilfisk professional canister and upright vacuums, aligning consumable supply with durable professional equipment usage. Numatic International Ltd provides NVM-1CH and Henry-specific paper bags for Henry, Hetty, and commercial bagged vacuums, and its March 2024 catalog release of eco-friendly recycled paper bags for the Henry Hoover series in new packaging illustrates how sustainability messaging and packaging updates can refresh a mature product line.
Alfred Kärcher SE & Co. KG offers fleece and paper bags for Kärcher wet/dry vacuums and canister models such as the WD and VC series, showing how consumable strategies extend across mixed equipment categories. Aerus LLC serves as the exclusive manufacturer of Mikrofek and Style 3 micron bags for Kirby bagged vacuum systems, an example of tightly controlled compatibility that can support loyalty but also concentrates dependence on a single platform. EnviroCare operates as an aftermarket producer of compatible vacuum bags for Miele, SEBO, Riccar, Simplicity, and Hoover models, with synthetic and paper options that position it within the substitution economy where price, availability, and compatibility clarity become decisive. Techtronic Industries (TTI) produces bags for Hoover, Dirt Devil, and Oreck bagged upright and canister vacuums under type Y and B series, linking consumable supply to a wide consumer-facing brand footprint. Riccar America supplies R bags for Riccar and Simplicity lightweight upright vacuums, reinforcing the importance of model-specific fit and targeted distribution.
Taken together, these profiles reveal a market where competitive advantage is rarely about any single attribute. It is about the combination of filtration credibility, compatibility breadth, channel strength, brand trust, and cost structure. The report examines these themes in greater depth, allowing clients to compare strategic postures without being confined to a narrow snapshot.
Market Concentration and the Implication for Strategy
The industry’s competitive structure is moderately consolidated. The combined share of the top three competitors is approximately 42.5%, while the top five reach roughly 58.8%. This distribution indicates that leading players exert meaningful influence over pricing norms, product standards, and channel expectations, while still leaving substantial room for specialized and aftermarket participants to compete on fit, service, and cost.
For 2026 planning, this concentration pattern carries several implications. Incumbents must protect performance perception and distribution relationships while managing input cost volatility and substitution pressure from bagless alternatives. Challengers and compatible-supply entrants need to navigate fit assurance, compatibility communication, and channel access carefully, especially where tariff exposure and material cost trajectories can compress margin tolerance. OEMs and private-label strategists, meanwhile, benefit from understanding where brand equity, proprietary fittings, and filtration claims create durable retention versus where price-driven switching becomes more likely.
Why This Research Matters for 2026 Decisions
The most valuable insights in a market study are not always the ones that are easiest to publish in a summary. In a market influenced by material inflation, trade policy, regulatory baselines, channel evolution, and technology substitution, strategic advantage comes from knowing where to focus, what to test, and which assumptions deserve challenge. PW Consulting’s Worldwide Vacuum Cleaner Bags Market research is built for exactly that purpose.
Worldwide Vacuum Cleaner Bags Market
It gives leadership teams a structured view of where revenue is flowing, how product categories are differentiating, how distribution pathways are shaping purchase behavior, and how competitive positioning is likely to evolve. It helps procurement teams frame sourcing decisions in light of material trends and tariff exposure. It helps product and brand teams assess where filtration claims, compatibility clarity, and packaging updates can support repeat purchase behavior. It helps investors and analysts interpret growth potential without mistaking headline momentum for durable advantage.
Next Steps
The vacuum cleaner bags market will continue to reward organizations that combine operational discipline with strategic clarity. The full report provides the detailed segmentation evidence, competitive context, and forward-looking interpretation needed to turn that discipline into practical action. For teams preparing 2026 planning cycles, the complete analysis offers a more granular foundation for scenario modeling, portfolio review, and channel strategy. To access the full market intelligence, segmentation detail, and company-level interpretation, refer to the complete PW Consulting Worldwide Vacuum Cleaner Bags Market research and use it as a working document for cross-functional decision-making throughout the year.
For detailed analysis of this topic, please visit the official page: Worldwide Vacuum Cleaner Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com