

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Liquid Nitrogen Cryotherapy Equipment Market Hits $342.5M in 2025, 7.51% CAGR

Strategic Intelligence for the Liquid Nitrogen Cryotherapy Equipment Market: Navigating the 2026–2032 Growth Trajectory
The global landscape for liquid nitrogen cryotherapy equipment is undergoing a structural transformation. As healthcare providers, medtech investors, and strategic planners confront an increasingly complex regulatory and reimbursement environment, the ability to separate short-term market noise from durable growth signals has become a critical competitive advantage. Our newly released Worldwide Liquid Nitrogen Cryotherapy Equipment Market study delivers precisely that clarity: a rigorously validated, forward-looking intelligence framework built to inform capital allocation, product positioning, and portfolio strategy across the 2026–2032 forecast horizon.
Cryotherapy Units Market
This introductory analysis outlines the strategic architecture of the research, demonstrates how the underlying data maps to real-world decision cycles, and highlights the operational and competitive dimensions that matter most to executives planning their next three to five years of growth. The narrative that follows is deliberately high-level, designed to establish analytical credibility while preserving the granular segmentation, pricing benchmarks, and regional breakdowns that await in the full report.
Why 2026 Marks a Strategic Inflection Point
Cryotherapy has evolved from a niche dermatologic intervention into a diversified therapeutic modality spanning oncology, beauty and wellness, and localized tissue management. The market’s maturation is reflected in a clear upward trajectory: from a base of approximately 342.5 million USD in 2025, the sector expands to roughly 368.67 million USD in 2026 and continues climbing through the end of the decade, with long-range projections indicating sustained momentum beyond 2030. This growth is not merely incremental; it is being shaped by an accelerating pipeline of device clearances, evolving clinical indications, and a competitive field that is actively refining capital equipment design, nitrogen-handling integration, and workflow ergonomics.
For enterprises making 2026 commitments, the question is no longer whether cryotherapy equipment will grow, but how that growth distributes across device architectures, application pathways, and geographic demand centers. Strategic planning requires a precise understanding of the operational levers that convert clinical adoption into recurring revenue, service contracts, training ecosystems, and localized supply partnerships. The full report translates these dynamics into actionable matrices, enabling stakeholders to evaluate entry timing, capacity planning, and partnership structures without relying on generic market narratives.
The Analytical Architecture of the Research
Our market study was constructed with a decision-first methodology. Rather than presenting a static snapshot of historical volumes, the analysis embeds time-series validation, competitive benchmarking, regulatory mapping, and application-specific adoption patterns into a single, referenceable intelligence system. The objective is to give strategy, commercial, and clinical affairs teams a shared factual baseline that supports scenario planning, investment committee discussions, and product roadmap alignment.
Worldwide Liquid Nitrogen Cryotherapy Equipment Market
The report addresses the full equipment value chain: capital devices used in clinical dermatology, cryoablation platforms deployed in oncology workflows, and whole-body or localized chambers positioned within wellness and recovery environments. It also examines the operational realities that determine commercial success, including nitrogen handling requirements, device durability, service infrastructure, and the increasingly important interplay between clearance status and procurement eligibility. Each section is designed for immediate reuse in internal briefing materials, partner evaluations, and market-entry modeling.
Segment Landscape Without Losing Sight of Strategy
The equipment continuum is anchored by device categories that serve distinct clinical and commercial missions. At one end of the spectrum are compact, point-of-care spray and contact instruments designed for precise lesion management in outpatient and office-based settings. These systems have become standard durable equipment in dermatology practices because they combine repeatable performance, straightforward workflow integration, and compatibility with routine cryosurgical protocols. At another tier sit more complex surgical and ablation platforms, which are increasingly evaluated not only on technical capability but also on clearance pathways, surgeon adoption patterns, and reimbursement clarity. A third category comprises chambers and localized delivery systems, which are expanding beyond traditional clinical use into recovery, rehabilitation, and consumer-adjacent wellness environments.
What makes this segmentation commercially meaningful is the divergence in adoption drivers. Clinical dermatology equipment often scales through practitioner familiarity, disposables and service ecosystems, and institutional procurement cycles. Oncology-focused platforms depend on clinical evidence generation, regulatory authorization trajectories, and integration into procedural pathways. Wellness-oriented installations frequently hinge on operational economics, site readiness, and the credibility of supplier support. The complete research quantifies these dynamics in a structured framework so that readers can compare segment economics, demand elasticity, and competitive intensity without treating the categories as interchangeable.
Geography as a Strategic Variable
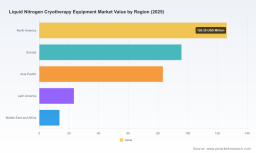
Hardware strategy cannot be decoupled from regional context. Procurement norms, regulatory classification expectations, service density, and local nitrogen supply arrangements vary substantially across markets, creating different barriers to entry and different pathways to scale. A consolidated view of regional distribution highlights where installed-base momentum is strongest and where latent demand remains underpenetrated relative to clinical need and capital availability.
Rather than treating geography as a simple volume map, the report contrasts regions by procurement behavior, device mix preferences, and competitive presence. This allows readers to assess where a handheld or chamber-based offering is likely to encounter immediate traction versus where a longer commercialization timeline may be required. The detailed regional breakdowns, including market size distributions and demand concentration metrics, are reserved for the downloadable research, where they are presented alongside purchasing cycle analysis and channel considerations.
Competitive Landscape and the Meaning of Focus
The competitive field in liquid nitrogen cryotherapy equipment is shaped by manufacturers with differentiated engineering heritage, distinct clearance portfolios, and varying degrees of integration between device performance and operational support. Several established players anchor the dermatology and point-of-care segment through long-standing presence in handheld spray systems and lesion treatment workflows. Their product lines reflect decades of refinement in temperature delivery, nitrogen capacity, and clinic-friendly ergonomics, and they continue to influence procurement expectations in outpatient settings worldwide.
Adjacent to these clinical-grade spray devices are manufacturers expanding the cryosauna and whole-body chamber category, often with an emphasis on certified manufacturing environments, medical device classification alignment, and structured support for site installation and nitrogen supply integration. These producers differentiate not only through chamber design and environmental control, but also through how they position their equipment within wellness operators, recovery centers, and specialized clinical programs.
A third competitive vector is emerging around targeted cryoablation and localized destruction platforms. Recent regulatory milestones have brought liquid nitrogen cryoablation into more defined therapeutic conversations, with authorization pathways that explicitly frame the technology around specific patient populations and lesion types. For investors and OEM strategists, the significance lies less in any single clearance and more in the pattern they reveal: regulatory progress is enabling modalities once confined to narrowly defined use cases to enter broader procedural discussions, provided evidence, labeling, and reimbursement alignment evolve in parallel.
Recent product and regulatory activity reinforces this competitive maturation. Sector participants continue to refine device usability, for example through design updates that address maintenance concerns such as filter longevity and nitrogen flow consistency. At the same time, multiple entities have advanced through U.S. clearance processes for cryosurgical and ablation-related indications, signaling that the pipeline remains active and that market access conditions are being incrementally reshaped. These developments matter because procurement teams increasingly weigh not just technical capability, but the durability of regulatory standing, post-market obligations, and supplier reliability over the equipment lifecycle.
Regulatory and Reimbursement Dynamics as Decision Inputs
One of the most actionable contributions of the study is its treatment of regulatory and reimbursement context as a planning variable rather than a background condition. Cryotherapy equipment does not sell into a uniform compliance environment. Classification expectations, quality-system alignment, and clearance pathways differ across jurisdictions and across device categories, and these differences influence procurement eligibility, clinical adoption, and risk exposure for both buyers and manufacturers.
The research maps these considerations across device types and application contexts, drawing attention to the operational implications of meeting Class II cryosurgical expectations for dermatology-focused instruments and aligning product documentation with evolving medical device frameworks in other regions. For OEMs, this landscape shapes design control, labeling strategy, and post-market surveillance planning. For distributors and clinical buyers, it affects supplier qualification, service expectations, and long-term equipment viability. By consolidating these factors into a structured view, the report helps decision-makers anticipate friction points before they become commercial obstacles.
Reimbursement, Procurement, and Commercial Readiness
Even where clinical utility is well established, commercial velocity is often determined by procurement classification, coding clarity, and the practical ease with which a facility can justify acquisition. Cryosurgical equipment used for lesion management typically operates within familiar regulatory controls, but the commercial reality of budget cycles, capital planning, and multi-stakeholder approval still dictates purchase timing and volume. For more procedure-oriented platforms, reimbursement narratives and clinical pathway integration become central to adoption, meaning that product roadmaps must be synchronized with evidence generation, labeling scope, and the pace at which payers and providers incorporate new indications into standard workflows.
The report translates these considerations into commercial readiness themes: what kind of documentation and service infrastructure supports acquisition confidence, how installation and nitrogen supply partnerships influence site-level economics, and where the opportunity lies in bundling devices with training, maintenance, and operational support. These elements are especially relevant for enterprises evaluating expansion into adjacent geographies or application verticals where local credibility can be as important as product performance.
How Strategic Leaders Should Use This Intelligence
The value of the report lies in its portability across decision contexts. For corporate strategy teams, the analysis supports market-entry timing, segment prioritization, and resource allocation by connecting demand signals with competitive intensity and regulatory exposure. For product leaders, it provides an evidence-based frame for assessing whether to deepen presence in existing device categories, introduce complementary accessories or service offerings, or prepare for additive capabilities in response to evolving clinical use. For investors and partners, it clarifies where durability of competitive advantage is likely to come from: manufacturing quality, clearance standing, installation and supply integration, clinician adoption, and post-market support, rather than headline market growth alone.
In practice, the research is built to be operationalized. Readers can align internal scenario models with validated time-series trajectories, benchmark product positioning against established manufacturers and recent entrants, evaluate the implications of regulatory developments on commercial timelines, and identify geographic or application spaces where purchasing behavior and device mix create asymmetric opportunities. This is intelligence designed for use, not merely inspection.
What the Full Report Delivers
This article is a strategic preview. The complete Worldwide Liquid Nitrogen Cryotherapy Equipment Market research goes further, offering a detailed quantitative foundation and a structured qualitative backdrop calibrated for executive decision-making. It integrates validated market sizing and growth projections across the base year and forecast window, examines segmentation dynamics across equipment types and application pathways, and provides consolidated regional distribution perspectives that illuminate where demand is concentrated and how competitive presence varies by market.
Beyond macro data, the report delivers buyer-facing commercial intelligence: competitive profiles that connect product heritage with clearance status, recent regulatory and product developments that affect market access, manufacturing quality and classification context where relevant, and the operational variables that determine whether equipment translates into sustainable revenue. The objective is to give leadership teams a single, defensible reference point for planning through 2032.
Begin the Decision with the Right Map
Liquid nitrogen cryotherapy equipment sits at the intersection of clinical utility, regulatory evolution, and expanding application breadth. Growth is real, but where value will be captured in 2026 and beyond depends on how precisely organizations understand device differentiation, regional demand behavior, clearance trajectories, and the operational infrastructure that turns a promising modality into a profitable, scalable business. Our report provides that understanding in a form built for strategy, procurement, and investment teams alike.
For decision-makers who need the full segmentation detail, regional breakdowns, competitor positioning, and the complete forecast series to support planning, the comprehensive report is available through our market intelligence portal. Access it directly to move from strategic overview to actionable intelligence and to ensure your next planning cycle is grounded in validated market structure rather than partial signals.
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Nitrogen Cryotherapy Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com