

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Oral Solid Dosage Medicine Market to Reach $1.13 Trillion by 2032, 6.3% CAGR

Global Oral Solid Dosage Medicine Market: Strategic Outlook 2026-2032
The worldwide oral solid dosage (OSD) medicine market stands at a critical inflection point as the industry transitions from historical growth patterns into a new cycle defined by manufacturing localization, patent cliffs, and supply chain restructuring. Our latest comprehensive study, covering the historical period from 2020 through 2025 and extending forecast projections to 2032, provides the strategic intelligence required to navigate this complex landscape. This article outlines the core dynamics shaping the sector and demonstrates why precise, forward-looking market intelligence is indispensable for corporate decision-making in 2026.
Market Trajectory and Structural Growth Drivers
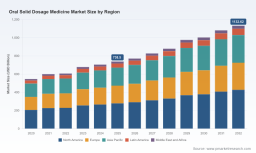
The OSD sector has demonstrated consistent expansion over the past half-decade, with global revenue climbing from approximately 546 billion USD in 2020 to an estimated 738.5 billion USD in 2025. This trajectory reflects not only baseline pharmaceutical demand but also the structural advantages of solid dosage forms, which continue to dominate prescription volume due to patient compliance, manufacturing scalability, and established distribution networks. The forecast period through 2032 points toward sustained momentum, with the market projected to surpass the one trillion USD threshold before the end of the decade and approach 1.13 trillion USD by 2032. Driving this expansion is a compound annual growth rate of 6.3 percent, a figure that underscores the resilience of oral formulations even as biologic therapies and novel delivery mechanisms capture headlines.
Several macroeconomic and clinical forces reinforce this growth profile. Aging demographics across developed and emerging markets continue to elevate prevalence rates for chronic conditions that rely heavily on long-term oral therapy regimens. Simultaneously, healthcare systems worldwide are prioritizing cost containment, which paradoxically benefits OSD products given their established manufacturing efficiencies and the substantial share of prescriptions filled by lower-cost generic alternatives. The interplay between volume expansion and pricing pressure creates a nuanced environment where manufacturers must optimize production throughput, reduce waste, and invest in advanced formulation technologies to maintain margin integrity.
Segmentation Landscapes: Dosage Forms and Therapeutic Areas
Understanding where value concentrates within the OSD ecosystem is essential for portfolio strategy and capacity planning. Tablets remain the dominant dosage form, commanding the largest share of global revenue among solid oral formats, followed by capsules which serve distinct patient populations and drug stability requirements. Powders, granules, and other solid forms occupy more specialized niches, often tied to pediatric formulations, compounding scenarios, or specific regional distribution channels. The relative weighting of these formats shapes capital expenditure decisions, as firms evaluate whether to expand existing tablet lines, invest in capsule-specific encapsulation infrastructure, or develop flexible manufacturing suites capable of handling multiple solid dose configurations.
Therapeutic area segmentation further reveals where demand intensity and innovation pipelines intersect. Chronic metabolic and diabetes-related disorders represent a substantial revenue center, reflecting the global burden of insulin resistance, type 2 diabetes, and related comorbidities. Oncology follows as a critical growth vector, with oral oncolytics increasingly complementing infusion-based regimens and enabling decentralized treatment models. Cardiovascular indications, central nervous system disorders, and infectious diseases each contribute meaningful share, while aggregate demand across other therapeutic categories rounds out the portfolio. The distribution of revenue across these areas highlights the importance of therapeutic diversification for manufacturers seeking to mitigate cyclical risks and align production capabilities with high-growth clinical segments.
Regional Dynamics and Supply Chain Realities
Geographic distribution of OSD consumption and production continues to evolve as trade policies, labor economics, and regulatory frameworks reshape manufacturing footprints. North America remains a dominant revenue region, underpinned by deep pharmaceutical infrastructure, robust clinical demand, and sustained investment in domestic production capacity. Europe maintains a substantial market position, though it faces distinct regulatory and cost pressures that influence sourcing decisions and manufacturing localization strategies. Asia Pacific represents a sizable and growing region, driven by expanding healthcare access, generic manufacturing scale, and increasing domestic consumption of finished dosage forms. Latin America and the Middle East and Africa, while smaller in absolute revenue terms, present strategic opportunities for market penetration, emerging clinical needs, and cost-competitive manufacturing hubs.
Supply chain dynamics add further complexity to regional analysis. Recent data indicate that active drug shortages in the United States declined from peak levels observed in early 2024, yet remain elevated relative to pre-pandemic baselines, creating intermittent disruptions across various OSD products. Excipient supply volatility, including notable price spikes for microcrystalline cellulose and lactose, contributed to more than a quarter of documented shortages in 2024, prompting manufacturers to pursue dual-sourcing strategies and alternative raw material qualification. Additionally, the potential imposition of tariffs on active pharmaceutical ingredients threatens to raise input costs for imported generic OSD products, a concern amplified by the fact that a significant majority of generic tablets and capsules consumed in the United States originate from overseas sources. These supply-side pressures are catalyzing a broader reevaluation of where and how solid dose products are manufactured.
Competitive Landscape and Capital Allocation Signals
The OSD market is characterized by a mix of large multinational originators, specialized generic manufacturers, and contract development and manufacturing organizations that collectively shape capacity, innovation, and pricing dynamics. Industry concentration metrics indicate a moderately fragmented landscape, with the top three firms accounting for a combined share in the high teens and the top five firms commanding just under a quarter of total revenue. This structure reflects both the scale advantages of global pharmaceutical enterprises and the specialized capabilities of regional and niche manufacturers that serve distinct customer segments.
Strategic capital allocation among leading participants signals where the industry is placing its long-term bets. Novartis has announced a substantial multi-year investment program in United States infrastructure, including a dedicated facility for chemical drug substances, oral solid dosage forms, and packaging, reinforcing a trend toward end-to-end domestic production for key medicines. Eli Lilly and Company has similarly committed to a major manufacturing expansion in the Netherlands, focusing on advanced oral solid dosage technologies to support a portfolio that includes next-generation cardiometabolic therapies. Piramal Pharma Solutions has moved to strengthen its fixed-dose combination capabilities through a dedicated suite partnership, while LGM Pharma continues to scale its United States presence with incremental investments targeting niche, high-value oral solid dose products and orally disintegrating tablet formats. These commitments illustrate a broader industry emphasis on securing manufacturing capacity for high-priority molecules, reducing dependency on concentrated supply nodes, and building flexibility into production networks.
The contract manufacturing segment remains equally vital, with leading CDMOs expanding their OSD development and commercial scale-up capabilities across multiple global sites. Firms specializing in high-potency compounds, complex formulation strategies, and integrated packaging solutions are positioned to benefit as innovator companies increasingly rely on external partners to manage capacity bottlenecks and accelerate time-to-market. Generic-focused manufacturers continue to play an indispensable role in ensuring broad access to oral solid therapies, particularly as patent expirations open substantial revenue pools to competitive entry.
Patent Expirations, Generics, and Pricing Realities
One of the most consequential dynamics facing the OSD market over the forecast horizon is the wave of small-molecule patent expirations projected between 2025 and 2030. Analysts estimate that these expirations could result in hundreds of billions of dollars in revenue erosion for originator companies, driven by rapid generic entry and steep sales declines within the first year of competition. This pattern reinforces the strategic importance of lifecycle management, formulation innovation, and manufacturing efficiency for both originators seeking to defend market position and generic manufacturers preparing to capture volume.
Generics, which are overwhelmingly oral solid dosage forms, already account for the overwhelming majority of prescription volume in the United States, supporting healthcare cost containment through lower pricing after patent expiry. For manufacturers, this reality creates a dual imperative: maintain competitive cost structures to thrive in generic markets while investing in differentiated capabilities that allow branded products to sustain premium positioning where clinically justified. The balance between volume-driven generic growth and value-driven branded strategies will remain a defining tension for OSD companies throughout the forecast period.
Why This Research Matters for 2026 Decision-Making
Entering 2026, pharmaceutical and life sciences executives face a matrix of interdependent decisions: where to allocate capital for manufacturing expansion, how to structure supply chains against ingredient volatility and trade uncertainty, which therapeutic segments to prioritize for capacity investment, and how to position product portfolios against impending patent cliffs. Generic market entrants require equally precise intelligence to time launches, assess competitive density, and secure sourcing arrangements that protect margin profiles. The depth and granularity of our Worldwide Oral Solid Dosage Medicine Market report are designed to address these needs directly.
The study provides a detailed historical reconstruction of market performance across the 2020 to 2025 period, establishing a credible baseline against which forecast assumptions can be evaluated. It maps revenue distribution across dosage forms, therapeutic areas, and regions, enabling stakeholders to identify concentration points, growth pockets, and structural shifts that may not be visible from top-line aggregates alone. Competitive profiles examine the strategic positioning, manufacturing footprints, and recent capital commitments of the companies shaping the marketplace, including major originators, generic specialists, and CDMOs that together define the operational fabric of the industry. Recent development timelines capture facility announcements, partnership structures, and capacity expansion moves that signal where the market is heading in the near term.
Orally Disintegrating Tablet Market
Beyond descriptive analysis, the report integrates regulatory, reimbursement, raw material, and regional context into a cohesive framework that supports scenario planning. Insights on drug shortage trends, excipient supply risks, potential tariff impacts, and patent expiration revenue exposure are woven into the analytical narrative to help leaders quantify vulnerabilities and stress-test strategic assumptions. This approach ensures that the intelligence is not merely descriptive but actionable, supporting decisions on capacity investment, sourcing diversification, therapeutic focus, and competitive positioning.
For organizations that require the full set of segmentation values, regional breakdowns, therapeutic area shares, competitive benchmarking metrics, and forecast trajectories across all modeled years, the complete report offers the detailed data architecture necessary for rigorous internal analysis and board-level presentation. The executive summary and sample sections provide a substantive preview of methodology and scope, while the full deliverable delivers the comprehensive dataset and strategic commentary required for implementation.
Conclusion: Positioning for the Next Phase of Growth
The worldwide oral solid dosage medicine market is entering a period in which historical growth patterns will be tested by supply chain reconfiguration, patent cliff dynamics, and evolving regional manufacturing strategies. The projected expansion toward more than 1.13 trillion USD by 2032, supported by a 6.3 percent compound annual growth rate, reflects enduring demand for oral therapies and the continued centrality of solid dosage forms to global pharmaceutical care. Yet realizing value in this environment demands more than confidence in the aggregate trend; it requires precise understanding of where growth is concentrated, which competitive moves are reshaping capacity, and how external pressures will influence cost structures and market access.
Worldwide Oral Solid Dosage Medicine Market
Our research is built to equip decision-makers with that understanding. By combining historical reconstruction, forward-looking forecasts, competitive intelligence, and contextual dynamics into a single integrated analysis, the study provides the strategic foundation needed to navigate 2026 with confidence. Stakeholders who ground their planning in this level of market clarity will be better positioned to allocate capital efficiently, manage supply risk, and capture growth opportunities as the OSD market moves into its next phase of evolution.
For detailed analysis of this topic, please visit the official page: Worldwide Oral Solid Dosage Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com