

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vending Payment Market Forecast $15.2B in 2025 to $32.5B by 2032 at 11.45% CAGR

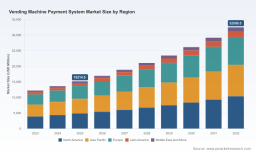
The Contactless Imperative: Strategic Intelligence for the Worldwide Vending Machine Payment System Market (2026–2032)
The global unattended retail ecosystem is undergoing a structural transformation. What was once a convenience-driven upgrade has become a fundamental infrastructure requirement. As consumer expectations shift toward frictionless, hygienic, and instantaneous transactions, vending machine payment systems have evolved from peripheral hardware into the central nervous system of modern self-service commerce. Our newly published Worldwide Vending Machine Payment System Market research study provides enterprise leaders, hardware manufacturers, payment processors, and vending operators with the analytical rigor required to navigate this inflection point through 2032.
This article outlines the strategic architecture of the study, emphasizing why 2026 represents a critical decision window for capital allocation, technology roadmapping, and competitive positioning. While we highlight the macro trajectory, regulatory pressures, and competitive dynamics shaping the sector, the granular segmentation data, regional revenue breakdowns, and proprietary operator benchmarks are reserved for the full report. Leadership teams that require precise investment thresholds, channel profitability modeling, and deployment sequencing frameworks will find the complete study essential.
Macro Trajectory: Why 2026 Is a Defining Baseline Year
The market has demonstrated sustained momentum across the historical evaluation window (2020–2025), with operational scale expanding rapidly as cashless acceptance moved from early adoption to mainstream standard. The industry closed the base year of 2025 at approximately 15,214.5 million USD , reflecting a decisive pivot away from cash-reliant architectures. Our forward projections map a clear uptrend through 2032, with the market expected to surpass 32,500 million USD by the end of the forecast horizon. The implied compound annual growth rate of 11.45% signals more than incremental expansion; it indicates a sector-wide restructuring of how payment infrastructure is designed, integrated, and monetized.
Several structural drivers underpin this trajectory. First, the installed base of connected vending endpoints has crossed a critical threshold, with industry monitoring reporting over 8.1 million connected vending machines globally in 2025 . Second, consumer behavior has stabilized around contactless preferences, with operator-side data indicating that 71% of vending transactions were cashless in 2024 , and roughly 77% of those cashless transactions were executed via tap or contactless methods . Speed, hygiene, and ease of use are no longer differentiators; they are baseline purchase conditions. Third, telemetry-enabled payment terminals are transforming vending from a transactional channel into a data-rich operational environment, enabling dynamic pricing, real-time inventory visibility, and predictive maintenance workflows that can reduce machine downtime by up to 30% for operators deploying IoT-enabled cashless solutions.
For decision-makers, these trends create a clear strategic implication: payment system selection is now inseparable from operational efficiency, data capture, and customer experience strategy. Companies that treat payment hardware as a commodity procurement item risk underutilizing one of the most valuable data and engagement layers in unattended retail.
Market Architecture: Payment Modalities, End-Use Verticals, and Regional Realities
The growth narrative is not monolithic. It is shaped by the interplay between payment technology maturity, vertical-specific deployment requirements, and regional regulatory environments. Our research dissects these layers to help organizations identify where adoption is accelerating, where integration complexity is highest, and where value capture will be concentrated.
Payment Technology Shifts
The market is increasingly defined by the dominance of contactless and mobile wallet acceptance, supported by card-based readers and emerging digital currency or QR-based pathways. Contactless NFC and mobile wallet integration now commands the largest share of payment system activity, reflecting the consumer preference for tap-and-go transactions and the operational advantage of reduced transaction friction. Credit and debit card readers continue to serve as a foundational layer, particularly in markets where mobile wallet penetration or infrastructure readiness varies. QR code and digital currency solutions represent a smaller but strategically important segment, especially in regions where smartphone-based payment ecosystems are advancing rapidly or where legacy hardware modernization requires low-cost bridging solutions.
End-Use Vertical Deployment Patterns
Vending machine payment systems are deployed across a diverse set of environments, each with distinct throughput expectations, security requirements, and integration constraints. Retail and commercial locations represent a major demand center, driven by high foot traffic and the need for fast, reliable payment acceptance in convenience-oriented settings. Transportation hubs form another critical axis, where unattended retail must accommodate transient passenger flows, higher transaction volumes, and stringent uptime expectations. Offices and institutions contribute steady, recurring demand tied to employee convenience, campus services, and controlled-access environments. Healthcare facilities introduce additional considerations around accessibility, hygiene, and compliance-sensitive deployment settings. Each vertical requires a different balance of hardware durability, telemetry capability, payment method breadth, and service-level commitments.
Regional Divergence and Strategic Implications
Regional dynamics shape both demand volume and technology preference. North America continues to reflect a mature, highly penetrated unattended retail market with strong emphasis on integrated telemetry and analytics. Asia Pacific captures substantial momentum, supported by rapid mobile payment ecosystem development, expanding urban convenience channels, and aggressive modernization of legacy machine fleets. Europe maintains a robust footprint shaped by regulatory nuance, particularly around contactless exemptions for unattended terminals and data security expectations. Latin America and the Middle East and Africa represent growth territories where infrastructure development, currency dynamics, andOperator adoption cycles create distinct entry and expansion strategies. The full study maps these regional trajectories in greater detail, enabling firms to align go-to-market timing, partner selection, and pricing architecture with local realities rather than global averages.
Competitive Landscape: Differentiation in a Consolidating Ecosystem
Strategic planning in this market requires a clear understanding of how incumbents and specialists are positioning themselves. The sector is characterized by a moderate concentration profile, with the top three players accounting for roughly 42.5% of market activity and the top five reaching approximately 58.2% . This structure suggests that scale matters, but differentiation remains achievable through software integration, telemetry capabilities, vertical specialization, and global service coverage.
Nayax Ltd. , headquartered in Herzliya, Israel, has built a global footprint around cashless vending payment systems that combine credit card readers, contactless and NFC terminals, mobile wallet integration, and telemetry for operators and manufacturers. Its end-to-end ecosystem positioning was reinforced through recent trade show showcases emphasizing cashless acceptance, real-time analytics, and loyalty program integration. Cantaloupe, Inc. , based in Malvern, PA, USA, competes through ePort and related cashless payment devices, vending management software, and connected solutions for vending, micro-markets, and unattended retail, with a strong emphasis on real-time analytics and operational visibility. Recent industry reporting also highlighted Cantaloupe's significant installed base and its leadership in documenting cashless and contactless transaction trends.
Worldwide Vending Machine Payment System Market
Crane Payment Innovations (CPI) , operating in the USA as part of Crane Co., remains a leading provider of cashless payment systems, card readers, and telemetry, including mobile wallet solutions and integration pathways for existing hardware. Azkoyen Group , including Coges, based in Navarre, Spain, develops payment systems, coin mechanisms, and telemetry solutions integrated into vending machines, offering cashless and connected offerings for global operators. European and global specialists further expand the competitive field: Vendon , headquartered in Estonia, focuses on cashless payment terminals, telemetry, and IoT solutions that enable remote monitoring and mobile payments; Televend (INTIS) , with global operations centered in Europe, provides T-Pay cashless devices and T36 telemetry hardware aimed at modernizing legacy machines with real-time data, AI-enabled tools, and dynamic pricing capabilities; and Ingenico , based in France with global reach, supplies adaptable payment terminals and unattended payment systems including contactless solutions suited to vending environments.
Additional players extend the ecosystem into specialized niches. 365 Retail Markets , based in the USA, delivers PayPlus card readers and cashless solutions integrated with micro-markets and vending, supporting credit, debit, and mobile wallets. Heartland (Global Payments) , USA-based, provides secure cashless payment systems and card readers tailored for unattended vending, laundromats, and similar self-service environments. Apriva , also USA-based, delivers self-service payment processing, devices, and connectivity platforms that extend beyond vending into EV charging and unattended retail. HID Global , with US headquarters and global operations, supplies RFID and contactless payment readers and modules for integration into vending machines and kiosks, supporting cashless and credential-based transactions. Gantner , based in Austria, offers RFID/NFC cashless payment terminals designed for snack and drink vending, enabling membership or employee card payment models.
This competitive mosaic matters because procurement decisions are increasingly evaluated on total operational value rather than terminal price alone. Operators and OEMs weigh telemetry integration, analytics readiness, remote management capabilities, compliance support, and ecosystem compatibility. The full report provides detailed company profiling, strategic positioning analysis, and recent development tracking to support competitive benchmarking and partner selection.
Regulatory, Security, and Operational Dynamics
Payment system strategy cannot be separated from compliance and risk management. As vending machines handle cardholder data, they must align with PCI DSS requirements for secure storage, processing, and transmission of payment information. Shared responsibility models become especially relevant when machines are operated by third parties, making contractual clarity and technical architecture decisions central to risk exposure. Industry analyses suggest that PCI DSS compliance costs for larger organizations can range from 50,000 to 200,000+ USD annually when audits and related controls are included, while smaller entities using self-assessment questionnaires may face annual costs in the 5,000 to 20,000 USD range. Non-compliance penalties can escalate quickly, with reported potential penalties reaching 100,000 USD per month in certain circumstances. These financial and operational stakes make compliance-ready design a strategic priority rather than a backend checkbox.
In parallel, regional regulatory nuances are shaping transaction flow design. Contactless payments at vending machines often qualify for exemptions from Strong Customer Authentication under EU regulations for low-value or unattended terminals, enabling faster tap-and-go transactions without PIN entry. This exemption supports the broader consumer demand for speed and convenience, while also influencing terminal configuration, transaction routing, and regional deployment strategies. The interplay between regulation, user experience, and fraud-risk management is a recurring theme in the study, particularly for firms operating across multiple jurisdictions.
Strategic Value for 2026 Decision-Making
The 2026–2032 forecast window is not merely a planning horizon; it is a period in which legacy modernization, contactless standardization, telemetry adoption, and compliance readiness will separate scalable operators from those burdened by fragmented systems and manual workflows. Our research is designed to support several high-value decision contexts:
- Capital allocation and fleet modernization planning: Understanding where connected payment systems deliver the strongest operational return, including downtime reduction, remote monitoring, and predictive maintenance benefits.
- Payment technology roadmap prioritization: Evaluating the balance between contactless NFC and mobile wallet readiness, card reader continuity, and emerging QR or digital currency pathways based on vertical and regional fit.
- Competitive positioning and partnership strategy: Mapping incumbent capabilities, installed base dynamics, and ecosystem differentiation to inform supplier selection, OEM integration, and service partnership decisions.
- Compliance and risk architecture: Incorporating PCI DSS considerations, shared responsibility structures, and regional authentication rules into terminal selection and deployment planning.
- Market entry and expansion sequencing: Aligning regional demand signals, vertical adoption patterns, and infrastructure readiness with realistic growth pathways rather than aggregated global assumptions.
The study integrates historical performance, forward projections, segmentation analysis, company profiling, and regulatory context into a single decision-support framework. Importantly, it avoids treating the market as a single average growth curve. Instead, it isolates where value is being created, which payment modalities are gaining traction, and how operators and manufacturers are translating technology adoption into measurable efficiency and revenue gains.
What the Full Study Delivers
Beyond the macro trajectory and competitive context summarized here, the complete Worldwide Vending Machine Payment System Market report provides operational depth designed for strategy, finance, product, and sales leadership. The analysis covers market sizing and forecast architecture across the 2020–2032 window, payment-type dynamics, end-use vertical deployment characteristics, and regional demand patterns. It also includes company profiles, recent development tracking, and concentration analysis to support competitive intelligence and partnership evaluation.
The report is structured to translate market movement into actionable insight. For vending operators, it supports fleet upgrade timing, payment method mix decisions, and telemetry investment priorities. For payment system suppliers and OEMs, it clarifies integration opportunities, vertical-specific requirements, and differentiation levers in a consolidating landscape. For investors and strategic planners, it provides a structured view of growth drivers, compliance overhead, and competitive density.
Transportation Ticket Vending Machine (TVM) Market
Conclusion: From Contactless Adoption to Strategic Advantage
The Worldwide Vending Machine Payment System Market is moving from rapid adoption to refined differentiation. Contactless and mobile wallet acceptance have become the operational norm, telemetry has turned payment terminals into management platforms, and regulatory frameworks have elevated compliance from a technical requirement to a strategic design constraint. In this environment, the organizations that outperform will be those that treat payment infrastructure as an integrated capability spanning hardware, software, data, security, and customer experience.
This research study is intended to give leadership teams the clarity required to act with confidence in 2026 and beyond. The headline trajectory, competitive dynamics, and operational pressures are visible here; the detailed segmentation breakdowns, regional revenue contours, end-use profitability context, and proprietary benchmarking are developed fully in the report itself. For executives responsible for unattended retail strategy, payment ecosystem planning, or vending fleet modernization, the complete study provides the granularity needed to convert market momentum into disciplined, high-conviction decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Vending Machine Payment System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com