

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Light Guides Market to Reach $4,521.81M by 2032 at 8.42% CAGR

Lighting the Path Forward: Strategic Intelligence for the Global Light Guides Market 2026–2032
The worldwide light guides market stands at a critical inflection point. Driven by rapid advancements in display technologies, automotive lighting architectures, and precision medical instrumentation, optical transmission components have evolved from passive hardware elements into strategic enablers of product differentiation and performance optimization. For executives navigating capital allocation, supply chain redesign, and product roadmap planning in 2026, the market presents both high-opportunity growth corridors and complex structural shifts that demand granular, actionable intelligence. Our newly released Worldwide Light Guides Market research report delivers the comprehensive analytical framework required to turn these dynamics into informed corporate strategy.
Drawing on a five-year historical baseline and a seven-year forward projection, this study maps revenue trajectories, material substitution patterns, competitive repositioning, and regional manufacturing realignments that will shape procurement, engineering, and market entry decisions throughout the decade. Rather than offering surface-level aggregates, the report is engineered to support cross-functional decision-making across R&D, operations, sourcing, and corporate strategy.
Macro Trajectory and Structural Growth Signals
The market has demonstrated consistent expansion over the past half-decade, with revenue scaling from a baseline of approximately $1.72 billion in 2020 to an estimated $2.57 billion by 2025. This historical momentum establishes a credible platform for the forecast period, during which the market is projected to reach $2.85 billion in 2026 and continue climbing toward $4.52 billion by 2032. The implied compound annual growth rate of 8.42 percent reflects sustained demand pull across multiple end-use verticals, compounding the effects of technological upgrades and capacity additions already underway.
Several interconnected forces underpin this trajectory. Edge-lit illumination architectures continue to benefit from miniaturization requirements in consumer-facing devices, while automotive OEMs push toward adaptive interior and exterior lighting that relies on high-efficiency light guide plates and molded optical components. At the same time, industrial and medical applications are expanding their reliance on specialty light guides for precision illumination, spectroscopy, and minimally invasive instrumentation. These demand drivers are reinforcing volume growth while simultaneously elevating performance thresholds around uniformity, thermal tolerance, and wavelength-specific transmission.
Linear Guide Market
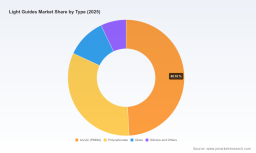
The forward outlook is further shaped by material dynamics that directly influence manufacturing economics and sourcing strategies. Optical-grade acrylic (PMMA) remains the dominant material foundation for light guide plates due to its combination of clarity and cost efficiency, while polycarbonate maintains a meaningful position where heat resistance and impact durability are non-negotiable. Recent analyst observations highlight that polycarbonate pricing in Asia exhibited relative stability through late 2025, with early-2026 FOB benchmarks around $1,876 per metric ton in China and $1,622 per metric ton in India. Meanwhile, PMMA raw material pricing experienced notable volatility across a twelve-month window, creating planning complexity for producers dependent on predictable input costs. These price behaviors are not abstract macroeconomic footnotes; they are direct inputs to margin modeling, vendor negotiations, and inventory strategy.
At the same time, the display sector introduces a structural substitution dynamic that warrants close monitoring. Broader adoption of OLED technologies in premium devices has begun to reduce demand for certain light guide plate applications, while a meaningful share of high-performance laptops has shifted toward OLED alternatives. This transition does not negate the light guides opportunity; rather, it sharpens the focus on where light guides retain a decisive cost, performance, or design advantage, including edge-lit backlighting, signage, and specific automotive interior configurations. Understanding the precise boundaries of substitution is essential for accurate volume forecasting and product portfolio planning.
Competitive Landscape: Scale, Focus, and Strategic Reinvestment
The market exhibits moderate concentration, with the top three participants accounting for a combined share of approximately 34.28 percent and the top five exceeding 51.92 percent. This structure indicates a landscape where established manufacturers hold meaningful scale advantages in mainstream optical components, while specialized and regional players compete on customization, rapid prototyping, and application-specific engineering. For procurement teams and strategy leaders, this implies a bifurcated vendor ecosystem in which commodity segments increasingly reward scale and integration, whereas high-performance segments reward technical collaboration and process capability.
Worldwide Light Guides Market
Leading incumbents are actively reinforcing their competitive positions through targeted investments. SCHOTT AG continues to advance flexible glass optical fiber light guides, bundles, cables, and assemblies tailored for medical, industrial, and electronics applications. The company's PURAVIS® fiber platform emphasizes high transmission and customization to nanometer tolerances, and its recent production expansion includes bioburden-controlled ISO 7/8 cleanroom services in Mexico to support complex light guide assemblies for medical use. Lightguide International is strengthening its specialty optical fiber and laser delivery capabilities, expanding optical fiber production lab capacity to support scientific, industrial, and medical applications across a span of continents, with full custom development from prototype through mass production. Global Lighting Technologies remains positioned around custom molded LED-based edge-lit light guides and light guide plates, leveraging advanced micro-optical extraction methods for uniform illumination across consumer electronics, automotive, and general lighting applications, with multiple manufacturing facilities in Asia and additional capacity in Vietnam.
Parallel activity among regional and application-focused suppliers adds important texture to the competitive map. Astra Products supports edge-lit displays and backlighting through CLAREX acrylic light guide panels, light guide reflectors, and high scatter optical transmission light guides, complemented by custom printing and finishing options. Yongtek manufactures light guide plates from acrylic and polystyrene using extrusion, silk printing, and laser methods for LED lighting, displays, automotive interiors, and signage. Thorlabs contributes to the scientific and laboratory segment with liquid light guides designed for broad wavelength transmission, while RSP, Inc. supplies custom light guide films for LED backlighting in compact consumer products. Nanjing Giant Technology rounds out the competitive field with plastic and glass optical fiber light guides, including ring light guides and custom bundles for non-communication illumination uses.
Strategic developments in late 2025 reinforce the theme of deliberate capability expansion and product repositioning. HOYA Corporation signaled a move toward targeting light guides for AR glasses as a next step following its camera lens focus, illustrating how optical specialists are extending core competencies into near-eye display architectures. Global Lighting Technology's detailed guidance on custom optical pattern application methods for acrylic and polycarbonate light guide plates, including micro-machined mirror-finished structures, underscores the ongoing engineering emphasis on illumination uniformity and structural precision. Taken together, these moves suggest that competition is increasingly defined by process control, application integration, and geographic diversification.
Regulatory Friction and Supply Chain Reconfiguration
The operating environment is being reshaped as much by policy and trade dynamics as by technology roadmaps. U.S. tariffs imposed in early 2025 on imported components from major manufacturing hubs have prompted a broad reassessment of sourcing strategies and accelerated exploration of near-shoring alternatives for light guide plates, particularly within the automotive sector. For global manufacturers, this creates a dual challenge: maintaining cost competitiveness while building or qualifying supply options that reduce exposure to border friction and currency volatility. The result is a market in which geographic diversification, supplier redundancy, and regional manufacturing footprints are becoming strategic imperatives rather than optional contingency measures.
These trade-driven pressures intersect with material sourcing considerations. As regional price behavior diverges and production capacity is rebalanced, firms that rely on single-source input dependencies or concentrated manufacturing locations face elevated risk. The report examines how these dynamics affect lead times, qualification cycles, and total cost of ownership, providing executives with the analytical scaffolding to evaluate make-versus-buy decisions, dual-sourcing structures, and regional capacity investments with greater precision.
Inside the Worldwide Light Guides Market Research Report
This research is designed to translate market complexity into decision-ready intelligence. The study opens with comprehensive market sizing and forecast modeling that links historical performance to forward projections, allowing leadership to benchmark current performance against top-down opportunity ranges and scenario-based growth paths. Segmentation analysis dissects demand across material types and application domains, revealing where optical performance requirements, cost sensitivities, and substitution risks converge. Regional evaluations provide a structured comparison of demand intensity, manufacturing presence, and trade exposure, helping teams prioritize market entry, expansion, or sourcing shifts with confidence.
Beyond sizing, the report delivers practical operability through several integrated sections. A competitive profiling module maps the strategic positioning, capability strengths, and recent investments of leading participants, enabling benchmarking against internal development roadmaps and supplier evaluation criteria. A raw material and cost dynamics section contextualizes input pricing behavior, substitution economics, and planning implications for producers and buyers alike. A regulatory and trade impact analysis identifies policy-driven risks and near-shoring incentives that may influence procurement strategy, capacity placement, and contract structures over the forecast horizon.
The report also integrates recent corporate developments to illustrate how strategic intent is translating into tangible capability changes. Whether it is cleanroom expansion for medical assemblies, production lab capacity increases for specialty fiber systems, or product-level enhancements in micro-optical patterning, these developments are interpreted within a broader framework of competitive advantage and supply reliability. This approach ensures that executives do not merely observe industry events, but understand their implications for sourcing resilience, technology readiness, and time-to-market.
Why This Research Matters for 2026 Decision-Making
In a market growing at a sustained mid-to-high single-digit compound rate, strategic advantage accrues to organizations that can couple demand visibility with operational agility. The light guides sector is not defined by a single dominant application or material; rather, it is shaped by overlapping transitions in display formats, automotive lighting requirements, medical device sophistication, and regional manufacturing economics. Decision-makers must therefore answer a set of interrelated questions: where does growth concentrate by application and geography, which material substitutions will persist versus plateau, how should sourcing portfolios be restructured in response to trade policy, and which competitors are most likely to shape pricing and capacity dynamics in each segment.
This report is built to help leadership teams answer those questions with rigor. It provides the analytical foundation to align R&D roadmaps with realistic substitution boundaries, to inform procurement strategies that balance cost efficiency with supply resilience, and to evaluate potential partnerships, acquisitions, or capacity investments against credible market trajectories. The study's forecast architecture, segmentation logic, and competitive mapping are intended to support scenario planning, allowing organizations to test assumptions around demand sensitivity, input cost volatility, and regulatory exposure before committing capital or redesigning product architectures.
For executives seeking to move beyond intuition and into structured strategic planning, the essential next step is access to the full analytical detail that underpins these conclusions. The complete Worldwide Light Guides Market research report presents the internal data tables, segment breakdowns, regional comparisons, and competitive profiles necessary to operationalize the insights summarized here. We invite you to explore the full report to obtain the granular intelligence required to align your organization's next planning cycle with the market's most consequential developments.
For detailed analysis of this topic, please visit the official page: Worldwide Light Guides Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com