

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Industrial High Res Camera Market Hits $1.54B in 2025, Projects 8.28% CAGR to 2032

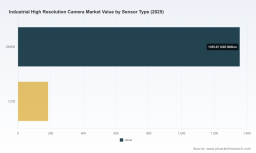
Worldwide Industrial High Resolution Camera Market: Strategic Intelligence for 2026 Decision-Making
The industrial imaging landscape is undergoing a structural transformation. As manufacturing systems grow more digitized, inspection requirements become more stringent, and automation architectures demand higher fidelity data capture, high resolution cameras have moved from peripheral components to critical enabling technologies. PW Consulting’s latest Worldwide Industrial High Resolution Camera Market study provides a comprehensive, forward-looking assessment of this rapidly evolving sector, designed specifically to equip leadership teams with the analytical rigor required for confident 2026 strategic planning.
This research does not merely catalog historical performance. It constructs a decision-ready framework that maps revenue trajectories, competitive positioning, technological inflection points, and supply chain pressures across a forecast horizon extending through 2032. The following overview illustrates the depth and operational utility embedded within the full report, while preserving the precise segmentation data, regional breakdowns, and proprietary modeling outputs that subscribers will access in the complete intelligence package.
Macro Trajectory and Revenue Architecture
The global industrial high resolution camera market has demonstrated consistent expansion across the historical review period, with total revenue climbing from approximately 1,045 million USD in 2020 to an estimated 1,540 million USD in 2025. This growth reflects sustained capital investment in automated visual inspection, precision metrology, and advanced manufacturing platforms that require imaging systems capable of resolving fine structural details at production-line speeds.
Looking ahead, the market is projected to advance to 1,715 million USD in 2026 and continue its upward trajectory toward 2,687 million USD by 2032. The forecast period compound annual growth rate of 8.28 percent underscores a sector that is expanding faster than many adjacent industrial automation categories. This rate is not uniform across all vectors; rather, it is shaped by divergent adoption curves, regional industrial policy shifts, sensor technology transitions, and the pace at which end-use sectors integrate higher-resolution imaging into routine quality and process control workflows.
Several structural forces explain this momentum:
- Increasing defect-detection sensitivity requirements in electronics and semiconductor fabrication, where sub-pixel feature resolution directly correlates with yield improvement and waste reduction.
- The migration from legacy CCD architectures toward high-performance CMOS platforms, driven by improvements in quantum efficiency, read noise reduction, power efficiency, and integration flexibility.
- Expanding deployment of high-speed line-scan and area-scan configurations in continuous-motion manufacturing environments, where frame-rate and resolution must scale together without compromising throughput.
- Growing integration of vision subsystems into broader automation ecosystems, including robotic guidance, volumetric measurement, and inline metrology stations that depend on deterministic image acquisition.
The full study dissects these drivers through multi-axis modeling that isolates the contribution of each segment while maintaining a cohesive view of total market momentum. Decision-makers will find that the aggregate figures tell only part of the story; the actionable intelligence lies in understanding which technology pathways, application domains, and geographic clusters are accelerating, which are plateauing, and why.
Competitive Landscape: Positioning Among Established and Emerging Players
The competitive architecture of the industrial high resolution camera market is characterized by a blend of specialized imaging manufacturers, diversified machine vision conglomerates, and regional suppliers leveraging localized manufacturing and distribution advantages. The report provides detailed company profiles, capability mapping, and strategic assessment for the leading organizations shaping the market’s direction.
European suppliers maintain a strong presence through product breadth and application engineering depth. Basler AG offers a wide portfolio of industrial high-resolution area-scan and line-scan cameras with CMOS sensors reaching up to 65 megapixels, supported by GigE, USB3, and CoaXPress interfaces for machine vision, factory automation, and inspection applications. Allied Vision Technologies specializes in high-resolution 2D, 3D, and SWIR cameras for industrial automation, semiconductor inspection, and medical imaging, with an emphasis on smart vision systems and high-performance CMOS sensors. JAI A/S focuses on multi-sensor and high-resolution industrial cameras, including prism-based color models, for machine vision, automation, and surface inspection applications. Baumer manufactures high-performance CMOS industrial cameras with resolutions up to 65 megapixels, supporting GigE Vision, USB3 Vision, and Camera Link for precision measurement and automation.
North American firms contribute significant innovation in ultra-high-speed and high-resolution architectures. Teledyne DALSA provides high-resolution machine vision cameras, including area-scan and line-scan models with advanced CMOS sensors for electronics, semiconductor, and industrial inspection. Emergent Vision Technologies develops ultra-high-speed, high-resolution cameras reaching more than 100 megapixels with 10GigE, 25GigE, and 100GigE interfaces, including Zenith series models for industrial automation and volumetric imaging. Lucid Vision Labs offers Triton and Phoenix series GigE and high-resolution machine vision cameras with IP67-rated options for industrial environments and OEM integration. Adimec specializes in high-resolution cameras optimized for metrology, semiconductor wafer inspection, and electronics inspection with active sensor control features. Vision Systems Technology supplies ultra-high-resolution cameras leveraging advanced CMOS sensors for precision industrial imaging and inspection. Cognex Corporation develops smart machine vision cameras and systems with high-resolution capabilities for industrial inspection and quality control.
Asia-Pacific participants are increasingly influential in expanding price-performance options and scaling supply capacity. Daheng Imaging provides industrial cameras, optical systems, and high-resolution imaging solutions for automation and machine vision applications. Huaray Tech manufactures high-speed and high-resolution industrial cameras for various automation and imaging applications. Omron Corporation integrates high-resolution vision systems and cameras into automation solutions for industrial manufacturing and inspection.
The report evaluates each company across multiple strategic dimensions: sensor integration capability, interface roadmap alignment, application-specific validation, OEM partnership models, and capacity to manage supply chain volatility. This competitive profiling enables clients to benchmark their own product strategy, identify partnership or acquisition targets, and anticipate market share shifts as technology and regional cost structures evolve.
Recent Product and Technology Developments Shaping 2026 Investment
Innovation velocity in this sector has accelerated markedly over the past twelve to eighteen months. The study incorporates a structured review of recent launches and component-level advances that are reshaping performance ceilings and integration economics.
Worldwide Industrial High Resolution Camera Market
In September 2025, Emergent Vision Technologies released five new models in the ZENITH 100GigE camera series based on Sony Pregius S sensors, offering up to 105 megapixel resolution and frame rates exceeding 800 fps for industrial automation applications. This launch illustrates the ongoing convergence of extreme resolution and extreme data throughput, raising the bar for infrastructure planning in high-speed inspection environments.
STMicroelectronics advanced its sensor portfolio in October 2025 with four new 5-megapixel CMOS image sensors in the ST BrightSense family, featuring hybrid global and rolling shutter modes for industrial automation, machine vision, and robotic applications, with mass production scheduled for February 2026. Such component-level releases influence downstream camera design cycles, cost structures, and the timing of new product introductions across multiple manufacturers.
AT Sensors launched the C7 triangulation camera series for high-speed industrial 3D scanning in March 2026, delivering up to five times higher data throughput with 3072 pixels per profile for inline inspection tasks. This development highlights the growing demand for high-resolution 3D profiling that can operate within tight cycle-time constraints.
SinceVision Technology announced its 2026 lineup in December 2025, including high-speed cameras up to 5K and 21-megapixel resolution alongside 3D laser profilers for high-precision industrial inspection in smart manufacturing. These successive product announcements indicate that suppliers are not only competing on resolution alone but also on the integration of speed, robustness, and application-tuned optical performance.
The full report situates these developments within a broader technology roadmap, enabling clients to distinguish between incremental specification improvements and step-change innovations that could alter procurement strategies, system architecture choices, or competitive differentiation timelines.
Supply Chain Pressures and Regulatory Dynamics
Strategic planning for 2026 cannot ignore the operational realities affecting sensor procurement, component pricing, and cross-border trade. The research integrates recent industry intelligence on cost and availability pressures that are directly influencing manufacturing schedules and margin management across the industrial camera sector.
U.S. imposition of tariffs on imported semiconductors and related components has increased production costs for machine vision systems by an estimated 8 to 12 percent in affected supply chains. This cost pressure is not uniformly distributed; it varies by sourcing strategy, bill-of-materials composition, and the extent to which manufacturers can reallocate procurement or adjust assembly locations.
Semiconductor shortages and extended component lead times for CMOS image sensors have constrained production schedules for industrial camera manufacturers. Even as certain bottlenecks ease, the timing and reliability of sensor availability remains a critical variable for companies planning product launches, capacity expansion, and customer commitments.
In parallel, rising costs of silicon wafers and specialized materials for CMOS sensor fabrication continue to pressure manufacturing expenses in the industrial camera sector. These input-cost dynamics affect not only sensor pricing but also the broader economics of upstream fabrication, which can cascade into lead-time variability and negotiation leverage for downstream camera builders.
Regulatory complexity adds another layer of strategic risk. U.S. export controls on advanced computing commodities to China include case-by-case licensing for certain AI-related chips below specific performance thresholds, impacting broader electronics and imaging supply chains. While the direct scope of these controls varies, their presence alters planning assumptions for manufacturers with cross-border component flows, distribution networks, or end-market exposure. The complete report analyzes how these regulatory and supply chain factors interact with regional demand patterns and competitive sourcing options.
Application Landscape and Technology Transition
The industrial high resolution camera market serves a diverse set of end-use domains, each with distinct performance requirements, inspection tolerances, and adoption cycles. Semiconductor and electronics manufacturing continues to be a major demand center, where high spatial resolution and stable repeatability support wafer-level inspection, component verification, and advanced packaging quality control. Automotive manufacturing relies on high-resolution imaging for surface defect detection, assembly verification, and increasingly for guided processes that depend on precise visual feedback. Pharmaceuticals and medical applications demand imaging systems capable of supporting stringent documentation, cleanliness, and metrology expectations. Logistics and packaging operations utilize high-resolution cameras for label reading, code verification, dimensioning, and automated sorting where throughput and reliability must remain balanced. Additional application areas extend into surface inspection, robotics integration, and specialized metrology tasks that require tailored optical configurations.
Across these domains, the transition toward CMOS-based sensors is a defining strategic theme. CMOS architectures are increasingly favored for their improved integration potential, lower power consumption, and expanding performance envelope that continues to narrow the gap with traditional CCD solutions in many industrial scenarios. Nevertheless, the report emphasizes that sensor selection is not a simple binary decision. The appropriate imaging architecture depends on resolution targets, exposure conditions, frame-rate requirements, noise tolerance, interface constraints, and total system cost. The study provides a structured evaluation of these trade-offs so that engineering and procurement teams can align technology choices with application realities rather than specification-marketing alone.
Regional Dynamics and Strategic Sourcing Considerations
Regional market structure plays a decisive role in how industrial high resolution camera demand evolves, how competition is organized, and how supply chain risk is managed. Manufacturing density, automation investment cycles, local content expectations, and trade policy all influence the geography of opportunity. The report examines regional demand patterns and supplier distribution without reducing the analysis to static share percentages, because the strategic value lies in understanding momentum, dependency, and transition points rather than snapshot figures alone.
In regions with intensive electronics and semiconductor manufacturing, demand is closely tied to fab expansion, packaging complexity, and inspection automation programs. In automotive and heavy manufacturing centers, adoption is shaped by line modernization schedules, quality-program mandates, and the availability of skilled integration partners. In healthcare and pharmaceutical environments, procurement is influenced by compliance requirements, validation cycles, and the need for imaging solutions that can operate reliably within tightly controlled processes. Across all regions, the interplay between local suppliers and globally active manufacturers affects pricing, customization depth, support responsiveness, and supply continuity.
The full study provides a decision-oriented regional analysis that helps clients evaluate where to prioritize sales efforts, how to structure distribution partnerships, and which sourcing strategies best balance cost, performance, and risk in an environment where trade policy and component availability can shift material outcomes within a single planning cycle.
How This Study Supports 2026 Decision-Making
PW Consulting’s Worldwide Industrial High Resolution Camera Market research is built for executive, product, sales, and supply chain teams that need more than high-level trend commentary. The report is structured to support concrete decisions in several areas:
- Portfolio planning: Identify which resolution tiers, sensor technologies, and interface configurations are gaining adoption momentum and which are facing substitution or saturation risk.
- Competitive positioning: Assess how major players differentiate through resolution ceilings, speed performance, environmental robustness, OEM integration support, and application-specific validation.
- Sourcing and supply continuity: Incorporate sensor availability, input-cost trends, tariff exposure, and export-control considerations into procurement and manufacturing plans.
- Market entry and expansion: Evaluate regional demand intensity, application mix, and competitive thickness to prioritize investment and partnership strategies.
- Product roadmap alignment: Use recent product launches and sensor-component advances to anticipate customer expectations and infrastructure requirements for next-generation systems.
Each section of the report is designed to link market evidence to operational consequences. Rather than presenting the market as a single growth narrative, the analysis isolates the segments, technologies, and competitive dynamics that will determine which companies capture share efficiently and which face margin compression, capacity constraints, or misalignment with end-user requirements.
What the Full Report Delivers
The complete Worldwide Industrial High Resolution Camera Market study provides a unified analytical structure that combines historical performance review, forecast modeling, segmentation analysis, competitive profiling, technology assessment, and supply chain context. Subscribers gain access to detailed company evaluations, structured recent-developments tracking, and decision frameworks that translate market signals into planning actions. The research is intended to support scenario testing, investment prioritization, product strategy refinement, and competitive benchmarking across the 2026 to 2032 horizon.
Access the Complete Strategic Intelligence
This overview has highlighted the scope, methodological rigor, and decision-relevant content embedded in the full study. To obtain the complete segmentation intelligence, regional analysis, company benchmarking, and forecast detail required for precise 2026 planning, access the full PW Consulting report through our official market research portal. The complete package is structured for immediate use by strategy, R&D, procurement, and commercial leadership teams seeking a reliable foundation for industrial high resolution camera market decisions.
Industrial Cameras Market
For detailed analysis of this topic, please visit the official page: Worldwide Industrial High Resolution Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com