

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Protein Resin Market Hits $11.5B in 2025 with 9% CAGR Through 2032

Strategic Intelligence for the Protein Purification Resin Market: Navigating Growth Through 2032
The global landscape for protein purification resins is entering a phase of accelerated transformation, driven by complex bioprocessing demands, evolving therapeutic modalities, and intense competitive innovation. As enterprises formulate their strategic roadmaps for 2026 and beyond, the need for precise, forward-looking intelligence has never been more critical. This newly released Worldwide Protein Purification Resin Market research provides a comprehensive diagnostic of market architecture, competitive dynamics, and growth trajectories, offering decision-makers the analytical rigor required to capitalize on emerging opportunities while mitigating supply chain and regulatory risks.
Macro Market Architecture and Growth Trajectories
The market has demonstrated consistent upward momentum over the historical evaluation period, expanding from a baseline of approximately USD 7,450.2 million in 2020 to a projected valuation of USD 11,463.05 million by 2025. This trajectory reflects the compounding impact of biopharmaceutical scaling, increased biologics production volumes, and the maturation of downstream processing technologies. Looking ahead, the forecast horizon through 2032 underscores a sustained growth curve, with the market anticipated to surpass the USD 20,000 million threshold by the close of the decade. The compound annual growth rate across the forecast period stands at 9.0%, signaling a robust expansion phase that outpaces many adjacent life sciences material segments.
This growth is not linear; it is punctuated by periodic inflection points tied to technological breakthroughs, regulatory shifts, and the commercialization timelines of next-generation therapeutics. Strategic planners must recognize that volume expansion alone does not guarantee margin preservation. The interplay between resin pricing dynamics, ligand economics, and manufacturing scale efficiency will dictate which organizations capture disproportionate value as the market matures. Understanding the temporal distribution of this growth—where demand accelerates, where capacity constraints emerge, and where substitution risks materialize—is foundational to capital allocation and R&D prioritization.
Core Industrial Dynamics and Structural Pressures
Several interconnected forces are reshaping the competitive environment and operational calculus for protein purification resin stakeholders. First, raw material architecture continues to anchor procurement strategies and performance benchmarks. Agarose-based matrices remain the dominant foundation for large-scale bioprocessing applications, with cross-linked agarose retaining strong preference due to its established biocompatibility profile and extensive regulatory history. This material continuity provides downstream developers with predictability, yet it also concentrates supply chain dependencies among specialized matrix producers and creates barriers for alternative polymer-based innovations seeking to displace incumbent chemistries.
Second, cost economics around Protein A ligands and resin pricing remain a persistent pressure point. Historical pricing ranges for affinity resins have consistently operated in high-value territory, reflecting the specialized ligand synthesis, coupling complexity, and performance validation required for regulated manufacturing. This economic reality is catalyzing a dual response: manufacturers are investing heavily in higher dynamic binding capacity formats and reusable resin architectures to amortize costs across more purification cycles, while end-users are scrutinizing total cost of ownership models that factor in resin lifetime, cleaning validation, and process robustness.
Third, the regulatory environment introduces a layer of structural discipline. Chromatography resins deployed in compliant biopharmaceutical manufacturing operate under stringent change control protocols and documented regulatory pathways. Any shift in sourcing, material substitution, or process optimization must navigate validation requirements to preserve GMP compliance. This regulatory moat favors established suppliers with comprehensive documentation packages and long-term stability records, while simultaneously raising the compliance burden for organizations pursuing rapid material swaps or experimental resin formats.
Competitive Landscape and Strategic Positioning
The market exhibits a concentrated structure, with a handful of multinational life sciences and specialty materials players commanding a substantial share of global revenue. This concentration reflects the capital intensity of resin development, the value of established manufacturing scale, and the importance of integrated technical support for process-scale customers. The competitive field is anchored by organizations that span diverse capabilities—from high-capacity affinity platforms and ion exchange media to membrane-integrated downstream systems and analytical-to-preparative chromatography columns.
Key participants shaping the market include Danaher Corporation (Cytiva), Merck KGaA (MilliporeSigma), Repligen Corporation, Thermo Fisher Scientific, Ecolab (Purolite Life Sciences), Bio-Rad Laboratories, Tosoh Corporation (Tosoh Bioscience), Sartorius AG, Agilent Technologies, GenScript Biotech, Bio-Works Technologies AB, Marvelgent Biosciences, and JSR Life Sciences. These entities compete along multiple vectors: resin selectivity and dynamic binding performance, bead morphology and flow dynamics, scalability across clinical and commercial volumes, cost efficiency for biosimilar and second-generation drug programs, and the breadth of downstream workflow integration. Geographic diversification also plays a role, with headquarters spanning the United States, Germany, Japan, China, and Sweden, reflecting a globally distributed manufacturing and service footprint.
The market structure implies that competitive advantage will increasingly derive from differentiation in performance-per-dollar rather than pure volume pricing. Suppliers that can demonstrate superior resin longevity, reduced ligand leaching, faster cycle times, and seamless integration with automated downstream processing platforms will be better positioned to defend margins and secure long-term procurement commitments from biologics manufacturers.
Innovation Cadence and Product Evolution
Recent activity across the competitive field highlights a clear strategic priority: delivering next-generation resin formats that address the dual mandates of higher performance and lower cost of ownership. During the past year, several launches have targeted the expanding needs of monoclonal antibody purification, viral vector processing, and biosimilar-scale manufacturing. Repligen introduced next-generation AVIPure HiPer AAV9 and AAV8 affinity resins, alongside a HiPer QA anion exchange resin built on its Tantti DuloCore base bead technology, extending the toolkit for viral vector and new modality purification. Ecolab advanced its Purolite AP+50 Protein A chromatography resin with a 50-micron bead size designed to improve dynamic binding capacity, cost efficiency, and yield in biosimilar and large-scale mAb production. Danaher's Cytiva expanded its MabSelect family with MabSelect SuRe 70 and MabSelect PrismA X Protein A resins, targeting enhanced productivity and affordability at clinical and commercial scales. Bio-Works Technologies added WorkBeads affimAb Edge, a premium Protein A resin optimized for monoclonal antibody purification workflows.
These launches are not isolated product announcements; they are indicative of a broader innovation tempo focused on bead engineering, ligand stabilization, binding kinetics, and process economics. The emphasis on improved capacity and reusability directly responds to the pricing and cycle-cost pressures noted earlier, while modality-specific formats reflect the diversification of the therapeutic pipeline beyond conventional antibodies. Organizations evaluating their resin portfolio strategy should assess how these innovations alter the performance baseline for their internal purification workflows and whether incremental capability gains justify procurement transitions or process redevelopment.
Report Scope and Decision-Ready Content
Our Worldwide Protein Purification Resin Market research is designed to translate complex market signals into actionable strategic guidance. The report provides a multi-dimensional evaluation of market size, growth rates, and segmentation architecture across technology types, application domains, and regional markets. Beyond high-level sizing, the analysis delves into the structural drivers that shape demand intensity, the competitive tactics that influence supplier selection, and the operational variables that determine total cost of ownership for end-users.
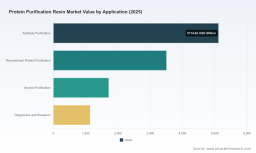
The content framework encompasses a detailed segmentation review that maps demand distribution across affinity chromatography, ion exchange chromatography, size exclusion chromatography, hydrophobic interaction chromatography, and other resin categories. Application-level analysis isolates the relative importance of antibody purification, recombinant protein purification, vaccine purification, and diagnostics and research workflows, helping leaders understand where value creation is concentrated and where substitution or cross-technology migration may occur. Regional and country-level breakdowns offer comparative context for market maturity, capacity availability, procurement patterns, and growth velocity, enabling more precise allocation of commercial resources and supply chain planning.
In addition, the report evaluates competitive positioning, recent product launches, and strategic maneuvers among leading suppliers, providing a structured lens on how incumbents and challengers are attempting to reshape buyer preferences and lock in long-term demand. Regulatory considerations, material sourcing dependencies, and performance validation requirements are integrated into the analysis to reflect the real-world constraints that shape procurement decisions in regulated bioprocessing environments. The synthesis of these elements allows executives, R&D leaders, and procurement strategists to benchmark internal assumptions against market-wide evidence and to identify the most defensible pathways for capacity expansion, partnership formation, and technology adoption.
Strategic Imperatives for 2026 Decision-Making
As organizations prepare their plans for 2026, several strategic imperatives emerge from the market's trajectory and competitive dynamics. First, demand forecasting must account for modality diversification. While antibody purification continues to represent a major demand anchor, the expansion of viral vector work, recombinant protein programs, and vaccine-related purification requirements is broadening the applicability landscape for chromatography resins. Resins that can address multiple workflows or that can be justified across parallel pipelines may deliver stronger utilization economics and lower vulnerability to single-program demand fluctuations.
Worldwide Protein Purification Resin Market
Second, cost architecture must be evaluated through a lifecycle lens. Given persistent pricing pressures around Protein A ligands and high-capacity affinity formats, procurement strategies that prioritize lowest unit price without considering binding capacity, cleanability, reuse cycles, and downstream process robustness may inadvertently increase total operating expense. Decision-makers should assess whether investments in higher-capacity or more durable resin formats yield net savings when cycle counts, validation overhead, and process downtime are incorporated.
Third, supply resilience and regulatory readiness should be treated as strategic differentiators rather than compliance afterthoughts. As change control requirements and validation burdens remain stringent for regulated manufacturing, suppliers with transparent documentation, consistent batch quality, and credible alternate-sourcing strategies will have an advantage in procurement negotiations. Buyers, in turn, should structure their supplier relationships to preserve continuity while maintaining the flexibility to adopt improved resin architectures as validated pathways allow.
Fourth, geographic expansion and regional capacity dynamics warrant close monitoring. Market growth is distributed across multiple regions, each with distinct maturity profiles, procurement behaviors, and infrastructure constraints. Firms seeking to grow commercial footprint or optimize supply chains should align their regional strategies with local demand intensity, logistical considerations, and the presence of capable manufacturing and technical support ecosystems.
Oligonucleotide Purification Market
Conclusion: From Market Awareness to Strategic Advantage
The Worldwide Protein Purification Resin Market is undergoing a period of pronounced expansion and structural realignment. A nearly decade-long growth trajectory, a high single-digit compound annual growth rate through 2032, and a concentrated competitive field all point to an environment where informed strategy can create durable advantage. Yet the market's complexity—spanning material science, process economics, regulatory compliance, and modality-driven demand shifts—requires more than surface-level intelligence. It demands a rigorous, integrated view of where growth is concentrated, how suppliers are competing, and what operational choices will protect margins and performance quality.
This research report is built to provide that view. It synthesizes sizing, segmentation, competitive dynamics, recent innovation activity, and industrial context into a decision-ready framework for executives and technical leaders. To access the full market size progression, detailed segmentation breakdowns, regional and application-level analysis, and complete competitive profiling, please visit the source webpage for the complete Worldwide Protein Purification Resin Market research. The complete intelligence will equip your team to convert market awareness into disciplined strategic action for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Protein Purification Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com