

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Polyester Coating Market Hits $12.8B in 2025, Poised to Reach $18.5B by 2032

Strategic Imperatives in the Worldwide Polyester Coating Market: Navigating Growth and Complexity Through 2032
The global coatings industry stands at a critical inflection point, where sustainability mandates, regional cost arbitrage, and technological innovation are reshaping competitive dynamics. For executives, procurement leaders, and strategic planners, the Worldwide Polyester Coating Market represents both a foundational input stream and a high-stakes battleground for margin preservation. As we move into the 2026 decision cycle, access to granular, forward-looking intelligence is no longer a luxury—it is a prerequisite for capital allocation, supply chain resilience, and product portfolio optimization.
PW Consulting’s newly released comprehensive market study delivers exactly that intelligence. Spanning historical performance from 2020 through 2025 and projecting through 2032, this report equips decision-makers with a structured, data-rich framework to anticipate demand shifts, evaluate competitive moves, and align operational strategies with macroeconomic realities. Below is a strategic preview of the market landscape, the analytical architecture of the study, and why it matters for your 2026 planning.
Macro Market Trajectory and Structural Momentum
The worldwide polyester coating market has demonstrated consistent expansion over the past half-decade, driven by industrial modernization, infrastructure investment, and the ongoing substitution of solvent-based systems with lower-emission alternatives. Historical data underscores this trajectory: the market generated approximately USD 9.85 billion in 2020 and has accelerated steadily, reaching USD 12.11 billion by 2023. The momentum carried through 2024 to USD 12.37 billion and further to USD 12.83 billion in 2025, reflecting both volume growth and strategic pricing adjustments across key geographies.
Looking ahead, the forecast period from 2026 to 2032 outlines a sustained growth arc. The market is projected to reach USD 13.29 billion in 2026, expanding to USD 14.40 billion by 2027, USD 15.72 billion by 2028, and USD 15.86 billion by 2029. Medium-term projections extend to USD 15.98 billion in 2030, USD 16.80 billion in 2031, and a terminal forecast of USD 18.47 billion by 2032. The compound annual growth rate across the forecast window stands at 5.35 percent, signaling a market that is neither inflationary nor stagnant, but structurally expanding at a pace that rewards proactive positioning.
Polyester Fiber Market
This macro trajectory, however, masks significant underlying variation. Demand concentration, feedstock volatility, regulatory divergence, and capacity deployment cycles all interact to create pockets of accelerated growth and zones of margin pressure. Understanding these dynamics requires more than headline figures—it demands segmentation-level visibility, competitive benchmarking, and scenario modeling that only a structured research framework can provide.
Segmentation Architecture: Applications, Types, and Regional Realities
The study dissects the market across three critical dimensions: application verticals, product types, and geographic regions. Each lens reveals distinct growth vectors, cost structures, and competitive pressures that directly influence sourcing strategy, product development roadmaps, and market entry decisions.
Application Verticals
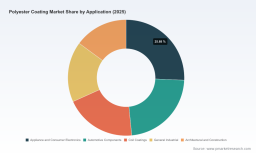
Industrial demand for polyester coatings spans a diverse set of end-use sectors, each with unique performance requirements and procurement cycles. Appliance and consumer electronics manufacturing continues to drive consistent volume, leveraging polyester systems for durability, aesthetic consistency, and regulatory compliance. Automotive components represent another high-value segment, where lightweighting initiatives and corrosion resistance specifications push formulators toward advanced resin architectures. Coil coatings remain a cornerstone application, supporting building envelope manufacturing and industrial metal processing with high-throughput, continuous-line compatibility. General industrial applications provide a broad baseline of demand, while architectural and construction coatings reflect both retrofit cycles and new infrastructure programs.
The report maps revenue contributions, growth rates, and substitution risks across these verticals without exposing sensitive granularity that would dilute strategic focus. Instead, it provides decision-makers with relative weighting, demand elasticity indicators, and forward-looking adoption signals that inform capacity planning and product mix optimization.
Product Type Evolution
The competitive and technological landscape is further shaped by the coexistence of multiple polyester coating formats. Powder polyester coatings have gained structural advantages in regions with stringent VOC regulations and in applications prioritizing overspray recovery and waste reduction. Liquid solvent-borne polyester systems maintain relevance in high-performance industrial and specialty finishes where application flexibility and film properties remain unmatched. Water-borne polyester variants are accelerating in markets where environmental compliance and worker safety standards are tightening. UV-curable and specialized polyester formulations represent a high-margin, technically differentiated niche, often deployed in precision coating, electronics protection, and rapid-cure industrial processes.
Worldwide Polyester Coating Market
Each type carries distinct raw material dependencies, processing requirements, and end-market acceptance curves. The study evaluates these dimensions across the forecast horizon, highlighting where capacity investments are aligning with demand signals and where overcapacity or technological obsolescence risks may emerge.
Regional Demand and Cost Dynamics
Geographic performance is deeply intertwined with feedstock economics, trade policy, and industrial output cycles. The report provides regional revenue baselines and growth trajectories, but deliberately withholds exact percentage splits and localized dollar figures to preserve the analytical premium of the full study. What is clear from the macro distribution is that Asia Pacific commands the largest revenue pool, followed by Europe and North America, with Latin America and the Middle East and Africa representing smaller but strategically evolving markets.
Regional cost structures are increasingly influenced by feedstock divergence. In the United States, purified terephthalic acid (PTA) prices—a critical polyester resin feedstock—reached approximately USD 972 per metric ton in December 2025, with first-half 2026 base-case projections settling in the USD 1,050 to USD 1,200 per metric ton range. Meanwhile, China’s PTA trading levels remained in the USD 614 to USD 750 per metric ton band through late 2025 and early 2026, creating a persistent cost asymmetry that reshapes global resin pricing and exported coating competitiveness. Compounding this dynamic, geopolitical tensions in the Middle East triggered a 3.53 percent weekly increase in U.S. PTA prices in early March 2026, driven by disruptions to crude-derived paraxylene feedstock supply chains.
Regulatory environments further differentiate regional attractiveness. EU policy frameworks continue to accelerate the transition toward low-VOC polyester powder coatings as direct substitutes for solvent-based systems in industrial applications. In parallel, Canadian surtax remission orders have extended coverage for specific aluminum sheets and steel closures with polyester coatings through 2026, directly influencing import costs for coated metal substrates and altering regional procurement economics.
Competitive Landscape and Strategic Positioning
The polyester coating market is characterized by a moderately concentrated competitive structure, with the top three players accounting for approximately 18.45 percent of global revenue and the top five representing roughly 28.3 percent. This fragmentation at the tail end of the market, combined with concentrated leadership at the top, creates a landscape where scale advantages in R&D, capacity utilization, and distribution networks are decisive, yet where regional specialists and technology-focused formulators can compete effectively in niche segments.
Several global incumbents define the strategic center of gravity. PPG Industries, headquartered in Pittsburgh, remains a major global supplier of polyester and powder coatings for industrial, architectural, and coil applications, with a pronounced emphasis on durable, weather-resistant polyester systems. Akzo Nobel N.V., based in Amsterdam, delivers an extensive portfolio of polyester powder and liquid coatings, including its Interpon brand, for architectural, industrial, and protective applications worldwide. Axalta Coating Systems LLC, located in Philadelphia, focuses on polyester-based powder and liquid coatings tailored to industrial, automotive refinish, and performance applications. BASF SE, operating from Ludwigshafen, supplies polyester resins and coatings for powder, industrial, and automotive use, with growing emphasis on sustainable and high-performance formulations. The Sherwin-Williams Company, headquartered in Cleveland, delivers polyester coil and powder coatings, recently expanding coil-line capacity to strengthen its industrial and architectural market footprint.
Additional players reinforce the competitive mosaic. Arkema, based in Colombes, produces polyester resins for powder and liquid systems with a clear focus on sustainable, low-VOC solutions. Huntsman International LLC, from The Woodlands, offers polyester polyols and related components used in high-performance polyurethane-polyester hybrid systems. Jotun A/S, headquartered in Sandefjord, supplies polyester-based protective and architectural powder and liquid coatings engineered for harsh environments. Nippon Paint Holdings Co., Ltd., from Osaka, provides industrial polyester coatings and powder systems for metal substrates across Asian and global markets. Allnex Netherlands B.V., in Waalwijk, specializes in polyester resins for powder coatings, including the CRYLCOAT series designed for durable outdoor applications.
Recent Strategic Moves Shaping 2026
Competitive dynamics are not static. Recent corporate actions underscore where incumbents are placing their bets. In May 2025, PPG Industries launched its EnviroLuxe Plus powder coatings range, incorporating post-industrial recycled content to enhance sustainability in polyester-based systems—a move that aligns product differentiation with ESG-driven procurement criteria. In March 2025, BASF SE doubled production capacity for polyester and polyurethane resins at its Caojing plant in Shanghai, directly addressing automotive and industrial coatings demand in a region with accelerating volume growth. In January 2025, Sherwin-Williams completed a Kentucky coil coatings plant expansion, significantly increasing capacity for polyester coil coatings with enhanced automation, reinforcing its position in high-throughput metal finishing markets.
These developments are not isolated; they reflect a broader pattern of capacity realignment, sustainability integration, and regional demand targeting. The report analyzes how such moves reshape competitive benchmarks, alter regional supply-demand balances, and create follow-on opportunities or threats for adjacent participants.
Operational Framework and Decision Utility
A market study is only as valuable as its applicability to real-world decisions. PW Consulting’s Worldwide Polyester Coating Market research is structured to translate macro intelligence into actionable strategy across multiple corporate functions.
What the Report Delivers
- Historical and Forecast Time Series: Detailed revenue tracking from 2020 through 2032, enabling trend analysis, baseline calibration, and scenario planning for budget cycles and capacity investments.
- Segment-Level Analysis: Disaggregated views across applications, product types, and regions that reveal growth concentration, substitution patterns, and demand elasticity without exposing sensitive micro-data.
- Competitive Profiling and Benchmarking: In-depth company profiles, strategic focus areas, recent development tracking, and market share context that support competitive intelligence, partnership evaluation, and positioning strategy.
- Supply Chain and Cost Driver Mapping: Integration of feedstock price trajectories, resin cost structures, and trade-policy impacts to inform procurement timing, hedging strategies, and regional sourcing decisions.
- Regulatory and Sustainability Dynamics: Evaluation of VOC mandates, low-emission product adoption, recycled-content innovation, and regional compliance requirements that shape product roadmap priorities and market access.
- Strategic Scenario Frameworks: Structured analytical pathways that help executives assess best-case, base-case, and stress-case outcomes across demand, cost, and competitive response variables.
Why It Matters for 2026 Decision-Making
As organizations enter 2026, they face a trifecta of pressures: volatile feedstock costs, divergent regional regulatory trajectories, and intensifying competition for high-value applications. In this environment, decisions made without granular market visibility carry elevated risk. A procurement team relying on outdated resin cost assumptions may lock in unfavorable contracts. A product development group may overinvest in a coating format facing regulatory headwinds. A strategic planner may misjudge regional demand strength and misallocate capacity or inventory.
The report mitigates these risks by providing a coherent, data-grounded view of where the market is headed, which segments are structurally advantaged, how competitors are repositioning, and what external shocks—such as PTA price volatility or trade policy changes—could alter the calculus. The deliberate withholding of exact percentage splits and localized dollar figures in this preview is intentional: the full study preserves those analytics as decision-grade intelligence, ensuring that stakeholders who need precision can access it without dilution.
Next Steps for Strategic Teams
The Worldwide Polyester Coating Market will continue to evolve through 2032, shaped by capacity expansion cycles, feedstock market fluctuations, sustainability-driven product substitution, and regional industrial policy. Organizations that integrate this intelligence into their planning processes will be better positioned to optimize sourcing, align R&D with market demand, and anticipate competitive moves before they materialize.
We invite executives, strategy leads, procurement directors, and market intelligence teams to access the complete study for full segmentation detail, competitive benchmarking depth, and scenario-ready data sets. The preview above establishes the strategic frame; the full report delivers the precision required to translate insight into execution.
For detailed analysis of this topic, please visit the official page: Worldwide Polyester Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com