

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Dung Removal Robots Market Hits $273.41M in 2025, Nears $503M by 2032

Strategic Intelligence for the Herd: Navigating the Worldwide Dung Removal Robots Market in 2026
The agricultural machinery sector is undergoing a quiet but decisive transformation. At the intersection of animal welfare, labor economics, and emission compliance, automated dung removal systems have evolved from niche barn conveniences into strategic assets for commercial livestock operations. As enterprises plan capital allocations and technology roadmaps for 2026, understanding the trajectory of this market is no longer optional—it is a prerequisite for competitive positioning. Our latest Worldwide Dung Removal Robots Market research delivers the structural clarity required to make informed decisions in a rapidly consolidating landscape.
The 2026 Decision Context: Why Timing Matters
Livestock operators are confronting a convergence of pressures. Manual cleaning routines remain repetitive and labor-intensive, while tighter welfare standards and emission reduction targets demand more consistent barn hygiene. Simultaneously, advancements in autonomous navigation, durable frame engineering, and floor-specific cleaning mechanisms are expanding the practical envelope of robotic solutions across dairy and swine facilities. In this environment, procurement teams, investors, and strategic planners must evaluate not only unit economics but also ecosystem readiness, technology maturity, and regional deployment patterns. Our analysis frames these variables within a forward-looking timeline that maps historical adoption into the 2026-2032 forecast horizon, giving decision-makers a reliable scaffold for scenario planning.
Market Trajectory and Structural Signals
The market has demonstrated steady expansion over the past half-decade, with revenue climbing from 185.4 million USD in 2020 to 273.41 million USD in 2025. The trajectory reflects a compound annual growth rate of 9.1 percent as the sector moves through the forecast window to 2032, indicating durable demand rather than a short-lived procurement cycle. This growth path signals a market that is past its early-adoption volatility and entering a phase where repeatability, service networks, and segment fit become decisive purchasing criteria.
For corporate strategists, that pattern carries several implications. First, growth at this pace typically attracts incremental capacity, but it also raises the bar for differentiation. Buyers increasingly weigh floor compatibility, bedding handling, noise levels, and emission impacts alongside base cleaning performance. Second, as installations broaden across farm types and geographies, the importance of after-sales support, spare parts logistics, and localized engineering grows in tandem. Third, the market’s momentum suggests that automation is becoming embedded in standard barn design discussions, not merely retrofitted as an aftermarket upgrade. Understanding where these adoption inflection points occur enables enterprises to time product launches, service investments, and partnership initiatives more effectively.
Worldwide Toilet Cleaning Robot Market
Segment Architecture and Decision Levers
The commercial landscape is shaped by three interlocking segmentation dimensions: robot type, end-user application, and geographic deployment. Each dimension influences product requirements, pricing tolerance, and competitive intensity in distinct ways.
Robot Type and Floor Compatibility
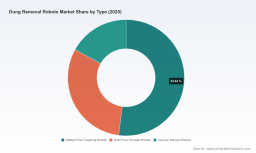
Cleaning technology diverges sharply by barn construction and bedding strategy. Slatted floor cleaning robots remain the dominant solution category, reflecting their broad compatibility with passageways designed for liquid manure drainage. Solid floor scraper robots serve operations that prioritize surface cleaning in denser floor configurations, while vacuum manure robots address specialized removal needs where containment and collection matter more than continuous scraping. For procurement teams, the strategic question is less about which category is largest and more about which architecture aligns with existing infrastructure, bedding regimes, and daily workflow. Our research evaluates how each type performs across cleaning consistency, material handling, and operator oversight requirements, helping buyers translate technical specifications into total cost-of-ownership logic.
End-User Focus and Operational Fit
Application demand is concentrated where herd size, hygiene criticality, and labor constraints intersect. Dairy cattle farms represent the principal demand pool, given the scale of routine cleaning cycles and the direct link between floor hygiene and hoof health, udder health, and overall animal comfort. Swine operations form a substantial secondary application base, where manure management overlaps with ventilation planning, pen design, and biosecurity considerations. Other livestock settings contribute additional niche demand, often shaped by smaller herd structures and differentiated facility layouts. From a strategy perspective, these segments do not simply differ in volume; they differ in purchase drivers, installation complexity, and post-deployment support expectations. Enterprises seeking targeted go-to-market approaches benefit from a segmentation view that connects operational pain points with solution fit.
Regional Deployment Patterns
Geographic distribution illuminates where adoption maturity, local regulation, and farm structure shape demand intensity. Europe currently anchors the largest revenue concentration, reflecting a combination of advanced barn modernization, strong welfare expectations, and established service ecosystems. North America follows with a significant footprint, driven by large-scale dairy and swine operations that weigh labor efficiency against installation economics. Asia Pacific represents a meaningful growth corridor, where changing farm structures and increasing attention to productivity and emissions create room for broader automation uptake. Rest of World markets add incremental but strategically relevant demand, often characterized by varied facility standards and localized procurement dynamics. For global suppliers and investors, regional analysis matters because it reveals where channel development, certification pathways, and service coverage will determine market entry success.
Competitive Landscape and Positioning Logic
The competitive field is moderately concentrated, with a handful of established manufacturers holding meaningful share and multiple specialized players competing on floor-type expertise, barn size adaptability, and emission-conscious design. Our research profiles the leading companies shaping this environment and examines how their product families map to practical barn requirements.
- JOZ b.v. provides manure robots engineered for solid barn floors, with systems designed to handle heavier bedding materials such as straw in dairy environments. This positioning makes the company relevant to operations with traditional bedding practices and solid-surface cleaning needs.
- Lely offers a manure robot series that spans slatted and solid floor applications. Its Discovery scraper targets slatted passageways, while the Discovery collector addresses denser or solid barn floors, with an emphasis on consistent hygiene and cow health outcomes.
- Schauer Agrotronic manufactures manure removal robots for solid surfaces in small to medium dairy barns without straw, emphasizing hygiene and emission reduction. Its approach appeals to operators focused on compact barn layouts and cleaner walking surfaces.
- Peter Prinzing develops an autonomous manure removal robot aimed at reliable cleaning of slatted floors in cattle barns of varying sizes, supporting operations that value repeatable cleaning cycles across different barn scales.
- GEA Group supplies manure scraper robots for slatted passageways, engineered for quiet operation and optimized barn hygiene across different barn sizes. Its profile is relevant where noise, operator comfort, and broad barn applicability matter.
- AGRICOW produces robotic manure scrapers, including a model suited to both slatted and semi-closed floors, offering flexibility for facilities that need a hybrid cleaning approach.
Industry activity remains active around product communication and specification refinement. In September 2025, for example, Schauer Agrotronic released product video content highlighting its ENRO+ manure removal robot for solid walkway cleaning and emission reduction, underscoring how manufacturers continue to sharpen market positioning around hygiene and environmental performance.
Worldwide Dung Removal Robots Market
Competitive Dynamics Beyond the Product Sheet
Several structural forces now influence buying behavior and supplier strategy. Material durability is a recurring theme: dung removal robots commonly utilize carbon steel frames and specialized components to withstand harsh barn environments, and this engineering baseline affects lifecycle cost, maintenance frequency, and overall reliability. At the same time, automation directly addresses repetitive labor in dairy barns, reducing manual cleaning efforts and improving consistency in hygiene, which strengthens the operational case for upfront investment. Regulatory and welfare expectations further reinforce adoption by linking improved barn hygiene to better animal health and broader livestock welfare and emission reduction goals. Taken together, these forces mean that competitive advantage is increasingly defined by more than cleaning performance alone. Service coverage, installation expertise, compatibility with existing barn layouts, and clear communication of welfare and emission benefits all shape purchase decisions.
What the Report Delivers for Strategic Planning
This research is designed for teams that need to convert market signals into actionable plans. It combines top-down market sizing with segment-level interpretation, competitive profiling, and operational context that enterprise buyers can use immediately. Key components include:
- A comprehensive market size and forecast framework that situates historical performance within the 2026-2032 outlook, enabling revenue planning, market entry timing, and investment sequencing.
- Segment-level analysis across robot type, end-user application, and regional deployment, helping readers identify where demand is concentrated and where differentiation opportunities are most viable.
- Competitive profiling of leading manufacturers, with attention to product families, barn compatibility, and positioning themes that matter to procurement and product strategy teams.
- Operational and strategic context drawn from material design practices, labor dynamics, and regulation-linked adoption drivers, so that market figures are interpreted through real-world barn conditions.
- Scenario-ready framing for capital allocation, channel development, and product planning, including considerations for service networks, installation readiness, and segment-specific purchasing drivers.
How to Use This Intelligence in 2026
For equipment manufacturers and technology providers, the report supports product roadmap decisions by clarifying which floor types, farm types, and regions present the strongest alignment between solution capabilities and buyer priorities. For investors and lenders, it offers a structured view of demand durability, competitive concentration, and adoption drivers that can inform diligence and portfolio strategy. For distributors, integrators, and service organizations, it highlights where deployment scale, barn compatibility, and after-sales expectations are likely to shape growth. For large livestock enterprises, it provides a basis for evaluating automation not as a stand-alone purchase but as part of a broader hygiene, labor, and compliance strategy.
Closing the Information Gap
Market-level trends tell only part of the story. To evaluate entry timing, segment fit, competitive exposure, and regional opportunity with precision, decision-makers need the full dataset and interpretive layers behind these headlines. Our Worldwide Dung Removal Robots Market research is built to provide that depth: a complete forecast structure, segment splits, company profiles, and strategic context calibrated for enterprise use. The summary above illustrates the analytical approach and the nature of the decision support available, while the full report contains the detailed figures and breakdowns necessary for quantitative planning. For teams preparing 2026 strategies in agricultural automation, the opportunity is to move from broad market awareness to targeted, evidence-based action. The complete research package is available through our official report page, where the full segmentation views, competitive detail, and regional breakdowns can be reviewed in context.
For detailed analysis of this topic, please visit the official page: Worldwide Dung Removal Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com