

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mica Capacitor Market to Hit $922M by 2032, 4.38% CAGR

Strategic Horizons: Navigating the Worldwide Mica Capacitor for Industrial Market 2026-2032
The industrial electronics sector stands at a critical juncture where component reliability dictates system longevity and operational safety. As we move beyond the baseline year of 2025, understanding the trajectory of passive components becomes essential for stakeholders aiming to secure supply chains and capitalize on emerging opportunities. PW Consulting presents a comprehensive strategic analysis of the Worldwide Mica Capacitor for Industrial Market, offering a data-rich roadmap designed to inform high-level decision-making through 2032.
This research is not merely a collection of statistics but a diagnostic tool for assessing market health. The global mica capacitor revenue is projected to ascend from approximately 683 million USD in 2025 to nearly 922 million USD by 2032. This trajectory reflects a compound annual growth rate of 4.38 percent over the forecast period. Such growth signals a sustained demand for dielectric stability in harsh industrial environments, warranting a deep dive into the underlying drivers, competitive pressures, and raw material dynamics that will define the next decade.
The State of the Industry: A Snapshot of Market Dynamics
The historical context provided by the study establishes a foundation of resilience. Following a period of flux between 2020 and 2024, where revenues fluctuated between 551 million USD and 641 million USD, the market has corrected and stabilized. The recovery observed in 2025 suggests that industrial sectors are recommitting to high-reliability components despite macroeconomic headwinds. This stabilization is crucial for capacity planning and inventory management strategies heading into the forecast period.
Several macro-level dynamics are shaping this landscape. Raw material availability remains a pivotal concern for procurement teams. Natural mica currently holds a dominant position within the broader mica market, securing a substantial share driven by its established status as the preferred material for electronics-grade capacitor production. This reliance on natural sources introduces compliance overhead, as extraction remains geographically concentrated. Stakeholders must remain aware that this concentration exposes supply chains to regulatory oversight and ethical sourcing scrutiny.
Furthermore, geopolitical factors continue to influence pricing structures. Import and export restrictions or tariffs on mica trade from major producers in regions such as China, India, and Africa affect global pricing and supply continuity for capacitor manufacturers. In 2025, the pricing for silvered mica destined for capacitors operated within a wide band, influenced heavily by quality, size, and specific mining sources. Industrial buyers must account for these volatility factors when negotiating long-term contracts.
Segmentation Intelligence: Types and Applications
Diversification in Capacitor Types
The market is segmented by technology type, reflecting varying requirements for performance and cost. Within the scope of this study, silver mica capacitors represent the dominant technology segment, capturing the majority of market revenue. This predominance is attributed to their superior performance characteristics in high-frequency and high-stability applications. However, reconstituted mica capacitors and paper mica capacitors maintain distinct footholds, serving niche requirements where specific thermal or voltage characteristics are prioritized over raw frequency performance.
Understanding the revenue distribution across these types is vital for product portfolio strategy. While silver mica leads in volume, the reconstituted segment offers specific advantages for high-temperature environments. The report details the market share dynamics without exposing specific valuation figures, allowing strategic planners to assess where their proprietary technologies align with market demand curves. This segmentation analysis helps manufacturers decide whether to invest in R&D for enhanced silver mica formulations or optimize reconstituted processes for industrial heating applications.
Application Verticals Driving Demand
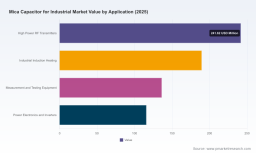
Power electronics and heavy industrial processing are the primary engines of consumption. The study identifies high power RF transmitters as a significant consumption point, leveraging the low loss tangent of mica dielectrics. Industrial induction heating systems follow as a major application vertical, utilizing the thermal stability of mica capacitors to withstand intense operational conditions. Measurement and testing equipment also contribute substantially to demand, requiring precision components for calibration and instrumentation.
Worldwide Mica Trimmer Capacitor Market
Power electronics and inverters represent another critical application area, where efficiency and reliability are non-negotiable. As industrial automation expands, the need for robust power conversion components grows in tandem. The report explores the revenue contribution of each application vertical, highlighting where growth rates are accelerating. By understanding which applications are driving the bulk of the 922 million USD outlook by 2032, companies can tailor their sales channels and technical support resources accordingly. Specific percentage breakdowns for each application are reserved for the full dataset to ensure committed engagement with the primary research.
Competitive Landscape: Key Players and Strategic Moves
The market exhibits a moderate concentration of supply, with the top three companies accounting for nearly half of the total revenue share. The top five players extend this influence to cover approximately 59 percent of the market. This concentration indicates that while there are opportunities for niche players, the bulk of volume flows through established authorities with proven supply chains and certification portfolios.
Several key companies define the competitive boundaries of this industry. Cornell Dubilier Electronics, headquartered in the USA, remains a central figure as a world authorities on mica dielectric capacitors. Their ongoing availability of RF high Q models for industrial use reinforces their position as a benchmark for quality. Exxelia, based in Paris, France, continues to strengthen its position through high-reliability silvered mica capacitors. Notably, in December 2024, Exxelia obtained QPL qualification for their HT 97PS high-temperature series, making them suitable for oil and gas and industrial exploration equipment. This qualification represents a strategic expansion into demanding environments.
Pacific Capacitor Co., also based in the USA, maintains active AS9100 Rev. D and ISO 9001:2015 certifications as of March 2026. These certifications support their production of high voltage mica capacitors for industrial applications, signaling adherence to rigorous quality management standards. Custom Electronics, Inc. has been manufacturing high-voltage reconstituted mica paper capacitors since 1964, serving radar, missile, and industrial high-reliability systems. Their longevity suggests a deep understanding of legacy support and component substitution.
Richard Jahre in Germany focuses on industrial and high-stability applications, while Teledyne Advanced Electronic Solutions provides mica capacitors for advanced electronic solutions in industrial and defense-related applications. Vishay Intertechnology offers silver mica dipped capacitors suitable for precision industrial uses. On the global supply side, Simic Electronics Pvt Ltd in India and Suntan in Hong Kong serve industrial clients across USA, Europe, and Asia, complying with ISO 9001:2015 standards. Additionally, Commercial Radio Company, Inc. acts as a major stocking distributor for CDM mica capacitors, supporting high-voltage industrial and RF applications. The full report provides a detailed comparison of these entities, analyzing their strengths and weaknesses without disclosing specific market share figures publicly.
Regional Dynamics and Supply Chain Considerations
Geographically, the market is distributed across five key regions. Asia Pacific generates the largest revenue volume, reflecting its role as a manufacturing hub and a center for industrial consumption. North America follows as a significant market, driven by high-tech industrial applications and defense-related demand. Europe represents a mature market with strict regulatory standards influencing component selection. Latin America and the Middle East and Africa constitute smaller but growing segments, often tied to resource extraction and infrastructure development projects.
For strategic planners, understanding regional revenue distributions is key to logistics and localization strategies. The report delineates the revenue generated in each region, providing a clear map of where value is captured. This information assists in determining where to establish distribution centers or where to prioritize sales engineering efforts. Specific regional monetary values are detailed in the proprietary sections of the study to maintain the integrity of the forecasting model.
Worldwide Mica Capacitor for Industrial Market
Strategic Implications for 2026 Decision Makers
The insights contained in this study are designed to trigger actionable intelligence for executives operating in 2026. First, the data supports supply chain risk mitigation. By understanding the reliance on natural mica and the geographic concentration of extraction, companies can develop dual-sourcing strategies or invest in material verification processes. The volatility in raw material pricing necessitates flexible procurement frameworks that can absorb cost fluctuations without eroding margins.
Second, the competitive analysis aids in positioning. Knowing that the top players hold significant sway allows mid-sized manufacturers to identify gaps in the market. For instance, while major players dominate standard industrial applications, opportunities may exist in specialized high-voltage or high-temperature niches where certification barriers are high. The recent developments by companies like Exxelia obtaining specific qualifications highlight the value of certification as a competitive moat.
Third, the application shift data informs R&D budgets. As industrial induction heating and power electronics continue to demand stable dielectric performance, investing in capacitor technologies that align with these verticals ensures relevance. The growth from 2026 to 2032 suggests that early movers in capacity expansion or technology refinement will capture disproportionate value. The report provides the granular visibility needed to justify these capital expenditures to stakeholders.
Conclusion: Accessing the Full Intelligence
The Worldwide Mica Capacitor for Industrial Market research by PW Consulting offers a definitive view of the industry trajectory. From the macro growth rates to the micro dynamics of raw material sourcing, every aspect is scrutinized to provide a clear picture of the future. The market is poised to reach 922 million USD by 2032, driven by enduring industrial needs and technological stability. However, navigating this growth requires more than surface-level data.
To fully leverage these findings for your organization, detailed segmentation splits, precise regional valuations, and comprehensive competitor benchmarking are available within the complete report. The summary provided here outlines the strategic landscape but withholds the specific percentages and monetary breakdowns necessary for precise forecasting and budgeting. Acquiring the full publication ensures your team has the exact figures required to model scenarios and validate investment theses. In a market defined by concentration and regulatory complexity, precision is the ultimate competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Mica Capacitor for Industrial Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com