

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PET and SPECT Scanners Market Hits $5.85 Billion in 2025, On Track for 6.5% CAGR to $9.09 Billion by 2032

Strategic Intelligence for the Molecular Imaging Era: Unlocking Value in the PET and SPECT Scanners Market
The landscape of molecular imaging is undergoing a structural transformation, driven by the convergence of digital detector technology, artificial intelligence integration, and evolving reimbursement frameworks. For healthcare providers, investors, and medical device strategists, navigating this shift requires more than surface-level market data. It demands a granular understanding of how capital expenditure trends, regulatory clearances, and clinical adoption patterns intersect to shape profitability and market share.
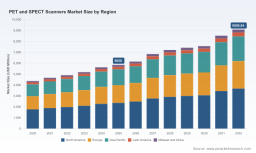
Our latest market research report on the PET and SPECT Scanners Market delivers precisely that intelligence. Designed for executive decision-making in 2026 and beyond, this study maps the trajectory of a sector that has demonstrated consistent growth, with the overall market valuation expanding from approximately 4.37 billion USD in 2020 to an estimated 5.85 billion USD by 2025. The forecast period through 2032 projects a compound annual growth rate of 6.5 percent, signaling sustained demand for advanced hybrid imaging systems across oncology, cardiology, and neurology.
This article serves as a strategic preview of the full report, outlining why this research is essential for 2026 corporate planning, what operational and competitive dimensions it covers, and how the latest industry dynamics are redefining the rules of engagement for market participants.
The Strategic Imperative for 2026 Decision-Making
Annual strategic planning cycles in the medical imaging sector are no longer sufficient. The pace of technological iteration, regulatory evolution, and reimbursement adjustment requires forward-looking intelligence that bridges historical performance with multi-year forecasts. Hospitals and imaging centers are making procurement decisions with longer asset lifecycles and higher capital thresholds. Meanwhile, OEMs and component suppliers must anticipate shifts in geographic demand, application-specific volume growth, and the competitive positioning of digital versus analog detector platforms.
The data foundation of this report captures a clear growth arc: market revenue climbed from 4.66 billion USD in 2021 to 5.19 billion USD in 2023, reached 5.62 billion USD in 2024, and is projected to cross the 6.15 billion USD threshold in 2026. By the end of the forecast horizon in 2032, the market is expected to approach 9.09 billion USD. These figures are not merely background statistics; they establish the scale of opportunity and the urgency of positioning. A 6.5 percent CAGR across an eight-year forecast window indicates that early movers in digital PET/CT and advanced SPECT/CT deployment will capture disproportionate share of high-margin clinical workflows, particularly in theranostics, total-body imaging, and AI-enhanced diagnostic pathways.
Equally critical is the concentration profile of the market. The top three competitors command an estimated 68.5 percent of industry revenue, while the top five hold approximately 82.3 percent. This level of consolidation shapes pricing power, service contract leverage, and the ability to invest in next-generation R&D. For new entrants, distributors, and regional service providers, understanding where the concentration lies and where whitespace remains is a prerequisite for viable market entry or partnership strategy.
The full report translates these macro signals into actionable frameworks for 2026. It aligns capital budgeting assumptions with procurement cycles, evaluates the impact of reimbursement changes on scan volume and equipment utilization, and maps regional and application-level demand drivers without relying on surface-level generalizations. The objective is to equip leadership teams with a decision-grade view of where to allocate resources, which product configurations are gaining clinical traction, and how competitive pressure is likely to evolve as total-body and AI-noise-reduction technologies mature.
Beyond Headlines: What the Report Delivers in Operational Depth
Market summaries often stop at vendor share rankings and high-level growth percentages. This research is structured to go further, providing the operational and commercial detail that procurement committees, business development teams, and investment analysts require. The report is organized around dimensions that directly influence go-to-market execution, capacity planning, and competitive positioning.
Comprehensive Segmentation and Demand Architecture
The analysis disaggregates market value across scanner type, clinical application, and geographic region, enabling readers to isolate the segments that align with their strategic focus. The segmentation framework examines the relative scale of PET versus SPECT systems, the dominance of oncology and cardiology workflows, and the emerging contribution of neurology and specialty applications. Regional breakdowns reveal where installed-base replacement cycles, new sitebuild activity, and public-sector procurement are concentrated, allowing stakeholders to calibrate distribution partnerships, service network expansion, and localized marketing investments.
Rather than presenting static share tables, the report contextualizes each segment with demand drivers, adoption barriers, and procurement behavior. This includes an assessment of digital detector penetration, preferences for hybrid modalities, and the operational impact of scan-time reduction technologies. For organizations evaluating product portfolio alignment or regional entry, these insights clarify which configurations are gaining clinical preference and where reimbursement or infrastructure constraints may temper adoption.
Competitive Benchmarking and Product Strategy Mapping
The competitive landscape section goes beyond corporate profiles to evaluate how leading manufacturers are differentiating their offerings and responding to market pressure. The report profiles major players including Siemens Healthineers, GE HealthCare, Koninklijke Philips N.V., Canon Medical Systems, United Imaging Healthcare, Positron Corporation, Mediso Ltd., Neusoft Medical Systems, Spectrum Dynamics Medical, and Shimadzu Corporation. Each profile is anchored in product architecture, clinical focus, and strategic posture, providing a basis for comparative assessment of detector technology, workflow integration, and application-specific strengths.
Siemens Healthineers continues to expand its Biograph and Symbia families, with recent regulatory milestones underscoring its push into hybrid PET/MR and AI-enabled noise reduction. GE HealthCare is advancing high-sensitivity total-body PET/CT platforms and has reinforced its cardiovascular imaging capabilities through both product approvals and academic collaborations. Philips emphasizes digital PET/CT with Time-of-Flight performance for diagnostic accuracy. Canon Medical and United Imaging contribute hybrid molecular imaging platforms with strong sensitivity characteristics, while Positron Corporation and Neusoft focus on specialized cardiac and distribution-aligned strategies in North America. Mediso, Spectrum Dynamics, and Shimadzu round out the field with multimodal preclinical and clinical systems, digital SPECT/CT solutions, and dedicated applications for specific anatomical targets.
The report synthesizes these positions into a competitive map that highlights where incumbents are reinforcing share, where new entrants are building credible alternatives, and how product launches and partnerships are reshaping procurement considerations. This is particularly valuable for organizations assessing partnership opportunities, evaluating competitive threats, or planning product roadmaps that must align with the technology priorities of leading sites.
Market Drivers, Restraints, and Reimbursement Dynamics
Growth in the PET and SPECT sector is not uniform; it is mediated by reimbursement policy, capital availability, radiopharmaceutical supply, and clinical evidence adoption. The report integrates these forces into a coherent demand model, helping stakeholders differentiate between structural growth and cyclical or policy-driven fluctuations.
Recent reimbursement developments are already influencing outpatient volume and equipment utilization. Proposed payment adjustments for diagnostic radiopharmaceuticals exceeding certain daily thresholds, along with add-on incentives for domestically produced isotopes, are reshaping cost structures and encouraging procurement planning around supply security. At the same time, expanded outpatient reimbursement in specialist care programs and growing theranostic applications are contributing to volume upside in specific markets. These dynamics are analyzed in the context of their impact on scanner utilization rates, service contract value, and the financial case for digital detector upgrades.
Regulatory activity is equally consequential. Clearances for next-generation PET/MR systems, total-body PET/CT platforms, AI noise-reduction software, and dedicated neurological PET devices are expanding the clinical envelope of molecular imaging. Each clearance alters the value proposition for specific applications and can accelerate replacement cycles in targeted segments. The report tracks these regulatory milestones and connects them to likely adoption pathways, enabling readers to anticipate where demand will intensify and which configurations will become reference standards in high-volume centers.
Competitive Landscape and Recent Moves Redefining the Field
The PET and SPECT scanners market is characterized by intense rivalry among well-capitalized OEMs and specialized players targeting high-value clinical niches. Competitive advantage is increasingly defined by detector performance, workflow integration, AI-enabled image reconstruction, and the ability to support total-body or application-specific imaging with reduced scan times and improved diagnostic confidence. Recent corporate activity illustrates how rapidly the field is evolving and why up-to-date competitive intelligence is essential for 2026 planning.
Siemens Healthineers received FDA clearance for its second-generation Biograph One PET/MR scanner, reinforcing its hybrid imaging portfolio and extending its reach into applications that demand simultaneous molecular and anatomical data. This clearance signals continued investment in premium hybrid platforms and highlights the competitive importance of PET/MR in centers pursuing advanced oncology and neurological workflows.
PET and SPECT Scanners Market
Positron Emission Tomography (PET) Scanners Market
GE HealthCare secured CE approval for its Omni 128cm total-body PET/CT system and has deepened its clinical validation efforts through collaboration with Erasmus MC University Medical Center to evaluate next-generation total-body technology. Total-body imaging is a strategic frontier because it promises higher sensitivity, lower dose requirements, and faster acquisition, all of which can improve throughput and expand clinical use cases. GE's parallel focus on high-sensitivity cardiac and digital detector platforms further broadens its competitive footprint across high-volume applications.
In a commercially Significant move, Positron Corporation announced multiple PET-CT 64-slice scanner orders with long-term service agreements from leading nuclear cardiology practices. This transaction underscores the enduring importance of cardiac PET in North America and demonstrates how specialized vendors can secure durable revenue streams by aligning product capabilities with the procedural priorities of high-volume cardiology centers.
Regulatory and technology developments at other players are also reshaping the competitive baseline. Spectrum Dynamics Medical has advanced AI noise-reduction capabilities for its VERITON-CT digital SPECT/CT platform, with reported potential to reduce scan times by up to half. Shorter scan times directly influence throughput, patient comfort, and site economics, making such software-enabled improvements strategically important even in mature modalities. Meanwhile, dedicated brain PET systems have received FDA clearance for neurological applications including epilepsy and Alzheimer's monitoring, opening specialized pathways for focused imaging in neurology workflows.
The report situates these developments within a broader competitive analysis that evaluates how each company's product strategy, geographic reach, and partnership activity positions it for the forecast period. By connecting recent clearances, commercial wins, and collaboration announcements to underlying demand drivers, the research provides a dynamic view of competitive momentum rather than a static snapshot.
Why This Research Is Essential for 2026 Planning
Executive teams entering 2026 must make decisions in an environment where technology, policy, and clinical practice are moving in tandem. Procurement cycles are extending, reimbursement frameworks are adjusting, and digital detector adoption is becoming a baseline expectation in high-value imaging sites. In this context, a market research asset that links historical performance, forward forecasts, and current industry dynamics becomes a strategic instrument rather than a reference document.
This PET and SPECT Scanners Market report is built for that purpose. It provides the segmentation detail needed to prioritize segments, the competitive analysis required to assess positioning, and the regulatory and reimbursement context necessary to validate commercial assumptions. It also addresses capital expenditure trends, including evidence that a meaningful share of PET imaging sites in the United States have allocated budgets for equipment with a strong preference for digital detector systems. Such indicators help organizations align product offerings, service capacity, and pricing strategies with the realities of buyer behavior.
Importantly, the report preserves analytical discipline by focusing on decision-relevant insights without oversimplifying the market into broad aggregates. Readers will gain a structured understanding of where growth is concentrated, which technologies are gaining preference, how leading competitors are positioning themselves, and what policy developments are likely to influence volume and margins. This is the kind of intelligence that supports disciplined capital allocation, targeted market entry, and proactive competitive response.
To access the complete segmentation data, detailed competitive profiles, regional and application-level analysis, and the full set of forecast tables and strategic recommendations, we invite you to explore the full report on our website. The complete intelligence package is designed to be integrated directly into executive briefings, investment committees, and strategic planning workflows for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: PET and SPECT Scanners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com