

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Optical Cryostat Market to Hit $386.83M by 2032 with 10.82% CAGR

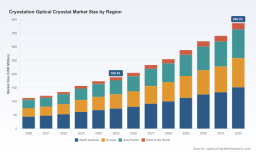
Strategic Intelligence for a Critical Inflection Point: Introducing the Worldwide Cryostation Optical Cryostat Market Research
The precision cooling systems that enable next-generation optical measurements are experiencing a structural shift. As the worldwide Cryostation Optical Cryostat market crosses the $188 million threshold in 2025 and projects a 10.82% compound annual growth rate through 2032, enterprises operating across advanced research, quantum infrastructure, and specialized instrumentation face a rapidly reconfiguring competitive landscape. For executives, procurement leaders, and technology strategists, the window to align capacity planning, R&D investment, and partnership strategy is narrowing. This article outlines why our newly released market research delivers the actionable intelligence required to navigate 2026 and beyond.
The industry is no longer defined by incremental laboratory upgrades. It is being reshaped by converging demand drivers: the expansion of quantum materials research, the maturation of cryogenic measurement ecosystems, and a decisive pivot toward cryogen-free closed-cycle architectures. Understanding how these forces interact—and where capital, talent, and engineering resources should be deployed—requires more than headline growth figures. It demands a granular, scenario-aware view of segmentation dynamics, regional supply chain realities, and the strategic positioning of the firms that dominate this niche but high-value space.
Why 2026 Demands a Forward-Looking Market View
The forecast horizon from 2026 through 2032 reveals a market trajectory that outpaces many adjacent laboratory instrumentation categories. After reaching $188.45 million in 2025, the worldwide revenue base is projected to expand to $204.67 million in 2026, then accelerate toward $254.69 million by 2028 and $386.83 million by 2032. This growth pattern is not uniform across the ecosystem. Instead, it reflects concentrated investment in specific technical configurations, application verticals, and geographic ecosystems that reward organizations with foresight in product roadmapping, vendor partnerships, and specialized service infrastructure.
For corporate strategists, the 2026 outlook carries several implications. First, the shift toward pulse tube and GM cryocooler-based platforms is reducing dependency on consumable cryogens, but it also raises the engineering bar for vibration control, thermal stability, and optical access at sub-4 Kelvin temperatures. Second, the demand for integrated magnetic field capabilities—reaching up to 7T in select platforms—means that optical cryostat procurement is increasingly bundled with magneto-optical experimentation requirements. Third, procurement signals from academic and national research institutions are becoming more customized, with recent sole-source engagements reflecting specifications that include high-frequency coaxial integration, specialized fiber routing, and large sample spaces engineered for high-numerical-aperture optical paths.
Organizations that wait until procurement cycles open will find themselves competing in a constrained supply environment. Those that map the demand trajectory now will be positioned to negotiate long-term supply agreements, align internal R&D with emerging customer specifications, and anticipate where regional demand will concentrate over the next seven years.
Market Structure, Growth Trajectory, and Strategic Implications
The worldwide market for Cryostation optical cryostats has evolved from a fragmented laboratory supply category into a concentrated, technology-intensive segment. Historical revenue progression from 2020 through 2025 demonstrates sustained expansion, but the forecast period reflects a step-change in velocity. This acceleration is underpinned by several structural dynamics that our research unpacks in detail.
One of the defining characteristics of the market is the dominance of closed-cycle architectures. Cryogen-free configurations are increasingly preferred for their operational continuity, reduced consumable costs, and compatibility with automated measurement environments. These systems are designed to eliminate liquid cryogen use while maintaining sample spaces that support complex optical setups and vibration profiles compatible with high-NA optical access down to temperatures below 3.6K. As research teams demand repeatable, low-drift environments for quantum optics and magneto-optical experiments, the engineering requirements for closed-cycle platforms continue to tighten, favoring manufacturers with mature cryocooler integration capabilities and robust mechanical design.
Application demand is equally multifaceted. Quantum computing and information research drives a significant share of procurement, reflecting the need for ultra-low vibration environments and precise temperature control across ranges that span from approximately 1.7K to 350K. Optical spectroscopy, microscopy and imaging, and materials science research each bring distinct technical requirements, from UV to IR window configurations for Raman, FTIR, and NMR-compatible systems, to customized probe stations with integrated optical access. Our research examines how these application segments interact with product architecture choices and how procurement patterns diverge across research-intensive institutions versus commercial R&D environments.
Geographically, the market reflects uneven demand intensity and distinct supplier ecosystems. Regional demand patterns are shaped by the concentration of advanced research institutions, national quantum initiatives, and localized service and support networks. Understanding where demand is emerging, which customs and procurement frameworks dominate, and how logistics and technical support influence total cost of ownership is essential for anyone evaluating market entry, distribution partnerships, or manufacturing footprint decisions.
Competitive Landscape: Who Is Shaping the Next Generation of Optical Cryostats
The competitive field is defined by a small group of highly specialized manufacturers whose product roadmaps, demonstration activity, and technical differentiation directly influence procurement decisions. Our research profiles the firms that are actively setting performance benchmarks, expanding application coverage, and signaling where the market is heading.
Montana Instruments has reinforced its position through a focus on cryogen-free closed-cycle optical cryostats designed for low-vibration optical and electrical measurements. Its flagship Cryostation s200 platform, with a 200mm sample space and temperature range from 3.6K to 350K, exemplifies the performance envelope that quantum materials research teams increasingly expect. The company's continued presence at major industry gatherings—including World of Quantum 2025 in Munich, MRS Fall 2025 in Boston, and the APS Global Physics Summit in Denver—signals sustained engagement with the research community and a deliberate strategy to align product visibility with high-impact application domains. The introduction of the Cryostation 200 PT further underscores an emphasis on stability, automation, and specialized measurement workflows.
Quantum Design has pushed the integration boundary with the OptiCool platform, a cryogen-free magneto-optical cryostat spanning 1.7K to 350K with high optical access and a 7T split-coil magnet. The recent announcement of the OptiCool Vector, featuring a 4-1-1 vector magnet configuration for advanced magneto-optical experiments, illustrates how manufacturers are responding to demand for multi-axis field control in optical measurement environments. These product moves matter because they reshape the specification conversation: procurement teams are no longer comparing standalone cooling performance alone, but evaluating integrated magnetic and optical capabilities as a bundled research-enabling solution.
attocube systems GmbH continues to differentiate through compact closed-cycle platforms such as the attoDRY series, which emphasizes large sample spaces, low vibrations, and unobstructed optical access for magneto- and quantum optical applications. The introduction of the attoCMC line for rack-compatible sub-4K mobile cryogenics reflects a broader industry trend toward flexible, space-efficient configurations that fit within demanding laboratory layouts while preserving experimental performance.
Lake Shore Cryotronics, Advanced Research Systems, and Oxford Instruments (Andor) each bring distinct value propositions. Lake Shore's window sets for UV to IR access and its support for Raman, NMR, and FTIR spectroscopy applications address a broad optical measurement footprint. Advanced Research Systems contributes ultra-low vibration models such as microDrift for quantum optics, alongside custom flow cryostats and probe stations with optical access. Oxford Instruments' Cryofree OptistatDry series, with top- or bottom-loading options, reinforces the market's demand for temperature-controlled optical measurement platforms that integrate cleanly into spectroscopy and microscopy workflows.
Importantly, the market is not a free-for-all. Consolidated concentration metrics indicate that a limited number of firms account for a substantial share of revenue, which means competitive dynamics are shaped as much by ecosystem lock-in, service reliability, and specification familiarity as by price. Our research examines how these firms position themselves across type, application, and regional demand, and where white space or over-served segments may create opportunities for differentiated offerings.
What the Report Delivers: Actionable Intelligence for Decision-Makers
This study is built for executives who need more than directional commentary. It provides a structured, decision-oriented view of the worldwide Cryostation Optical Cryostat market, with explicit attention to the operational questions that determine procurement success, product strategy, and investment timing.
The report covers the historical period from 2020 to 2025 and extends forecast analysis through 2032, allowing readers to connect past demand behavior with forward-looking scenarios. It evaluates the market across three analytical dimensions: type, application, and region. By disaggregating demand in this way, the study helps readers understand which product architectures are gaining traction, which application verticals are expanding procurement intensity, and where regional demand is likely to concentrate.
Key components of the report include:
- Detailed segmentation analysis that clarifies how closed-cycle and open-cycle configurations divide the market and how each type aligns with distinct user requirements, vibration tolerances, and optical access needs.
- Application-level insight that differentiates demand drivers across quantum computing and information, optical spectroscopy, microscopy and imaging, and materials science research, with attention to the technical thresholds that shape purchasing decisions.
- Regional demand and supply context that helps organizations assess where procurement activity is intensifying, how local service infrastructure affects adoption, and what logistical or customization considerations influence total cost of ownership.
- Competitive profiling of leading manufacturers, including product positioning, recent launches, demonstration activity, and procurement signals that reveal how the market is evolving in near-real time.
- Strategic scenario framing that supports capacity planning, partnership evaluation, and product roadmap decisions by connecting technical trends to commercial outcomes.
- Practical guidance on regulatory and classification considerations, including the fact that research-grade optical cryostats for laboratory applications are generally treated as general laboratory equipment rather than medical devices, which has implications for compliance workflows, procurement categorization, and cross-border trade planning.
Our objective is to give decision-makers a clear line of sight from market structure to action. Whether you are evaluating vendor selection, planning a specialized manufacturing or distribution entry, or aligning internal R&D with emerging demand, the study is designed to reduce ambiguity and support defensible strategy choices.
Market Dynamics Shaping 2026 and Beyond
Several interlocking dynamics will determine how the market unfolds over the forecast period. First, the demand for low-vibration, cryogen-free environments is no longer a niche preference; it is becoming a baseline requirement for research programs that depend on reproducible optical and electrical measurements. This creates a performance ceiling that rewards manufacturers with mature cryocooler integration and penalizes those that cannot consistently deliver thermal stability, low drift, and unobstructed optical paths.
Second, the convergence of optical access with magnetic field capability is redefining specification packages. As research increasingly requires magneto-optical experiments across a wide temperature envelope, buyers are evaluating platforms that combine cooling performance, magnet integration, and optical geometry in a single, coherent system. This bundling effect favors vendors that can offer integrated solutions and also creates opportunities for organizations that can provide specialized accessories, calibration services, or application-specific customization.
Third, procurement behavior is becoming more project-specific and specification-intensive. Recent procurement activity from research institutions demonstrates a move toward customized high-capacity closed-cycle systems with specialized coaxial and fiber integration. These engagements signal that end users are no longer treating optical cryostats as interchangeable catalog items; they are engineering them into broader experimental architectures. For suppliers and channel partners, this means that flexibility, lead-time management, and application engineering support are becoming as important as core product performance.
Fourth, the operational advantages of cryogen-free systems are reshaping total cost of ownership discussions. Eliminating recurring liquid cryogen dependence improves workflow continuity and reduces logistical complexity, but it also shifts value toward initial capital expenditure, service contracts, and long-term reliability. Organizations evaluating procurement strategies should weigh not only sticker price, but also downtime risk, service availability, and the compatibility of a platform with planned future experiments.
Worldwide Optical Cryostat for Microscopy Market
Finally, the market's classification as general laboratory equipment—rather than a regulated medical device category—streamlines certain compliance considerations, but it does not eliminate the need for rigorous vendor evaluation. Research users continue to require systems designed exclusively for laboratory and research applications, with performance claims grounded in measurable vibration, temperature stability, and optical access characteristics. This reinforces the importance of manufacturer documentation, application-specific validation, and transparent specification language when comparing alternatives.
Why This Research Matters for Your 2026 Strategy
The worldwide Cryostation Optical Cryostat market is entering a phase in which strategic advantage will belong to organizations that understand not just that demand is growing, but where that growth is concentrated, why it is emerging, and how it will reshape procurement, product design, and competitive positioning. Our study is engineered to provide that understanding without overwhelming readers with disconnected statistics. Instead, it connects market size, growth trajectory, segmentation behavior, competitive activity, and application-specific dynamics into a coherent decision framework.
Worldwide Cryostation Optical Cryostat Market
For companies evaluating market entry, the research clarifies where demand intensity is highest and what technical and service capabilities are required to compete credibly. For existing manufacturers and distributors, it identifies where specification expectations are rising, which application verticals are expanding fastest, and how recent product launches and demonstration activity are reshaping buyer expectations. For procurement teams and research administrators, it provides the context needed to assess vendor claims, anticipate customization requirements, and evaluate total cost of ownership across different architectural choices.
Most importantly, the study is designed to support timely action. The forecast period through 2032 is long enough to warrant durable investment decisions, yet near-term dynamics in 2026 will set the tone for supply availability, competitive intensity, and specification standards. Organizations that gain clarity now will be better positioned to structure partnerships, allocate engineering resources, and respond to procurement opportunities with confidence rather than reaction.
To access the full segmentation breakdown, regional demand analysis, application-level projections, and detailed competitive profiling, we invite you to explore the complete Worldwide Cryostation Optical Cryostat Market research. The published report provides the depth required to convert market intelligence into concrete strategic moves in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Cryostation Optical Cryostat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com