

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Silicon Etching Market to Reach $7.6B by 2032, 9.15% CAGR | Asia Pacific Leads

Beyond Countrols: Strategic Intelligence for the Worldwide Silicon Parts for Etching Market (2026–2032)
In the high-stakes arena of semiconductor fabrication, the performance of plasma etching equipment is often defined by the consumables it employs. Silicon parts for etching—including focus rings, electrodes, and wafer edge rings—are not merely accessories; they are critical determinants of etch uniformity, process stability, and yield. As the global semiconductor industry accelerates toward advanced logic nodes and high-density memory devices, the demand for high-purity silicon components is experiencing a structural shift. PW Consulting's latest research, Worldwide Silicon Parts for Etching Market, offers a comprehensive strategic lens into this evolving landscape, providing the intelligence necessary for stakeholders to navigate the forecast period of 2026 to 2032.
This report is not simply a collection of figures; it is a decision-support tool designed for executives, investors, and supply chain strategists. By analyzing historical trajectories from 2020 through 2025 and projecting forward, we uncover the underlying drivers shaping the market's expansion. The base year analysis for 2025 establishes a robust foundation, with the market having grown significantly over the past half-decade. This momentum is expected to continue, driven by the relentless scaling of semiconductor manufacturing and the increasing complexity of etching processes required for next-generation devices.
Market Trajectory and Growth Dynamics
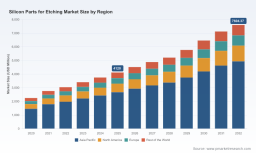
The macroeconomic indicators within this research highlight a compelling growth story. The total revenue for silicon parts used in etching processes has demonstrated consistent upward movement, reflecting the broader expansion of the semiconductor equipment market. Starting from a base of approximately 2.25 billion USD in 2020, the market has climbed steadily, reaching an estimated 4.12 billion USD by 2025. This historical performance underscores the critical role these components play in the fabrication ecosystem.
Looking ahead, the forecast period reveals sustained expansion. Projections indicate that the market will surpass the 4.5 billion USD mark in 2026, continuing its ascent toward higher valuations by the end of the decade. The Compound Annual Growth Rate (CAGR) during the forecast period is estimated at 9.15 percent, signaling a healthy, above-average growth trajectory compared to many mature industrial sectors. This growth is not linear; it is punctuated by technology nodes transitions, capacity expansions in key fabrication hubs, and the increasing replacement frequency of consumables in high-throughput plasma etching environments.
It is important to note that growth rates vary across different dimensions of the market. While the overall trend is positive, specific segments exhibit distinct behaviors based on technological adoption rates and regional manufacturing intensities. Our analysis delves into these variations without exposing sensitive granular data, allowing clients to understand the velocity of growth in their specific areas of interest while maintaining the integrity of proprietary forecasts.
Structural Composition: Types and Applications
The market for silicon etching parts is structurally divided by type and application, each presenting unique value propositions and challenges. By type, the market encompasses silicon rings, silicon electrodes, and other silicon parts. Silicon rings, which include focus rings and edge rings, constitute a significant portion of the demand, as they are essential for maintaining plasma distribution and wafer edge protection during etching. Silicon electrodes, serving as the upper or lower electrodes in etch chambers, are equally critical for process uniformity and are subject to stringent quality requirements due to their direct exposure to plasma environments. Other silicon parts, such as shielding rings and adapters, complete the ecosystem, addressing specific equipment configurations and process needs.
In terms of application, the demand is primarily driven by logic and foundry operations as well as memory device manufacturing. Logic and foundry applications require high-precision etching for complex transistor structures, driving the need for components that can withstand aggressive chemistries and high temperatures. Memory devices, including DRAM and NAND flash, also impose heavy demands on silicon parts due to the high aspect ratios and multi-layer stacking processes involved. The interplay between these application segments and the type of components required creates a complex demand matrix that our report unpacks in detail.
A key operational insight highlighted in the research is the consumable nature of these parts. Silicon components used in plasma etching are typically replaced after a defined number of wafer processes to ensure process integrity. This replacement cycle creates a recurring revenue stream for suppliers but also imposes strict requirements on cost-efficiency and supply reliability for manufacturers. Understanding the lifecycle and replacement frequency is vital for forecasting demand accurately, and our report provides the operational context needed to model these consumption patterns.
Regional Landscape and Supply Chain Concentration
Geographically, the market exhibits a pronounced concentration in specific regions, reflecting the global distribution of semiconductor manufacturing capacity. Asia Pacific stands out as a dominant region, hosting major production and consumption clusters for silicon etching parts. This dominance is largely attributable to the concentrated semiconductor manufacturing investments in countries such as South Korea and China. These nations host a significant number of logic, foundry, and memory fabrication facilities, creating a localized demand surge for high-quality silicon components.
North America and Europe also represent substantial markets, driven by their respective equipment manufacturing sectors and specialized fabrication activities. The rest of the world contributes to the overall market size, though at a smaller scale relative to the primary hubs. Our regional analysis explores the nuances of supply and demand within these areas, examining how local manufacturing capabilities, import dependencies, and regional policies influence market dynamics.
Worldwide Silicon Parts for Etching Market
The market structure is characterized by a moderate level of concentration among key players. The competitive landscape is shaped by a mix of established global suppliers and specialized regional manufacturers. Our report assesses the competitive intensity, market share distribution, and strategic positioning of leading firms. This analysis helps stakeholders identify potential partnership opportunities, assess competitive threats, and understand the barriers to entry in this high-purity materials segment.
Competitive Landscape and Key Players
The industry is served by a diverse array of companies, each bringing distinct capabilities to the table. PW Consulting's research profiles several key enterprises that define the competitive arena, analyzing their operational strengths, product portfolios, and strategic orientations.
Silfex Inc., based in Eaton, Ohio, USA, is recognized for providing high-purity custom silicon components for semiconductor etch applications. Their offerings include critical gas distribution parts and wafer edge rings supplied to major semiconductor processing equipment companies. Silfex's focus on customization and high-purity standards positions them as a reliable partner for equipment OEMs and fabs requiring tailored solutions.
Hana Materials Inc., headquartered in Cheonan-si, South Korea, produces silicon electrodes, silicon rings, and related parts for dry etching processes. Their integrated production capabilities, spanning from ingots to finished parts, allow for greater control over quality and supply continuity. Serving global equipment makers, Hana Materials leverages its South Korean base to align closely with regional demand clusters.
Mitsubishi Materials Corporation, based in Japan, supplies high-quality silicon parts for etching applications in semiconductor equipment. Their longstanding materials expertise and global reach contribute to their presence in the market, particularly in applications demanding exceptional reliability and consistency.
CoorsTek, operating from the USA, offers semiconductor-grade silicon components, including focus and edge rings designed for plasma etch chambers. Their products are engineered to improve uniformity and withstand harsh environments, addressing the core performance requirements of advanced etching processes.
In the Asian supply chain, Ningxia Dunyuanjuxin Semiconductor Technology Corporation (DSTC), located in Yinchuan, Ningxia, China, manufactures a range of silicon components for etching, including focus rings, showerheads (upper electrodes), outer rings, exhaust rings, and shielding rings. Their focus on optimizing plasma uniformity and etching precision reflects the increasing technical sophistication of Chinese manufacturers.
Sicreat, also based in China, develops and produces monocrystalline silicon components for integrated circuit plasma etching. Their product line includes focus rings, silicon electrodes, trays, and plates, characterized by low impurity content and large diameters up to 485mm. The emphasis on monocrystalline quality and large-diameter capabilities highlights the industry's push toward higher performance and yield.
Other notable participants include Semicorex, which supplies silicon parts including etching carriers for semiconductor processes, and Worldex Industry & Trading Co., Ltd. in South Korea, which provides silicon parts for etching in the semiconductor industry. Thinkon Semiconductor (Fujian Dynafine) in China manufactures silicon parts for etching applications, while Techno Quartz Inc. and RS Technologies Co., Ltd. in Japan supply silicon components used in semiconductor etching. KC Parts Tech., Ltd. in South Korea also contributes to the production of silicon parts for etching in semiconductor manufacturing.
These companies collectively shape the market through competition, innovation, and supply chain integration. Our report evaluates their relative positions, strategic moves, and the implications of their activities for the broader industry.
Si Precesors for Semiconductor Market
Industry Dynamics: Technical, Regulatory, and Geopolitical Factors
Several critical dynamics influence the market environment for silicon parts in etching. From a technical standpoint, the requirements for high-purity monocrystalline silicon components are stringent. These parts must meet rigorous impurity and defect standards, including zero dislocation defects, often achieved using Magnetic Czochralski (MCZ) growth techniques. The quality of the silicon material directly impacts the performance and lifespan of the etching components, making material science and manufacturing precision key differentiators for suppliers.
The consumable nature of these parts also plays a role in market dynamics. Components such as focus rings and electrodes are typically replaced after approximately 200 wafer processes in plasma etching equipment. This replacement cycle creates a steady demand flow but also necessitates efficient inventory management and supply chain responsiveness from both suppliers and end-users. Factors affecting process duration, such as changes in etching chemistry or device architecture, can alter replacement frequencies and thus influence consumption rates.
Geopolitical factors further complicate the landscape. The concentration of semiconductor manufacturing investments in Asia Pacific, particularly in South Korea and China, creates regional supply-demand imbalances and opportunities. Supply chain resilience, trade policies, and local content requirements can affect the flow of silicon parts across borders. Understanding these geopolitical undercurrents is essential for companies planning global sourcing strategies or market entry.
Strategic Value of the Research Report
PW Consulting's Worldwide Silicon Parts for Etching Market report is designed to deliver actionable intelligence for decision-makers. By synthesizing market size data, growth projections, segmentation insights, and competitive analysis, the report provides a holistic view of the industry's current state and future direction. The detailed segmentation analysis allows clients to pinpoint growth opportunities within specific types, applications, and regions, while the competitive landscape assessment offers context for strategic positioning.
The forecast period from 2026 to 2032 is critical for planning capital expenditures, capacity expansions, and product development initiatives. With a projected CAGR of 9.15 percent, the market presents significant opportunities, but realizing them requires a nuanced understanding of the underlying drivers and constraints. Our research equips stakeholders with the data and analysis needed to make informed decisions, mitigate risks, and capitalize on emerging trends.
Whether you are a silicon component manufacturer seeking to expand your market presence, an equipment OEM evaluating supply chain options, or an investor assessing the semiconductor materials sector, this report offers the depth and breadth of analysis required to navigate the complexities of the worldwide silicon parts for etching market. The insights contained within are derived from rigorous methodologies and a deep understanding of industry dynamics, ensuring that you have a reliable foundation for your strategic planning.
To access the full spectrum of data, detailed segment breakdowns, and comprehensive company profiles, we invite you to explore the complete report. The full intelligence package provides the granular details necessary to translate market insights into concrete business actions, empowering you to stay ahead in a rapidly evolving industry.
For detailed analysis of this topic, please visit the official page: Worldwide Silicon Parts for Etching Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com