

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aviation Cabin Management Market to Hit $5.8B by 2032, Growing at 6.1% CAGR

Executive Briefing: Why the Aviation Cabin Management System Market Demands Strategic Attention in 2026
The aviation cabin is no longer a passive environment. It has evolved into a highly integrated digital ecosystem where passenger experience, operational efficiency, and safety certification intersect. As airlines, business jet operators, and defense contractors navigate an increasingly complex technology landscape, the Aviation Cabin Management System (CMS) market stands at a critical inflection point. Our latest comprehensive market study, covering historical performance from 2020 through 2025 and projecting forward across the 2026 to 2032 forecast period, delivers the strategic intelligence required to navigate this transformation with precision.
For executives making capital allocation, procurement, and partnership decisions in 2026, understanding the trajectory of cabin management technology is not optional. It is a competitive necessity. This briefing outlines the structural forces shaping the market, the competitive dynamics at play, and the actionable frameworks embedded in our full report. It is designed to demonstrate the depth of our analysis while underscoring why a complete, data-rich assessment is essential for informed decision-making.
The Macro Landscape: Growth Trajectory and Market Scale
The global cabin management system market has demonstrated steady, compounding expansion over the past half-decade. Drawing on verified historical data from 2020 through 2025, the market has progressed from an estimated 2.85 billion USD in baseline revenue to approximately 3.85 billion USD in the most recent valuation year. This growth reflects sustained investment in cabin modernization, rising passenger expectations for seamless digital experiences, and the ongoing integration of connectivity and entertainment platforms into core cabin architectures.
Aviation Cabin Management System Market
Our forecast model projects continued upward momentum through 2032, with the market expected to reach approximately 5.83 billion USD by the end of the forecast horizon. This trajectory is underpinned by a compound annual growth rate of 6.1 percent, a figure that reflects both organic expansion and the structural shift toward software-defined cabin environments. Importantly, this growth rate is not uniform across all operator categories or platform types. The interplay between hardware refresh cycles, software upgrade pathways, and regional procurement rhythms creates distinct value pockets that require granular analysis to exploit effectively.
For strategic planners, the key takeaway is that the market is large enough to support meaningful investment but dynamic enough to reward those who understand where value concentrates. The full report dissects these patterns across multiple dimensions, providing the quantitative backbone needed to validate procurement strategies, forecast demand, and benchmark competitive positioning. Readers seeking the complete dataset—including detailed revenue projections, regional breakdowns, and type-specific growth coefficients—are encouraged to access the full report page, where the underlying models and scenario analyses are fully available.
Commercial, Private, and Military Applications: Divergent Demand Drivers
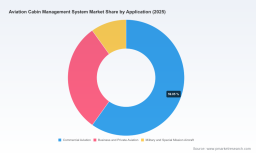
The cabin management ecosystem serves three distinct operational verticals, each with its own procurement cadence, technical requirements, and value propositions. Commercial aviation operators prioritize reliability, passenger throughput, and integration with existing in-flight entertainment and connectivity architectures. Business and private aviation clients, by contrast, emphasize customization, luxury interface design, and the ability to future-proof cabins against rapidly evolving consumer device ecosystems. Military and special mission platforms introduce an additional layer of complexity, demanding hardened architectures, secure communications integration, and compliance with mission-critical reliability standards.
These divergent requirements create a market structure where a single vendor rarely dominates across all segments. Instead, competitive advantage emerges from how effectively suppliers align their product roadmaps with the specific rhythms of each vertical. Our report maps these alignment opportunities in detail, examining how retrofit cycles, new aircraft delivery schedules, and aftermarket service contracts shape demand across commercial fleets, VIP airframes, and specialized defense platforms. The analysis reveals where procurement windows open, where integration bottlenecks persist, and where long-term service agreements can stabilize revenue streams amid volatile capital expenditure cycles.
Regional Dynamics and the Fragmentation of Demand
Geographic variation in fleet composition, regulatory environments, and aftermarket infrastructure creates a complex demand map. Mature markets with established fleet renewal programs exhibit different purchase behaviors than emerging regions where aftermarket retrofits and lease-market activity drive initial CMS adoption. The full report provides a comprehensive regional assessment that examines how local manufacturing ecosystems, aviation authority certification pathways, and airline business models influence procurement timing and vendor selection.
Understanding regional nuance is critical for companies evaluating market entry, partnership formation, or capacity expansion. A strategy that works for a narrow-body retrofit program in one geography may not translate to a wide-body new delivery campaign in another. Our analysis disentangles these variables, offering a structured view of where demand is concentrated, where competitive intensity is highest, and where underserved niches present strategic opportunity. The complete regional matrices, including historical share trends and forward-looking allocation scenarios, are detailed in the full report.
Competitive Landscape: Who Is Shaping the Next Generation of Cabin Management
The competitive field in cabin management systems is defined by a blend of incumbent aerospace suppliers, specialized cabin integrators, and technology-forward newcomers. Several key enterprises illustrate the spectrum of strategic approaches currently shaping the market.
Collins Aerospace, operating under RTX, has advanced its Venue cabin management platform with wireless control capabilities through a dedicated cabin command application, alongside 4K smart monitors and an upgraded graphical user interface. The system supports deployment across more than 50 aircraft models, reflecting a strategy centered on broad platform compatibility and continuous interface modernization for business aviation cabins.
Honeywell International has focused its efforts on the Ovation Select cabin management system, which integrates entertainment, control, and communications functions while optimizing for consumer device connectivity. Its positioning emphasizes seamless interoperability with passenger-owned technology, a key differentiator in the business jet segment where personal device integration is a primary purchase driver.
Diehl Aviation has developed the CANSAS platform, a modular digital control architecture designed to manage cabin functions through a networked, service-oriented framework. Its approach highlights the broader industry shift toward smart cabin technologies and the integration of ancillary systems, such as advanced waste management and environmental control, into a unified cabin management layer.
Lufthansa Technik has strengthened its footprint with its nice cabin management and IFE portfolio, including 4K and HD variants tailored for VIP and business jet applications. Recent innovations have introduced hidden touch display architectures integrated directly into cabin surfaces, reflecting a design philosophy that prioritizes minimalism and uninterrupted aesthetic integration.
Astronics Corporation serves the VIP and VVIP segment with its Avenir IFE and CMS offering, leveraging high-bandwidth Ethernet, native 4K video delivery, fiber optic infrastructure, and comprehensive cabin control functionality. Its architecture is engineered to support the demanding bandwidth and reliability requirements of ultra-luxury and government-operated airframes.
Rosen Aviation has pursued an operator-centric design philosophy with its Celestia CMS platform. Built on an IP-based distributed network architecture, the system emphasizes modularity, redundancy, and high customization for luxury cabin environments, allowing operators to configure control logic and interface layout according to specific operational workflows.
DPI Labs offers the SmartLink decentralized cabin management system, which integrates lighting, entertainment, and comfort control across multiple aircraft categories, including VVIP platforms. Its decentralized architecture aims to reduce single points of failure while maintaining unified command across distributed cabin zones.
Aviation Oxygen Systems Market
Jet Aviation has expanded its capabilities through in-house IFX IFE and CMS development, tailoring cabin control systems for refurbishment projects. Its recent activities demonstrate a growing trend among service-oriented integrators to internalize CMS development, thereby capturing more value along the customization and installation chain.
These firms illustrate a market where differentiation is increasingly driven by architecture choices, user interface sophistication, and the ability to integrate with broader cabin ecosystems. The full report provides detailed competitive profiles, product positioning maps, and an assessment of recent product launches and installation milestones that signal shifting strategic priorities. Access to the complete competitive intelligence section is available through the full report page.
Industry Dynamics: Certification, Standardization, and Cost Realities
The cabin management market does not operate in a regulatory vacuum. Safety-critical software and hardware components must satisfy stringent certification requirements, including DO-178C for airborne software and DO-254 for hardware design assurance. For Level A applications, the cost and timeline implications of compliance can be substantial, with certification pathways extending beyond 24 months and incurring expenditures that reach into the millions of USD. These dynamics influence product roadmaps, delay time-to-market for new features, and shape the competitive advantage of established vendors with mature certification infrastructure.
Parallel to certification complexity is the challenge of standardization. The absence of uniform interfaces and data protocols across aircraft models and fleets creates integration friction, particularly when operators seek to modernize legacy cabins or combine CMS platforms with third-party entertainment and connectivity solutions. Retrofit projects must navigate configuration-specific constraints, and typical upgrade expenditures can vary significantly depending on aircraft type, cabin layout, and the scope of subsystem integration. Our report examines how these factors shape procurement decisions, influence vendor selection criteria, and create opportunities for modular, standards-aligned architectures that reduce long-term integration overhead.
For executives, the practical implication is clear: technology superiority alone does not guarantee market success. Certification readiness, integration flexibility, and total cost of ownership over the aircraft lifecycle are equally decisive. The full report quantifies these dynamics where possible and provides qualitative frameworks for evaluating vendor claims against operational realities.
What the Full Report Delivers: Actionable Intelligence for 2026 Decision-Makers
This market study is structured to support concrete strategic actions rather than abstract observation. Inside the full report, readers will find a comprehensive segmentation analysis that disaggregates market size and growth trajectories across type, application, and regional dimensions. The report includes historical time-series data tracing performance from 2020 through 2025, forward-looking forecasts extending through 2032, and scenario-based sensitivity analysis for key demand drivers.
Additional sections provide a detailed competitive landscape assessment, covering product architectures, recent launch activity, installation milestones, and strategic positioning for each major participant. The report also examines market concentration metrics, offering insight into the balance between incumbent dominance and the emergence of specialized challengers. Procurement and aftermarket dynamics are analyzed alongside certification and integration challenges, giving operators and suppliers a shared reference point for evaluating feasibility and risk.
The study is designed for use by strategy teams, procurement directors, product managers, and investment analysts who need to translate market signals into actionable plans. Whether the objective is to benchmark a current platform against emerging alternatives, identify partnership or acquisition targets, or forecast demand for a specific aircraft segment, the full report provides the structured evidence base required to move from hypothesis to decision.
Conclusion: A Market in Motion, and the Need for Precision Intelligence
The aviation cabin management system market is expanding, evolving, and fragmenting simultaneously. Sustained growth through the end of the decade creates opportunity, but the distribution of that opportunity is uneven. Vendors and operators alike must navigate certification complexity, integration constraints, divergent segment requirements, and intensifying competition from both established aerospace suppliers and agile cabin specialists.
In this environment, high-level summaries and aggregate figures are necessary but insufficient. The decisions that determine competitive outcomes in 2026 and beyond require detailed visibility into where value is created, which architectures are gaining traction, how certification and retrofit economics shape procurement timing, and where regional demand patterns diverge from global averages. Our full market research report delivers that depth. It is built to equip decision-makers with the evidence, frameworks, and forward-looking projections needed to act with confidence.
For organizations serious about positioning themselves within the next wave of cabin management innovation, the complete analysis is essential. The full dataset, competitive breakdowns, and strategic recommendations are available through the complete report page, where the full scope of our research can be reviewed in detail.
For detailed analysis of this topic, please visit the official page: Aviation Cabin Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com