

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CMP Equipment Market Hits $3.87B in 2025, Rises to $6.86B by 2032 with 8.5% CAGR

Global CMP Equipment Market 2026-2032: Strategic Intelligence for Semiconductor Investments
The chemical mechanical polishing (CMP) equipment sector stands at a pivotal juncture. As the semiconductor industry races to meet the insatiable demand for advanced logic, high-bandwidth memory, and power devices, planarization technology has evolved from a backend processing step to a critical enabler of device performance and yield. PW Consulting's latest Worldwide CMP Equipment Market research offers a comprehensive, data-driven roadmap for navigating this complex landscape through 2032. This article outlines the strategic imperatives, market architecture, and competitive dynamics that corporate leaders must understand to capitalize on the next growth cycle.
A Market Defined by Structural Growth and Technological Inflection Points
Drawing on a robust historical dataset spanning 2020 through 2025 and extending a forward-looking forecast to 2032, our analysis captures a market experiencing sustained expansion. The global CMP equipment market generated revenue of approximately $3,872.66 million in 2025, having grown from $2,420.50 million in 2020. This trajectory reflects not merely cyclical upturns but a fundamental shift in manufacturing requirements driven by node scaling, advanced packaging adoption, and the proliferation of compound semiconductor substrates. Looking ahead, the market is projected to reach $4,165.01 million in 2026 and continues its upward arc, with a compound annual growth rate (CAGR) of 8.5 percent through the 2026-2032 forecast period, ultimately surpassing the $6,800 million threshold by 2032.
Such growth is not uniform across all segments or geographies. The market architecture is shaped by distinct demand drivers: the migration toward 300mm wafer processing for advanced nodes, the resurgence of 200mm capacity for mature and specialty technologies, and the emergence of dedicated tooling for power and optoelectronic materials. Geographic demand remains heavily influenced by the concentration of wafer fabrication capacity, with Asia Pacific accounting for the predominant share of equipment deployment, while North America, Europe, and the rest of the world contribute complementary growth driven by reshoring initiatives, sovereign chip programs, and specialized R&D ecosystems. Understanding how these regional and application-level forces interact is essential for capacity planning, supply chain resilience, and go-to-market strategy.
Inside PW Consulting's Worldwide CMP Equipment Market Report
Our flagship study is engineered to translate macro trends into actionable intelligence. Rather than offering a superficial overview, the report delivers an integrated analytical framework designed for executives, capital allocators, and strategic planners. The following components form the backbone of the research:
- Comprehensive Market Sizing and Forecasting: A granular, bottom-up and top-down reconciliation of historical revenues from 2020 to 2025, extended through scenario-based projections to 2032. The forecast model incorporates equipment unit shipments, average selling price dynamics, and technology migration curves to capture both baseline and upside cases.
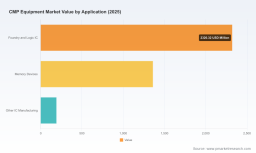
- Segment-Level Architectural Analysis: Deep dives into market segmentation by equipment type—including 300mm, 200mm, and other specialized CMP platforms—and by application, covering foundry and logic IC manufacturing, memory devices, and other IC manufacturing segments. Each segment is evaluated for growth drivers, technology readiness, substitution risks, and capacity utilization trends.
- Regional Demand and Deployment Mapping: An assessment of how wafer fab expansion, logic and memory capacity investments, and regional policy incentives shape equipment procurement cycles. The analysis contextualizes supply-demand balances, lead-time dynamics, and localization requirements that influence procurement decisions.
- Competitive Landscape and Strategic Positioning: Detailed profiles of the ten most influential companies shaping the CMP equipment ecosystem. Each profile examines product portfolio strength, technology differentiation, target end-markets, and strategic momentum, enabling a clear view of where incumbents hold advantages and where challengers are carving out niches.
- Technology and Process Evolution: An evaluation of advancements in slurry composition, pad materials, endpoint detection, and AI-driven process control. The report assesses how these innovations impact tool performance, consumable economics, and fab integration complexity, with particular attention to sub-3nm logic and advanced packaging workflows.
- Regulatory and Input-Material Dynamics: A focused examination of how environmental regulations targeting per- and polyfluoroalkyl substances (PFAS) are reshaping pad material development priorities and supplier roadmaps, alongside supply tightness in petro-based polyurethane affecting CMP pad production costs in key regions.
- Strategic Playbooks and Investment Frameworks: Actionable guidance for equipment manufacturers, fab operators, and investors on capacity expansion timing, product roadmap alignment, partnership structures, and risk mitigation in a market characterized by high concentration and rapid technology refresh cycles.
Competitive Landscape: Concentration, Differentiation, and the Battle for Process Excellence
The CMP equipment market is defined by pronounced competitive concentration, a structural feature that carries significant implications for pricing power, innovation velocity, and customer negotiating leverage. Our analysis indicates a high degree of market consolidation, with the top three players commanding an estimated 85.5 percent share and the top five firms collectively representing approximately 92.2 percent of total market revenue. This concentration reflects the capital-intensive nature of tool development, the stringent qualification requirements of leading logic and memory fabs, and the long-term service and consumable relationships that reinforce incumbency.
Within this consolidated framework, competitive differentiation is increasingly driven by process control sophistication, substrate versatility, and the ability to integrate CMP workflows with adjacent process steps. Applied Materials continues to reinforce its leadership position through platforms such as the Reflexion GT and Mirra families, with a strong emphasis on 300mm wafer processing and AI-driven process control tailored for sub-3nm applications. Ebara Corporation maintains a formidable presence in memory fabs, leveraging its FREX-series single-wafer planarization systems and multi-zone pressure control paired with optical endpoint detection to meet the repeatability demands of high-volume memory production. Tokyo Seimitsu (ACCRETECH) pursues a differentiated strategy by integrating CMP systems with dicing and grinding equipment, addressing the precision planarization requirements of advanced packaging and thinned wafer applications.
A parallel competitive dynamic is emerging around compound semiconductors and specialty substrates. Revasum focuses on CMP and grind-polish systems for silicon carbide (SiC) and gallium nitride (GaN) power semiconductor substrates, targeting 150-200mm wafers in electric vehicle and power applications—a segment with distinct process requirements and growing volume trajectories. Entrepix, operating under Amtech Systems, provides a broad CMP technology portfolio encompassing equipment, consumables, service, and a notable emphasis on refurbished systems and SiC wafer processing, creating a compelling value proposition for cost-sensitive deployments. Axus Technology supplies advanced CMP process development, production foundry services, and equipment solutions, bridging the gap between process refinement and production-scale deployment.
The market also includes specialized players addressing precision lapping, R&D, and optical and compound semiconductor applications. Lapmaster Wolters and Logitech focus on ultra-high surface quality requirements for compound semiconductors, optics, and research environments, where surface finish and minimal defectivity are paramount. Okamoto Machine Tool Works contributes precision grinding and CMP equipment for wafer planarization, while Alpsitec provides specialized CMP solutions for semiconductor manufacturing. The breadth of these profiles underscores that "CMP equipment" is not a monolithic category but a set of application-specific tool families, each with its own technology roadmaps, qualification cycles, and customer engagement models.
Industry Dynamics: Materials, Regulation, and the Acceleration of Demand
Beyond the competitive arena, several intersecting forces are reshaping the CMP equipment value chain. On the materials side, supply tightness in petro-based polyurethane is influencing CMP pad production costs and availability, particularly in North America and Europe. This constraint is prompting manufacturer scrutiny of pad sourcing strategies, inventory buffers, and alternative material pathways. Simultaneously, environmental regulations restricting per- and polyfluoroalkyl substances (PFAS) are actively reshaping CMP pad material development priorities, compelling suppliers to accelerate the qualification of compliant materials without compromising polishing performance or pad life. These dual pressures are elevating the strategic importance of consumable ecosystems and the tool-consumable co-optimization that leading fabs increasingly demand.
On the demand side, the expansion of semiconductor fabrication facilities and the scaling of advanced logic and memory production are primary engines of CMP equipment and consumables demand. The proliferation of new fab capacity, coupled with technology transitions that require more planarization steps per wafer, is strengthening the long-term demand outlook. This trend is reinforced by the growing relevance of hybrid bonding and advanced packaging, where CMP slurry and tools play an enabling role in achieving the surface quality and alignment precision necessary for high-performance interconnects. Recent developments illustrate this momentum: in September 2025, Fujifilm Corporation launched advanced packaging CMP slurry optimized for hybrid bonding technology to support AI semiconductor performance, signaling the intersection of materials innovation and packaging roadmaps. In July 2025, Clarkson University's CAMP and NCCAVS hosted the 27th International Symposium on Chemical-Mechanical Planarization, spotlighting leading-edge CMP technologies and process innovations. In October 2025, SEMICON West 2025 in Phoenix featured CMP-related technologies and awards, underscoring growth in U.S. semiconductor manufacturing and the expanding role of post-CMP applications.
These developments are not isolated events; they are indicators of a structural shift in which CMP is increasingly central to the performance equation across logic, memory, and power device roadmaps. For equipment suppliers, the implication is clear: process adaptability, consumable integration, and service responsiveness are becoming as critical as raw tool capability. For fab operators, the challenge lies in balancing technology migration timelines with consumable cost management and qualification risk.
Worldwide CMP Equipment Market
Strategic Implications for 2026 Decision-Making
As organizations finalize their 2026 capital allocation and product strategy, several themes emerge from our analysis as particularly actionable:
- Align capacity planning with segment-specific demand curves. The divergence between 300mm advanced-node demand and the sustained relevance of 200mm and specialty CMP for power, optoelectronic, and mature-node applications requires differentiated investment theses. Over-indexing on a single substrate or application can expose a portfolio to cyclical or substitution risk.
- Treat consumables and process control as strategic assets, not overhead. In a market where pad and slurry dynamics are influenced by material constraints and regulatory shifts, co-developing tool-consumable-process solutions can create defensible differentiation and stabilize total cost of ownership for customers.
- Monitor concentration dynamics when assessing partnership and procurement options. High market concentration among leading vendors can translate into reliable technology roadmaps but also into negotiating complexity and dependency risk. A balanced sourcing strategy—combining primary platform relationships with specialized or refurb capability where appropriate—can enhance resilience.
- Integrate regional policy and fab expansion signals into scenario planning. With Asia Pacific driving the majority of equipment deployment and North America and Europe expanding capacity under sovereign and reshoring incentives, regional lead-time, localization, and service-network considerations will increasingly influence procurement timing and vendor selection.
- Anticipate technology refresh cycles tied to AI, advanced packaging, and power semiconductor growth. The trajectory toward sub-3nm logic, hybrid bonding, and SiC/GaN power applications will intensify requirements for precision planarization, endpoint detection, and process repeatability. Equipment roadmaps should be evaluated against these end-market inflection points rather than historical baseline volumes alone.
Conclusion: From Macro Signals to Micro Decisions
The Worldwide CMP Equipment Market research from PW Consulting is designed to bridge the gap between high-level market signals and the micro-level decisions that determine competitive advantage in 2026 and beyond. The data tell a clear story of sustained growth, technological differentiation, and a concentrated but increasingly segmented competitive landscape. Yet the most valuable insights lie beneath the headline figures—in the interaction between material constraints and process innovation, in the way regional fab expansion reshapes procurement cycles, and in the strategic choices that determine whether a company leads, follows, or risks obsolescence as planarization requirements intensify across logic, memory, and power device roadmaps.
This article has provided a strategic preview of the market architecture, competitive dynamics, and industry forces that will shape decision-making in the coming years. The full report extends far beyond this overview, delivering detailed segmentation analysis, company-by-company strategic assessments, regional and application-level demand breakdowns, and scenario-based forecasts calibrated to different technology adoption and fab expansion trajectories. For executives seeking to translate market intelligence into concrete investment and operational decisions, the complete research offers the granular, actionable detail required to act with confidence.
CMP Polishing Pads Market
To access the full Worldwide CMP Equipment Market report, including complete segmentation data, competitive profiles, and forward-looking scenarios through 2032, please visit our research portal and secure your copy of this essential strategic resource.
For detailed analysis of this topic, please visit the official page: Worldwide CMP Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com