

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Molten Salt Pumps Market Hits $834M in 2025, Forecast 9.1% CAGR to 2032

Navigating the Thermal Frontier: Strategic Insights from the 2026 Worldwide Molten Salt Pumps Market Research
Executive Overview
As global industries accelerates their transition toward renewable energy infrastructure and advanced nuclear technologies, the molten salt pump market stands at a critical inflection point. The sector has evolved from a niche mechanical engineering segment into a cornerstone of high-temperature thermal energy management. This transformation is driven by the urgent need for reliable thermal energy storage (TES) in concentrated solar power (CSP) systems and the emerging requirements of next-generation molten salt reactors (MSRs).
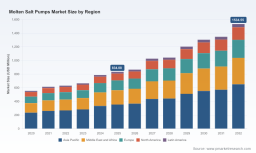
Our latest market research initiates with a base year of 2025 and captures historical performance spanning 2020 through 2025. This retrospective analysis provides the groundwork for a comprehensive forecast period extending through 2032. The data indicates that the worldwide revenue for molten salt pumps reached approximately 834 million USD in 2025, building upon a steady trajectory from 554 million USD in 2020. As we project forward, 2026 marks the beginning of an intensified growth phase, where revenue is expected to surpass 865 million USD, effectively setting the stage for a period of accelerated expansion across the remainder of the decade. By the conclusion of the forecast window in 2032, the market is projected to exceed 1.5 billion USD in annual revenue, reflecting a compound annual growth rate of 9.1 percent over the forecast period. These figures are not merely statistical; they represent a fundamental reshaping of capital investment in high-temperature fluid handling infrastructure.
Market Segmentation and Structural Dynamics
The structural composition of the molten salt pump market reveals distinct preferences and engineering priorities across pump architectures, end-use applications, and geographic deployments. Understanding these segmentation layers is essential for identifying where capital is concentrating and how supply chains are adapting to the specific demands of molten salt service.
When examining pump architectures, the market is dominated by three primary configurations: vertical cantilever pumps, vertical submerged pumps, and other high-temperature special pumps. The vertical cantilever design has emerged as the most significant contributor to market revenue, accounting for the largest share of overall uptake due to its robustness in handling solidifying salts and minimal leakage risks. Vertical submerged pumps follow as a strong secondary segment, favored for their ability to handle fluids in deep storage tanks and their reduced footprint requirements. The remaining category encompasses specialized high-temperature solutions tailored for unconventional operating environments, including experimental reactor loops and highly corrosive chemical processing scenarios. These design preferences are not static; they evolve alongside advancements in metallurgical engineering and thermal management capabilities.
From an application perspective, the market is anchored by three core domains with clearly differentiated growth drivers. Concentrated solar power represents the dominant application segment, where molten salt pumps serve as the circulatory system for thermal storage loops and power block heat transfer. Thermal energy storage applications function as a critical enabler, supporting both standalone storage projects and hybrid CSP-plus-storage deployments. Meanwhile, molten salt reactor technologies for advanced nuclear power generation constitute an emerging frontier, characterized by pilot-scale validation and early-stage commercial scaling. Industrial chemical processing adds a supplementary layer of demand, particularly in sectors requiring high-temperature transfer of corrosive salt mixtures. Each application domain imposes unique operational constraints, from temperature thresholds exceeding 600 degrees Celsius to stringent requirements for corrosion resistance and long-cycle maintenance intervals.
Geographically, the market exhibits a clear concentration pattern centered on regions with substantial renewable energy mandates and industrial manufacturing bases. Asia Pacific leads in absolute market contribution, reflecting large-scale CSP project pipelines, domestic manufacturing capabilities, and rapid deployment of thermal storage infrastructure. The Middle East and Africa follow as a closely trailing region, benefiting from abundant solar irradiance, government-led energy diversification initiatives, and strategic investments in utility-scale solar thermal facilities. Europe maintains a mature but steadily growing presence, driven by policy frameworks supporting renewable integration and industrial decarbonization objectives. North America and Latin America represent smaller but strategically important markets, with growth trajectories influenced by regional utility procurement cycles and advanced energy storage pilot programs. The geographic distribution of revenue underscores the interplay between policy, resource availability, and manufacturing localization.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a moderately concentrated competitive environment. The top three participants collectively command a combined market share of approximately 42.5 percent, while the top five firms expand this influence to nearly 58.8 percent. This level of concentration suggests a landscape where established engineering firms with proven high-temperature pump heritage hold significant leverage, yet there remains meaningful room for specialized players and regional manufacturers to capture niche demand. Understanding the competitive posture of leading organisations is vital for assessing supply chain resilience and procurement strategy.
Sulzer, headquartered in Winterthur, Switzerland, has positioned itself as a leading solutions provider for CSP applications. The company offers a portfolio of vertical mixed-flow molten salt circulation pumps designated for parabolic trough and central tower configurations, with capacities reaching up to 4,000 cubic meters per hour. Sulzer supplies both hot and cold molten salt pump systems for major CSP installations and has recently expanded its operational footprint through targeted contract awards. In September 2025, Sulzer signed an agreement with Highview Power to deliver eight molten salt pumps alongside cryopumps and auxiliary services for a molten salt energy storage facility, reinforcing its role in thermal storage infrastructure. Earlier, in July 2024, the company was selected to supply both hot and cold molten salt pumps, including three cold pumps equipped with 2.6-megawatt motors, for a significant 100-megawatt CSP tower project in China, with manufacturing coordinated through its Suzhou plant. Sulzer has also emphasised its contribution to high-temperature molten salt energy storage systems in industry publications, highlighting the importance of specialised designs for demanding operational environments.
Flowserve, based in Irving, Texas, USA, provides a distinct engineering approach through its Molten Salt VTP vertical turbine pump wet pit designs. These pumps are specifically engineered for molten salt service in CSP plants and are designed to support 30-year operational lifespans. Flowserve emphasises advanced thermal mapping techniques to mitigate heat distortion, a critical consideration for long-duration service under extreme thermal cycling. This focus on durability and lifecycle management positions the company as a preferred partner for utility-scale CSP deployments where uptime and reliability are paramount.
WEM Pumps, LLC, operating from Burlington, New Jersey, USA, has built a reputation since 1950 as a specialist in high-quality molten salt transfer pumps. The company serves a diverse application base that includes steel production, battery systems, and experimental molten salt reactors. Its long-standing heritage in high-temperature transfer applications provides a historical foundation that resonates with projects seeking proven performance under aggressive operating conditions.
Hayward Tyler, headquartered in Burlington, Vermont, USA, with global operations, manufactures custom high-temperature pumps for molten salt, liquid metal, and liquid sodium applications at temperatures reaching 750 degrees Celsius and above. The company targets advanced nuclear and concentrated solar power systems, aligning its engineering capabilities with the stringent material and thermal requirements of next-generation energy infrastructure. Recent industry context highlights the U.S. Department of Energy Gen3 CSP projects, which focus on improving reliability and longevity of high-temperature chloride salt pumps through material and design advancements, projects in which Hayward Tyler has been engaged.
Rheinhütte Pumpen, under ITT, operates from Wiesbaden, Germany, and produces submersible chemical pumps alongside specialised designs for conveying molten salts in CSP and industrial applications. The company’s expertise in corrosion-proof and wear-resistant materials dates back to nitrate salt experience established in the 1950s, providing a technical foundation for handling corrosive salt mixtures in demanding service environments.
Auro Pumps, based in Ahmedabad, Gujarat, India, manufactures molten salt pumps and complete molten salt systems and loops capable of operating up to 850 degrees Celsius for high-temperature industrial processes and solar applications. The company emphasises in-house engineering capabilities, enabling integrated system delivery that can reduce integration complexity for end users.
Zigong Pump & Valve, located in Zigong, China, produces vertical high-temperature submerged molten salt pumps specifically targeted at solar thermal power plants. Its regional manufacturing base supports the growing Asian Pacific deployment pipeline and provides localized supply options for domestic and export markets.
Nagle Pumps, part of the Ruthman Companies and operating from Chicago Heights, Illinois, USA, is recognised for vertical cantilever pumps, including the TWO and CWO models, with established expertise in molten salt pumping applications. The company’s product lineage reflects a focus on designs that balance structural integrity with maintenance accessibility.
Jinan Warwick Pump Co., Ltd., based in Jinan, China, specialises in high-temperature molten salt pumps and related submerged and axial flow pump configurations. The company contributes to the regional manufacturing ecosystem by addressing specific high-temperature fluid handling requirements within the Chinese market and adjacent export channels.
A notable recent milestone in the sector occurred in February 2026, when Copenhagen Atomics successfully completed two years of continuous operation of a molten salt pump and test loop at its facilities in Copenhagen. This achievement validated critical components for molten salt reactors, providing empirical evidence of long-duration pump reliability in novel reactor contexts. Such validation events carry significant weight for the emerging nuclear segment of the market, as they reduce perceived technology risk and support procurement confidence for advanced reactor developers.
Technological Evolution and Material Science Implications
The operational envelope of molten salt pumps has expanded alongside advancements in material science and thermal management engineering. Pump designs increasingly incorporate specialised high-temperature alloys and cermets to handle corrosive molten salts, whether nitrate or chloride based, at operating temperatures that frequently exceed 600 degrees Celsius in CSP and nuclear applications. The corrosive nature of molten salts, combined with thermal cycling and potential solid fraction formation, demands wetted components capable of maintaining structural integrity over extended intervals.
Worldwide High Pressure Melt Pump Market
For high-temperature chloride salt service, such as mixtures of magnesium chloride, sodium chloride, and potassium chloride operating near 720 degrees Celsius, engineering specifications call for Inconel 625 utilisation in wetted components. Advanced coatings, including HVOF processes employing NiWC-based Hybrimet formulations such as NiWC3b, are applied to bearings and critical surfaces to enhance corrosion resistance and wear performance. These material choices are not incidental; they reflect systematic responses to degradation mechanisms identified through operational experience and laboratory testing. The integration of such materials directly influences pump reliability, maintenance frequency, and total cost of ownership, making metallurgical capability a key differentiator among suppliers.
Thermal management remains equally critical. The demand for molten salt pumps is fundamentally tied to the expansion of CSP with thermal energy storage and emerging molten salt reactor technologies requiring robust high-temperature circulation solutions. As these systems scale, pump designs must accommodate not only steady-state thermal loads but also transient conditions arising from plant startups, shutdowns, and emergency cooling scenarios. Advanced thermal mapping and design adaptations that mitigate heat distortion contribute to extended service life, an attribute that carries substantial economic value in utility-scale deployments where downtime translates into significant lost generation revenue.
Forecast Trajectory and Investment Implications
Looking ahead across the 2026 to 2032 forecast horizon, the molten salt pump market is positioned for sustained expansion driven by the compounding effects of renewable energy infrastructure build-out and advanced nuclear development. The 9.1 percent compound annual growth rate projected over the forecast period reflects the convergence of multiple macro drivers: increasing deployment of CSP plants with integrated thermal storage, growing interest in advanced reactor concepts that rely on molten salt as both coolant and fuel carrier, and industrial applications that demand high-temperature fluid handling in novel process configurations.
The revenue trajectory from 865 million USD in 2026 to projections exceeding 1.5 billion USD by 2032 indicates not only volume growth but also escalating unit values as pump systems incorporate more sophisticated materials, custom engineering, and integrated monitoring capabilities. Procurement strategies will need to account for lead time variability, material availability for specialised alloys, and the increasing importance of supplier qualification in long-duration reliability contexts. Capital allocation decisions should consider regional manufacturing proximity, service network depth, and the ability of suppliers to deliver integrated pump and thermal system solutions rather than standalone equipment.
Market participants should also anticipate intensifying competition as new entrants evaluate opportunities in high-temperature pump manufacturing and as established firms expand their portfolios to capture cross-application synergies. The concentration metrics observed in the current landscape suggest that scale and engineering heritage provide meaningful barriers, but the emergence of novel reactor designs and chloride salt chemistries may open pathways for companies with specialised material and coating expertise. Strategic partnerships, joint development agreements, and regional supply chain localisation are likely to become more prominent as project developers seek to de-risk supply and ensure long-term service continuity.
The Complete Intelligence Picture
This market research delivers a comprehensive operational blueprint for decision-makers navigating the molten salt pump sector. Beyond the macroeconomic figures and structural observations presented here, the full study provides granular segmentation analysis, detailed regional market size tables, application-specific revenue breakdowns, and pump type distribution data that enable precise sizing of addressable market opportunities. The report also includes deep competitive profiling, technology roadmapping, regulatory and standards context, and raw material trend analysis that collectively inform supplier selection, capacity planning, and investment prioritisation.
Our detailed segmentation analysis quantifies the revenue contribution of each pump architecture, application domain, and geographic region with exact monetary values, allowing stakeholders to identify high-growth pockets and evaluate competitive exposure with precision. The complete report further examines how evolving chloride salt chemistries, DOE-backed Gen3 CSP initiatives, and material innovation cycles are reshaping procurement criteria and engineering specifications. It also contextualises recent contract awards, milestone validations, and technology demonstrations within broader market dynamics, offering actionable intelligence for both equipment suppliers and end-user procurement teams.
For enterprises seeking to align capital deployment with the accelerating thermal energy transition, the complete research provides the level of detail required to transform high-level market awareness into executable strategy. The full dataset, regional depth, and competitive intelligence contained in this study are available through our official research portal. We invite stakeholders to access the complete Worldwide Molten Salt Pumps Market research to secure the granular intelligence necessary for informed strategic execution in the period ahead.
Worldwide Molten Salt Pumps Market
For detailed analysis of this topic, please visit the official page: Worldwide Molten Salt Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com