

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: MDEA Market Hits $670.18M in 2025, Forecasts 5.42% CAGR to 2032

Strategic Intelligence for the Global MDEA Market: Navigating the 2026-2032 Growth Trajectory
For corporate strategists, procurement leaders, and chemical industry analysts, the trajectory of N-Methyl Diethanolamine (MDEA) represents far more than a niche specialty chemical segment. It is a critical indicator of broader industrial shifts tied to gas treatment, decarbonization, and downstream chemical manufacturing. As global demand for selective acid gas removal intensifies and production geographies realign, access to precise, forward-looking intelligence becomes a decisive competitive advantage. This newly released Worldwide N-Methyl Diethanolamine (MDEA) Market research report delivers the structural clarity executives need to navigate a market projected to expand steadily from 2026 through 2032.
Worldwide N-Methyl Diethanolamine (MDEA) Market
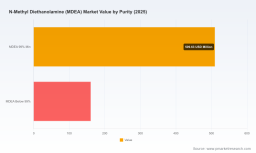
Drawing on historical performance data from 2020 through 2025, the analysis establishes a verified baseline before projecting market evolution across the next seven years. In 2020, global MDEA revenues stood at approximately 508.34 million USD. By 2025, that figure had climbed to 670.18 million USD, reflecting sustained demand across traditional gas processing applications and emerging end-use sectors. Looking ahead, the market is forecasted to reach 720.21 million USD in 2026, before advancing to 969.74 million USD by 2032. The compound annual growth rate across the forecast horizon is estimated at 5.42 percent. These aggregate figures signal a market that is not simply expanding in absolute terms, but maturing structurally. Growth is being shaped by plant investments, regional supply realignments, purity-driven pricing dynamics, and the accelerating integration of MDEA into carbon capture workflows.
What separates this research from conventional commodity tracking is its emphasis on decision-useful architecture. The study does not merely aggregate historical shipments; it dissects the operational variables that determine margin resilience, sourcing strategy, and capacity planning. Readers will find granular breakdowns of how purity specifications influence segment valuation, how application verticals allocate consumption, and how regional manufacturing footprints map against supply chain vulnerabilities. The report also maps the production economics that underpin MDEA manufacturing, recognizing that feedstock dynamics and plant-scale configurations are now central to competitive positioning.
Competitive Landscape: Scale, Specialization, and Strategic Posture
The global MDEA market is characterized by a moderately concentrated supplier base, with the top three players collectively accounting for roughly 48.4 percent of market share and the top five reaching 64.2 percent. This concentration does not imply uniformity. The competitive field is stratified between integrated global producers driving capacity expansions, formulation specialists engineering tailored solvent blends, and regional manufacturers anchoring localized supply chains for gas treating and industrial applications.
Dow Inc., headquartered in Midland, Michigan, positions MDEA as a versatile tertiary amine spanning gas treatment, detergents, urethane foams, cement grinding aids, and chemical intermediates. Its GT-grade offering for gas removal applications underscores a strategy that balances volume visibility with specification-driven differentiation. BASF SE, based in Ludwigshafen, Germany, has reinforced its standing as a major alkyl ethanolamines producer through a recent capacity expansion that increased global production capability by nearly 30 percent, pushing annual output beyond 140,000 metric tons. This move, centered at its Antwerp Verbund site, signals a deliberate scale play in a segment where operational leverage increasingly dictates cost competitiveness.
Eastman Chemical Company, located in Kingsport, Tennessee, competes on purity and formulation performance. Its Amietol M12 product is manufactured at purities exceeding 99.8 percent, targeting selective H2S removal and formulated solvent platforms such as the AdapT series for refining and natural gas streams. In April 2026, Eastman announced a price increase of 0.10 USD per pound, equivalent to 220 USD per metric ton, for Amietol M12 across North America and Latin America. The adjustment highlights how purity premiums and regional cost structures are being actively managed in a tightening supply environment.
Huntsman Corporation, headquartered in The Woodlands, Texas, emphasizes deep CO2 removal performance through its Methyldiethanolamine offerings and the JEFFTREAT MP formulated solvent. Its product logic extends across gas processing, hydrogen production, ammonia manufacturing, and LNG applications, aligning MDEA supply with the decarbonization and gas purification requirements of energy transition projects. INEOS Group, based in London, complements this landscape with MDEA and its GAS/SPEC specialty amine lines, including the CS-1, CS-1000, and CS-2000 series, engineered for H2S and CO2 removal across natural gas, LPG, ethane, and broader hydrocarbon streams.
On the regional side, Amines & Plasticizers Ltd. in Mumbai and Advance Petrochemicals Ltd. in Ahmedabad both bring decades of amines manufacturing experience to gas sweetening and decarbonization workflows. Advance Petrochemicals underscores the efficiency advantages of MDEA over MEA and DEA for sulfur impurities, a distinction that continues to shape buyer preferences in refineries and gas processing facilities. Meanwhile, Sintez OKA Group remains the sole manufacturer of MDEA ms grades A through D in Russia and CIS countries, supplying sorbent-grade material for purification of natural and process gases across oil, gas, and air-nitrogen industries. These regional anchors illustrate how localized supply, technical service, and infrastructure proximity remain critical even as global capacity expands.
Market Dynamics: Feedstock Reality, Capacity Shifts, and the Decarbonization Amplifier
Any credible MDEA strategy must begin with the chemistry and economics of production. The compound is manufactured through the ethoxylation of methylamine with ethylene oxide, a pathway that ties profitability to the availability, pricing, and logistics of key feedstocks. For a reference plant capacity of 185,000 metric tons per year, production economics consistently weigh ammonia, methanol, and ethylene oxide as foundational inputs. Feedstock volatility, therefore, is not an external footnote; it is a structural driver of cost curves, pricing cadence, and margin defense.
Methyl Diethanolamine Market
Recent feedstock data underscores this sensitivity. In the United States, Diethanolamine prices, a closely related analog and feedstock-adjacent benchmark, reached 1,450 USD per metric ton in September 2025, reflecting a 6 percent month-over-month increase and a 19 percent year-over-year rise. In Southeast Asia, Diethanolamine prices stood at 891 USD per metric ton during the same period, up 9 percent month-over-month and 17 percent higher than the prior year. These movements illustrate the geographic divergence in cost structures and the importance of regional sourcing intelligence when evaluating MDEA contract terms, inventory strategy, and substitution economics.
Capacity development is equally consequential. BASF’s September 2024 inauguration of a world-scale alkyl ethanolamines plant at Antwerp added meaningful global volume, reinforcing the view that integrated producers are positioning for sustained demand rather than cyclical spikes. Alongside this, Methanol Chemicals Company, also known as Chemanol, signed a technical licensing agreement in September 2024 for a new 25,000 metric ton per year MDEA production project, with operations slated to commence in the fourth quarter of 2027. New entrants and expanded capacities of this scale gradually reshape regional supply balances, alter freight and lead-time dynamics, and influence the bargaining power of buyers in procurement negotiations.
Beyond volume and cost, the strategic narrative of MDEA is increasingly tied to environmental and regulatory momentum. The compound is widely used in gas treating applications for selective H2S removal, but its relevance is expanding within carbon capture and storage technologies. Formulations such as ADIP ULTRA, which combine MDEA with a piperazine accelerator, are gaining traction for CO2 capture in refining, natural gas, and industrial process settings. As decarbonization mandates tighten and CCS deployments scale, MDEA’s performance profile in selective acid gas removal positions it as a material enabler of compliance and operational decarbonization. This is not a speculative tailwind; it is an active demand driver that is beginning to influence long-cycle investment decisions, solvent replacement planning, and technology selection in asset-intensive industries.
Inside the Report: The Analytical Toolkit for 2026 Decision-Making
The Worldwide N-Methyl Diethanolamine (MDEA) Market research is built for practitioners who need more than headline numbers. The report’s architecture is designed to translate complex market signals into actionable strategy across procurement, capacity planning, competitive positioning, and regional expansion. Key components include:
- Historical and forecast market sizing spanning 2020 through 2032, with base-year anchoring in 2025 and a clearly defined forecast window through 2032, enabling trend validation and forward planning under consistent assumptions.
- Segment-level analysis by purity, application, and region, structured to reveal where value concentrates, how specification premiums behave, and which end-use verticals are driving incremental consumption without exposing off-network data that should be evaluated within the full intelligence set.
- Production economics and feedstock linkage analysis, including the role of ammonia, methanol, and ethylene oxide in reference plant configurations, and the implications of regional feedstock price divergence for sourcing and inventory strategy.
- Competitive profiling of leading producers and formulators, covering product portfolios, grade specialization, capacity moves, and strategic positioning across gas treatment, chemical intermediates, coatings, textiles, and specialty solvent applications.
- Recent development tracking, including capacity expansions, announced price adjustments, and new project licensing, mapped to their likely influence on supply balance, regional availability, and contract negotiations.
- Regulatory and technology context, with attention to selective H2S removal workflows and CCS-related formulations, providing the operational and compliance backdrop that shapes long-term demand durability.
- Market concentration and structural dynamics that clarify the balance between integrated global suppliers and regional specialists, helping readers assess substitution risk, service expectations, and supply assurance requirements.
Each section is written to support concrete decisions: whether to renegotiate supply terms in a tightening feedstock environment, how to evaluate purity-related price premiums when specifying solvents for gas treating, where to monitor capacity entry for its impact on lead times and regional pricing, and how to align solvent strategy with decarbonization roadmaps that increasingly rely on selective acid gas removal performance.
Why This Intelligence Matters in 2026
The 2026 decision environment for MDEA is defined by intersecting pressures. Feedstock price dispersion across regions is complicating cost forecasting. Capacity additions are gradually altering supply balances and regional availability. Purity and formulation specialization are creating differentiated pricing tiers that reward technical specification management. At the same time, the broader energy and industrial landscape is accelerating the adoption of gas treating and carbon capture workflows that depend on high-performance amine chemistry. In this setting, companies that rely on fragmented data, anecdotal pricing signals, or backward-looking commodity indices risk misreading both opportunity and exposure.
This report is structured to close that gap. It offers a single, coherent view of how historical performance, current competitive moves, feedstock realities, and technology-driven demand intersect to shape the 2026-2032 outlook. For procurement teams, the analysis provides the context needed to assess contract timing, regional sourcing options, and purity-driven cost trade-offs. For commercial and strategy leaders, it clarifies where growth is accumulating and how competitive concentration influences market access. For industry analysts, it delivers a structured baseline for modeling demand, tracking capacity entry, and interpreting price movements within a consistent framework.
The complete dataset, segmentation detail, regional and application-level breakdowns, and proprietary analytical commentary are available through the full report. Given the strategic weight of MDEA across gas treatment, chemical intermediates, and decarbonization-linked workflows, the depth of this intelligence is best leveraged as a working reference rather than a one-time read. Readers interested in the full market model, segment architecture, and company-level competitive context are encouraged to access the source report directly to obtain the complete intelligence set and integrate it into their 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide N-Methyl Diethanolamine (MDEA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com