

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: MMA Film & Sheet Market to Hit $10.2B by 2032, Driven by 5.85% CAGR

Strategic Intelligence for 2026: Navigating the Global MMA Film & Sheet Market
Executive Overview
In an era defined by supply chain volatility, regulatory realignment, and accelerating material substitution, decision-makers in polymers, fabricated plastics, and end-use manufacturing face a common challenge: distinguishing transient market noise from durable structural shifts. The Worldwide MMA Film & Sheet Market study from PW Consulting delivers precisely the clarity required to position portfolios, pricing strategies, and capacity allocations for the 2026–2032 horizon. Grounded in a rigorous historical dataset spanning 2020 through 2025 and extended forward via a transparent forecasting methodology, the analysis captures a market currently valued at 6,850.0 million USD in 2025 and projected to reach approximately 10,198.27 million USD by 2032, reflecting a compound annual growth rate of 5.85 percent.
This trajectory is not merely a headline figure. It encodes the combined influence of optical-performance substitution in automotive glazing, sustained demand from signage and display fabrication, construction-sector adoption of extruded and cast acrylic formats, and the emergence of specialty film applications in electronics and appliances. More importantly, the report maps where growth concentrates, which structural forces accelerate or dampen value creation, and how leading producers are recalibrating their operating models in response to raw-material pressure, trade-policy turbulence, and sustainability mandates. For strategists planning capital deployment, product portfolio shifts, or regional sourcing decisions in 2026, the report functions as a decision-grade navigation tool rather than a static market snapshot.
Market Trajectory and Structural Dynamics
Growth Composition Beyond the Aggregate
The market's baseline growth path from 2025 onward reflects a composite of volume expansion, value migration across product formats, and application-level demand shifts. The historical arc from 2020 through 2025 reveals steady expansion, with revenue progressing from 5,100.0 million USD in 2020 to 6,850.0 million USD in 2025. The forecast period then carries the market through 2026 (7,079.37 million USD), 2027 (7,802.04 million USD), 2028 (8,370.42 million USD), 2029 (8,523.22 million USD), 2030 (9,264.63 million USD), 2031 (9,580.52 million USD), and 2032 (10,198.27 million USD). While these yearly figures establish the overall scale, the report’s strategic depth lies in the underlying composition of that growth, including the relative weight of extruded acrylic sheet, cell cast acrylic sheet, and MMA film categories, as well as the application-level distribution across signage and display, building and construction, automotive and transportation, electronics and appliances, and other applications.
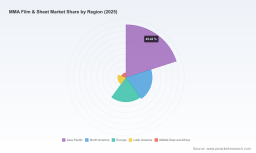
Regional variation further shapes the growth story. The market is not uniformly distributed across geographies, and the report quantifies the contribution of Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa to total revenue, revealing where demand intensity intersects with manufacturing footprint, logistics infrastructure, and local content requirements. Executives evaluating export strategy, regional sourcing, or nearshoring scenarios will find that the geographic split is not simply a descriptive breakdown but a strategic map of opportunity concentration and risk exposure.
Forces Shaping the 2026 Operating Environment
The 2026 decision environment is being shaped by multiple interacting forces, many of which are already visible in recent industry developments. On the input side, monomer and feedstock conditions have placed upward pressure on production economics. In the broader context, methyl methacrylate monomer spot prices in Asia rose 15 percent to 1,650 USD per metric ton in the fourth quarter of 2023 amid tight isobutylene supply, an indicator of how upstream constraints can cascade into sheet and film pricing. Competing pressures have also emerged from logistics disruptions, with ocean freight surcharges for chemical shipments increasing 20 percent in 2023 due to Red Sea disruptions affecting MMA imports. Such cost-channel dynamics are critical for margins in a market where producers must balance feedstock exposure, energy intensity, and finished-product pricing.
Regulatory and trade dynamics add another layer of complexity. The European Union’s REACH Annex XVII has restricted certain phthalates in PMMA sheets used in consumer goods, effective since 2020 with ongoing compliance audits, requiring manufacturers to manage formulation and documentation rigor across downstream markets. At the same time, trade-policy interventions have reshaped competitive boundaries. The US Department of Commerce imposed preliminary antidumping duties of 105 to 252 percent on PMMA sheets from China, Taiwan, and South Korea in September 2023, altering the relative attractiveness of import pathways and reinforcing the strategic value of compliant regional supply. Environmental considerations also influence end-market acceptance and recycling practice: PMMA sheets are classified as non-hazardous for recycling under the EU Waste Framework Directive, but combustion releases methyl methacrylate vapors requiring ventilation, a factor that affects processing, disposal planning, and customer-facing sustainability positioning.
Corporate responses to these pressures are already visible. Röhm GmbH implemented a global price increase for PLEXIGLAS® sheets in January 2024 due to rising raw material and energy costs. Mitsubishi Chemical Group expanded PMMA sheet production capacity at its Acrypet plant in Japan in November 2023 to meet demand for sustainable grades. Chi Mei Corporation launched the CM-503 impact-resistant PMMA sheet grade in September 2023 for automotive and construction applications. These moves illustrate how technology differentiation, capacity timing, and pricing discipline are being used to protect value in a market where input volatility and compliance requirements are increasingly intertwined.
Competitive Landscape and Strategic Positioning
Market Concentration and the Battleground of Differentiation
The competitive structure of the global MMA film and sheet market is moderately concentrated, with the top three firms accounting for 32.4 percent of market revenue and the top five firms accounting for 48.15 percent. This concentration level indicates a landscape where scale advantages, brand equity, and application-specific technical capability matter, but where meaningful share remains available to capable regional players and to firms that can translate innovation into commercially differentiated grades. In such an environment, strategic advantage is less about aggregate size alone and more about the ability to align product portfolios with the fastest-growing applications, to manage regional supply chains under trade and logistics constraints, and to demonstrate compliance and sustainability credentials that unlock or retain end-customer relationships.
The report profiles a set of central market participants whose strategies illustrate the diversity of competitive approaches. Röhm GmbH, headquartered in Darmstadt, Germany, is a global leader in PLEXIGLAS® brand PMMA sheets and films, offering cast and extruded acrylic products for displays, lighting, and construction applications. Mitsubishi Chemical Group, based in Tokyo, Japan, produces ACRYLITE® PMMA sheets and films with high optical clarity for signage, automotive, and medical uses through a global manufacturing network. Chi Mei Corporation, headquartered in Tainan City, Taiwan, is a major producer of acrylic sheets under its CM series, focusing on extruded PMMA for electronics, furniture, and sanitary ware markets. LG Chem, based in Seoul, South Korea, supplies high-performance PMMA sheets and films for automotive glazing, displays, and protective applications through integrated MMA production. Arkema, headquartered in Colombes, France, manufactures ALTUGLAS® acrylic sheets for building, advertising, and industrial fabrication worldwide. Plaskolite, LLC, located in Columbus, Ohio, USA, is North America's largest producer of extruded acrylic sheets for retail, transportation, and fabrication markets. Sumitomo Chemical Co., Ltd., also based in Tokyo, Japan, offers SUMIPEX® PMMA sheets and films for optical, electronic, and construction sectors with advanced polymerization technology.
Rather than presenting these companies as isolated profiles, the study situates them within the competitive logic of the market: who competes most intensely where, which product formats and applications create the strongest value pools, and how recent corporate actions—such as price adjustments, capacity expansions, and new product launches—signal likely competitive trajectories through 2032. For strategists, this framing helps answer essential questions about partnership selection, competitive response, and the risk of over-indexing on a single geography or format.
Inside the Report: Operational Intelligence for 2026 Planning
Coverage Designed for Decision Execution
This study is built to support concrete actions rather than abstract overview. It integrates historical performance, forward-looking projections, segmentation structure, competitive intelligence, and market dynamics into a coherent planning framework. The report's operational content is organized to help leaders interrogate assumptions, test scenarios, and identify the most valuable moves for their specific position in the value chain. Core materials include:
- A comprehensive market sizing and forecast architecture covering the 2020–2025 historical period and the 2026–2032 forecast window, providing a consistent baseline for demand modeling and revenue planning.
- Segment-level analysis across product type and application, showing how value is distributed among extruded acrylic sheet, cell cast acrylic sheet, and MMA film, and across signage and display, building and construction, automotive and transportation, electronics and appliances, and other applications.
- Regional revenue mapping for Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa, enabling geographic prioritization and risk-adjusted sourcing strategies.
- Competitive profiling of leading participants, including corporate positioning, product emphasis, and recent strategic developments, accompanied by market concentration data that clarifies the degree of consolidation and the openness of the competitive field.
- Contextual analysis of raw-material conditions, regulatory requirements, trade-policy actions, logistics disruptions, and environmental considerations, helping users incorporate external forces into pricing, compliance, and supply continuity plans.
- Practical interpretation of how cost-channel shifts, capacity additions, product launches, and policy interventions interact to shape margins, market access, and competitive positioning in the near term and through the forecast period.
These components are designed to function together. A pricing strategy, for example, gains precision when informed by regional growth weights, input-cost context, and competitor behavior. A sourcing or capacity decision becomes more robust when tied to application-level demand trajectories and trade-policy exposure. A product roadmap benefits from an understanding of which formats and end markets are expanding most reliably and where differentiation can defend against concentration-driven competitive intensity. The report therefore acts as both intelligence base and planning scaffold, not merely a reference document.
Worldwide MMA Film & Sheet Market
Why 2026 Demands a Structured View Now
The strategic stakes in 2026 are higher than a simple top-line growth reading suggests. Market participants are operating in an environment where raw-material price movements, energy cost exposure, freight surcharges, antidumping measures, and chemical compliance obligations all influence commercial outcomes simultaneously. In that setting, the value of forward visibility is not only in knowing that the market is expanding, but in understanding how expansion is distributed, what forces modulate it, and which competitive responses are already underway. The report's inclusion of recent developments—such as price actions, capacity expansions, and new-grade launches—grounds the forecast in observable behavior, giving readers a basis to anticipate rather than merely react.
For product managers, the analysis supports refinement of grade portfolios around high-viability applications and formats. For supply-chain and procurement leaders, it informs sourcing logic under shifting logistics and trade constraints. For corporate strategy and investment teams, it helps prioritize the geographies, segments, and partnership structures most aligned with durable value creation. For competitive intelligence functions, it provides a structured lens on how leading firms are positioning themselves and where the market’s center of gravity is likely to move.
How to Use This Intelligence
The strongest use of this study is as an integrated input to 2026 decision-making, not as an isolated data pull. The report's segmentation, regional mapping, concentration metrics, and contextual dynamics are most powerful when combined with internal portfolio data, cost structure, customer exposure, and risk tolerance. Readers seeking the full set of segment-level figures, regional breakdowns, application splits, and detailed competitive analysis will find the complete intelligence in the source report, where the underlying numbers and interpretive commentary are presented in full. The purpose of this overview is to demonstrate the strategic logic of the analysis and to show why the detailed dataset matters for concrete planning.
In practice, organizations that use the report effectively typically do three things. First, they align internal forecasts with the study’s baseline trajectory and segmentation structure, allowing them to test internal assumptions against an externally grounded view. Second, they incorporate the market-dynamics context—raw-material movement, regulatory requirements, trade measures, and logistics pressure—into scenario planning for pricing, procurement, and supply continuity. Third, they use the competitive and concentration information to assess vulnerability, opportunity, and the likely direction of rival behavior, especially where recent corporate actions already signal strategic intent.
Closing Perspective
The Worldwide MMA Film & Sheet Market is expanding along a clear path, but the strategic implication of that expansion depends on who is growing where, which formats and applications are leading the advance, and how external pressures are reshaping competitiveness. With an overall market projected to move from 6,850.0 million USD in 2025 to 10,198.27 million USD by 2032 at a 5.85 percent CAGR, the opportunity is substantial, yet its capture will favor organizations that can read the composition behind the aggregate and act on it with discipline. The full report provides the segment-level, regional, application-level, and competitive detail needed to convert that understanding into executable strategy for 2026 and beyond.
Methyl Methacrylate (MMA) Market
For detailed analysis of this topic, please visit the official page: Worldwide MMA Film & Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com