

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Bipolar Plate Fuel Cell Market Hits $1,933.55M in 2025, Projects 25.04% CAGR to $9.22B by 2032

The Bipolar Plate Fuel Cell Market: A Strategic Compass for the 2026 Operating Environment
The global transition toward decarbonized mobility and stationary power is no longer a theoretical trajectory. It is an operating reality defined by manufacturing scale-ups, material science breakthroughs, and regulatory frameworks that are actively reshaping capital allocation. At the center of this transformation sits the bipolar plate, a deceptively simple component that governs stack cost, power density, durability, and system-level efficiency across proton exchange membrane fuel cell architectures. For executives responsible for technology roadmaps, supply chain strategy, and portfolio positioning, understanding the bipolar plate market is no longer a niche technical exercise. It is a strategic imperative.
PW Consulting’s latest Worldwide Bipolar Plate Fuel Cell Market study is designed precisely for that imperative. This report translates multi-year market evolution into decision-grade intelligence, offering a structured view of where value is being created, which material pathways are gaining commercial traction, and how competitive dynamics are consolidating around manufacturing capability, coating innovation, and regional demand centers. The analysis below outlines the strategic rationale behind the study, previews the operational content executives will find inside, and contextualizes the market within the regulatory and technological forces defining the 2026–2032 horizon.
Why This Study Matters for 2026 Decision-Making
Strategic planning in the fuel cell component space requires more than top-line growth figures. It demands a disciplined understanding of how market expansion intersects with material selection, manufacturing throughput, end-use deployment patterns, and the competitive maneuvers of specialized suppliers. The worldwide bipolar plate market has moved from an early-adoption, pilot-scale environment into a phase where volume production, cost-per-kilowatt economics, and platform scalability determine commercial viability.
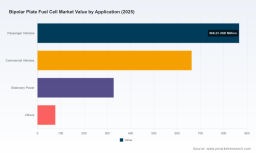
Tracked market revenue reflects this acceleration. From a baseline of approximately 545.2 million USD in 2020, the market advanced to 1,933.55 million USD in 2025, and the forecast trajectory extends toward 9,219.88 million USD by 2032, implying a compound annual growth rate of 25.04 percent across the 2026–2032 forecast period. This is not merely a growth narrative. It is a signal that demand is broadening across passenger vehicles, commercial vehicles, stationary power, and adjacent applications, while suppliers are simultaneously racing to reduce stack cost contributions, improve corrosion resistance, and meet throughput targets that make hydrogen systems competitive at scale.
For 2026 decision-makers, these macro trends create three strategic questions the report is built to answer: which material platforms are most defensible under high-volume manufacturing conditions, which application segments are driving near-term capacity requirements, and how are leading suppliers positioning around coated metallic architectures, graphite reliability, and composite hybridization? The study is structured to surface those answers without reducing them to superficial snapshots, allowing executives to align technology investment, sourcing strategy, and market-entry timing with a realistic view of market momentum.
What the Report Delivers: Operational Intelligence for Strategy Teams
The study is organized around practical usability. Rather than functioning as a static data compilation, it provides a structured decision framework that strategy, R&D, procurement, and investor teams can apply directly to commercial planning. The report’s architecture is designed to support cross-functional alignment around three core workstreams: market sizing and forecasting, segmentation logic, and competitive benchmarking.
Among the operational elements included are:
- A multi-year revenue evolution that connects historical performance with the forecast period, enabling scenario testing for capacity planning, demand forecasting, and investment prioritization
- Segment-level analysis that breaks the market into material type, application, and regional demand patterns, providing context for sourcing decisions, product strategy, and geographic deployment priorities
- A competitive landscape assessment centered on the companies setting the pace in manufacturing scale-up, coating development, stack integration, and application-specific commercialization
- Contextual tracking of recent corporate activity, including product launches, major orders, technology demonstrations, and program initiations that signal where commercial momentum is building
- Industry context around technical targets, standards adoption, material cost drivers, and manufacturing throughput requirements that influence go-to-market viability and supplier selection
This structure ensures that the report is not only descriptive but also actionable. Executives can use it to assess which material categories align with particular application requirements, how regional demand clusters relate to supply-base geography, and where supplier differentiation is emerging through precision forming, advanced coatings, integrated sealing, or high-volume production readiness. The emphasis throughout is on commercial relevance: what the market data implies for cost structures, scaling constraints, and competitive positioning in 2026 and beyond.
Worldwide Bipolar Plate Fuel Cell Market
Competitive Landscape: Differentiation Through Manufacturing, Materials, and Application Focus
The bipolar plate market is being shaped by a diverse set of global players, each pursuing distinct technological and commercial strategies. The report profiles companies that are actively defining the market’s trajectory through patented forming technologies, high-volume graphite production, advanced coating systems, and integrated stack solutions. Rather than treating these players as a simple roster, the study analyzes how their strategic choices map onto the broader demand environment.
Several competitive themes stand out. One is the continuing tension between metallic and graphite platforms. Graphite suppliers often emphasize corrosion resistance, thermal conductivity, and high-volume cost effectiveness, while metallic plate developers focus on thinner designs, precision forming, protective coatings, and integration advantages that support higher power density. This is not a binary winner-takes-all dynamic. Instead, it reflects application-specific optimization, where commercial vehicles, passenger cars, stationary systems, and heavy-duty platforms each impose different durability, cost, and manufacturability requirements.
A second theme is the growing importance of coatings and surface engineering. Advanced coating solutions are increasingly central to metallic plate competitiveness because they address corrosion resistance and conductivity without sacrificing the packaging benefits of metal architectures. Suppliers with proprietary coating technologies are therefore positioned as enablers of broader fuel cell system economics, not merely component vendors.
A third theme is regional and application-driven manufacturing expansion. Companies are scaling production footprints and securing orders aligned with commercial vehicle programs, passenger vehicle platforms, stationary power deployments, and electrolyzer-related demand. Recent activity illustrates how quickly commercialization is moving. Dana Incorporated moved forward with a metallic bipolar plate targeted at electrolyzers, combining precision forming, advanced coating, and integrated sealing to increase power density and reduce system costs for green hydrogen applications. Schaeffler Hydrogen secured new orders for PEM and AEM electrolyzer and fuel cell metal bipolar plates, building on first AEM shipments. Feintool secured a high-volume order for ready-to-install metallic bipolar plates for a leading Chinese fuel cell manufacturer, with production initiated at its Taicang facility for commercial vehicles, buses, and cars. EKPO Fuel Cell Technologies, via ElringKlinger, unveiled a high-power fuel cell stack with enhanced bipolar plates for heavy-duty and stationary applications, emphasizing increased power density, efficiency, and recyclability. Alongside these commercial milestones, technologydemonstration activity such as the pilot plant for rapid, cost-effective bipolar plate production showcased at Hannover Messe 2025, and program-level initiatives such as Hutchinson’s OBI-1 project for integrated sealing under France 2030, reinforce the pace of structural innovation across the value chain.
Taken together, these developments show a market where advantage is increasingly determined by manufacturing readiness, coating maturity, stack architecture compatibility, and the ability to fulfill volume requirements for specific end-use segments. The report maps these dynamics in detail, giving strategy teams a clearer picture of who is scaling fast, who is specializing by application, and where differentiation is likely to persist.
Market Dynamics Shaping 2026 Strategy
Beyond sizing and segmentation, the study situates the bipolar plate market within a broader set of technical, regulatory, and cost-driven dynamics. These forces matter because they define the practical limits of competitiveness. A fuel cell stack may demonstrate strong laboratory performance, but commercial adoption depends on meeting cost-per-kilowatt thresholds, durability targets, permeation limits, manufacturing throughput expectations, and safety standards that govern deployment.
One critical influence is the regulatory and technical target environment. U.S. Department of Energy technical targets for bipolar plates in transportation applications set expectations for plate cost, weight, hydrogen permeation, and corrosion limits. Separate manufacturing capacity targets for heavy-duty fuel cells envision high throughput in single production systems. These benchmarks shape supplier roadmaps because they translate directly into feasibility criteria for commercialscale production. Suppliers that can align their designs and processes with these performance and throughput expectations are better positioned to participate in large-scale programs.
A second dynamic is cost structure. Bipolar plates account for a substantial share of PEM fuel cell stack cost, which makes material and manufacturing innovation a direct lever on system competitiveness. Industry analysis suggests that graphite plates can approach lower per-kilowatt cost at high volumes, while metallic alternatives may carry a higher cost profile in comparable high-volume scenarios. At the same time, metallic plates enable thinner designs and integrated engineering benefits that can be attractive for certain applications. Understanding where these trade-offs fall is essential for sourcing strategy, product architecture choices, and long-term cost-down planning.
A third dynamic is standardization and regional uptake. International standards governing stationary fuel cell power systems safety, performance, and installation continue to influence deployment pathways across multiple markets. Where standards are adapted and adopted, they affect certification requirements, market access, and the pace at which stationary and other application segments can scale. For multi-region strategy teams, this creates both an operational consideration and a competitive moat for suppliers with strong compliance and localization capabilities.
These forces are not background noise. They are the parameters within which revenue growth, segmentation, and competitive positioning must be interpreted. The report integrates them into the analysis so that executives can evaluate market potential with a realistic understanding of technical constraints, cost drivers, and deployment requirements.
Who Should Use This Study and How
This study is intended for strategy leaders, business development teams, technology planners, procurement professionals, and investors who need a consolidated, credible view of the worldwide bipolar plate fuel cell market. It is especially relevant for organizations evaluating supplier partnerships, assessing material-platform strategy, tracking regional demand shifts, or building investment cases around hydrogen-related components and systems.
Worldwide Flow Field Plate Market
Because the report balances macro trajectory with segmentation logic and competitive profiling, it can support multiple internal use cases. Strategy teams can use it to validate demand assumptions and identify high-growth pathways. Procurement and sourcing groups can use it to understand supplier differentiation and the commercial implications of material selection. R&D and product planning teams can use it to align development priorities with market-accepted performance and cost expectations. Investor and corporate development professionals can use it to assess where value creation is concentrated and which capabilities are becoming structurally important.
Accessing the Full Intelligence
The executive overview presented here is intentionally derived from the study’s broader architecture. To preserve analytical depth, the full report contains detailed segment structures, regional and application-level market sizing, company-specific profiling, and forecast breakdowns that cannot be fully reproduced in a summary format. Those details matter because they reveal the specific demand concentrations, material pathways, and competitive positions that shape 2026 planning decisions.
Organizations that need to move from directional confidence to precise portfolio, sourcing, or investment choices will find the complete study designed for that purpose. The full dataset, segmentation detail, and competitive benchmarking provide the operational granularity required to translate market momentum into concrete strategy. For executives seeking a rigorous, commercially grounded view of the worldwide bipolar plate fuel cell market through 2032, the complete PW Consulting study is the recommended next step.
For detailed analysis of this topic, please visit the official page: Worldwide Bipolar Plate Fuel Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com