

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Phosphor Bronze Wire Market Reaches $1.05B in 2025 with 4.5% CAGR to 2032

Global Phosphor Bronze Wire Market: Strategic Intelligence for 2026 and Beyond
The worldwide phosphor bronze wire market stands at a critical inflection point as industries reconcile supply chain resilience with escalating performance requirements. Over the historical tracking window of 2020 through 2025, the sector has demonstrated consistent upward momentum, with total revenue expanding from 840.12 million USD to 1048.5 million USD. Our latest forecast extends through 2032, projecting a compound annual growth rate of 4.5 percent that will propel market valuation to approximately 1426.88 million USD by the terminal year. For executives navigating procurement strategy, capacity planning, and competitive positioning in 2026, this trajectory is not merely a statistical exercise. It represents a structural shift in how phosphor bronze wire is sourced, specified, and deployed across electrical, mechanical, and precision manufacturing ecosystems.
This article serves as a strategic preview of our comprehensive Worldwide Phosphor Bronze Wire Market research. It distills the macroeconomic architecture, competitive fault lines, and regulatory crosscurrents that will define investment and sourcing decisions over the next seven years. Full granular intelligence, including segment-level breakdowns, regional pricing dynamics, and scenario modeling, is available through the complete report. The objective here is to equip decision-makers with the foundational context required to evaluate opportunities and mitigate exposure before committing capital or restructuring supply networks.
Why 2026 Demands a Recalibrated Market View
The base year of 2025 established a new equilibrium for the sector, with revenue settling at 1048.5 million USD after a period of post-pandemic normalization and inventory rebuilding. Forecasts for 2026 indicate a rebound to 1118.46 million USD, reflecting renewed demand pull from electrical infrastructure modernization and automotive electrification. However, the growth path is not linear. The 2027 projection of 1114.47 million USD suggests a brief plateau, likely driven by raw material price volatility, shipping cost adjustments, and regional tariff recalibrations. Only after this consolidation phase does the market resume a steadier climb, reaching 1342.64 million USD by 2030 and continuing toward 1361.14 million USD in 2031 before closing the forecast window at 1426.88 million USD in 2032.
This pattern carries direct implications for enterprise planning. Companies that treat demand as a single directional trend risk overcommitting to capacity or misaligning inventory buffers. A more disciplined approach requires understanding the inflection points, the catalysts behind the 2027 soft patch, and the downstream segments that will absorb supply during transitional periods. Our analysis maps these dynamics across multiple time horizons, enabling procurement leaders and strategic planners to synchronize purchasing cycles with anticipated market tightness and easing phases.
Beyond aggregate revenue, the structural composition of demand is shifting. End-use industries are no longer purchasing phosphor bronze wire solely on the basis of cost. They are specifying grades and tempers that satisfy tighter fatigue resistance thresholds, higher conductivity consistency, and compliance with evolving environmental directives. These specification upgrades are reshaping order profiles, lengthening qualification cycles, and elevating the strategic importance of supplier technical support. Decision-makers who internalize these shifts early will secure preferential access to constrained alloy grades and avoid costly re-qualification delays.
Structural Architecture of Demand and Supply
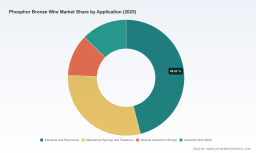
The market's growth is underpinned by a diversified application base that spans high-volume industrial uses and niche precision segments. Electrical and electronics applications represent the largest consumption pool, driven by connector manufacturing, relay components, and semiconductor equipment wiring. Mechanical springs and fasteners constitute the second pillar, benefiting from automotive suspension upgrades, industrial machinery rebuilds, and aerospace component lightening initiatives. Musical instrument strings and industrial wire mesh form smaller but highly specialized demand nodes, each with distinct metallurgical tolerances and quality assurance expectations.
Worldwide Litz Wire Market
On the alloy grade side, the market is stratified across multiple phosphor bronze formulations, each optimized for specific mechanical and electrical characteristics. Higher-strength grades dominate spring and fastener applications where cyclic loading and corrosion resistance are paramount. Medium-strength formulations serve electrical connector and contact manufacturing, balancing conductivity with formability. Lower-strength or specialized tempers cater to precision instruments, jewelry, and decorative hardware, where surface finish and acoustic or aesthetic properties drive selection. The interplay between grade availability, temper consistency, and diameter tolerance creates a multi-dimensional supply landscape that standard commodity analyses often overlook.
Geographically, demand is distributed across mature industrial economies and rapidly expanding manufacturing corridors. Asia Pacific accounts for the largest revenue share, reflecting dense electronics assembly networks, automotive component clusters, and expansive hardware production bases. Europe maintains a substantial footprint anchored in automotive engineering, precision instrumentation, and regulated electrical markets. North America contributes a significant volume driven by aerospace, industrial automation, and specialty connector manufacturing. Latin America and the Middle East and Africa represent smaller but growing consumption zones, often tied to infrastructure modernization and selective industrial upgrading. These regional distributions are not static; they evolve with trade policy, local content requirements, and the relocation of downstream assembly capacity.
To navigate this architecture effectively, buyers and investors must look beyond headline volumes. The report provides operational mapping of how each application segment interacts with specific alloy grades, how regional demand patterns align with local production capabilities, and where substitution threats or specification consolidation are most likely to emerge. This level of granularity is essential for pricing strategy, supplier qualification, and long-term capacity commitment.
Competitive Dynamics and Key Player Positioning
The phosphor bronze wire landscape is characterized by a moderately concentrated supplier base, with the top three firms commanding roughly 38.45 percent of market revenue and the top five accounting for approximately 52.12 percent. This concentration level indicates a market where scale, technical capability, and regulatory compliance create meaningful barriers to entry, yet leaves sufficient room for specialized producers to capture niche premiums. Understanding the positioning of leading companies is therefore central to any sourcing or competitive strategy.
PMX Industries LLC, headquartered in Cedar Grove, Wisconsin, produces high-performance phosphor bronze strip, foil, and wire tailored for electrical connectors, springs, and contacts. The company's recent expansion of phosphor bronze production lines reflects a deliberate response to growing demand for connector-grade wire, signaling capacity readiness for electrical application growth. Materion Corporation, based in Mayfield, Ohio, supplies ToughMet and standard phosphor bronze alloys in wire form for demanding electrical and mechanical applications. Its introduction of an enhanced phosphor bronze wire grade with improved fatigue resistance for automotive applications illustrates how incremental metallurgical innovation can unlock new specification opportunities and deepen customer lock-in.
Aviva Metals, operating from Houston, Texas, offers phosphor bronze C51000, C52100, and C52400 in wire and rod forms for bushings, bearings, and fasteners. This grade-specific portfolio positions the firm as a reliable source for mechanical load-bearing components. Cadi Company Inc., located in Bristol, Connecticut, manufactures and distributes phosphor bronze wire for springs, clips, and electrical components, emphasizing distribution agility and broad temper availability. Belmont Metals Inc., in New York, produces phosphor bronze alloys including wire grades for jewelry, hardware, and precision instruments, serving lower-volume but specification-sensitive markets where surface quality and consistency are decisive.
International producers extend the competitive frontier across key industrial regions. Wieland Group, headquartered in Ulm, Germany, is a global producer of phosphor bronze strip and wire for automotive connectors and electronics, leveraging European engineering standards and cross-border distribution networks. Mitsubishi Materials Corporation, based in Tokyo, manufactures high-strength phosphor bronze wire for relays, switches, and semiconductor equipment, aligning product development with precision electrical manufacturing requirements. Furukawa Electric Co., Ltd., also in Tokyo, develops phosphor bronze alloy wires for high-conductivity electrical applications, emphasizing performance optimization in conductive pathways. In China, Ningbo Jintian Copper Co., Ltd. stands as a leading producer of phosphor bronze wire for enameled wire, springs, and hardware, and recently achieved ISO 14001 recertification for its phosphor bronze wire manufacturing facilities, reinforcing environmental management credibility. Shanghai Metal Corporation supplies custom phosphor bronze wire in various tempers and diameters for industrial uses, catering to bespoke specification requests across diversified end markets.
Beyond individual company profiles, recent industry movements reveal strategic priorities that buyers should monitor. Capacity expansions in response to connector demand, product launches targeting fatigue-resistant automotive grades, and environmental certification renewals all signal where suppliers are placing bets on future demand. These moves interact with raw material conditions, such as the LME Grade A copper price averaging 8,720 USD per metric ton in 2023, and the global refined copper market's supply deficit of 103,000 tons during the same year. Tariff structures, including the 25 percent Section 301 tariffs on phosphor bronze wire imports from China under HTS 7408.11, further complicate cross-border sourcing arithmetic. Regulatory frameworks such as RoHS Directive 2011/65/EU compliance for EU electrical wire applications and the ASTM B139-23 standard updates for phosphor bronze strip and wire forms add additional layers of qualification rigor. Together, these forces shape a competitive environment where technical compliance, cost management, and supply assurance must be evaluated as an integrated package.
Worldwide Phosphor Bronze Wire Market
Strategic Implications for Sourcing, Investment, and Risk Management
For enterprises operating in or adjacent to the phosphor bronze wire value chain, the 2026 outlook demands a shift from reactive procurement to anticipatory strategy. Several implications emerge from the market architecture and competitive dynamics outlined above.
- Grade-Specific Sourcing Strategy: Because demand is distributed across multiple alloy grades and applications, blanket purchasing agreements often leave buyers exposed to grade-specific shortages or price premiums. Aligning procurement contracts with anticipated grade demand, temper requirements, and diameter tolerances enables more stable pricing and reduces qualification friction.
- Regional Diversity in Supply Base: The geographic distribution of both demand and production suggests that overreliance on a single sourcing corridor increases vulnerability to tariff shifts, logistics disruptions, and local regulatory changes. A diversified supplier portfolio, balanced across regions with complementary capabilities, strengthens continuity and negotiating leverage.
- Compliance as a Competitive differentiator: Environmental directives, hazardous substance limits, and updated material standards are no longer peripheral concerns. Suppliers that maintain robust compliance documentation and certification trajectories reduce downstream validation risk for buyers in regulated electrical and automotive markets. Evaluating compliance maturity alongside price and lead time yields more resilient sourcing decisions.
- Capacity Timing and Inventory Buffering: The projected 2027 plateau followed by renewed growth indicates that capacity and inventory planning should account for non-linear demand paths. Building flexible inventory buffers during periods of anticipated easing, and tightening commitments ahead of known demand surges, can improve working capital efficiency while preserving supply assurance.
- Technical Partnership Over Transactional Purchasing: As specification requirements become more stringent and qualification cycles lengthen, suppliers that provide metallurgical support, custom temper development, and consistent diameter control become strategic partners rather than commodity vendors. Investing in relationships with technically capable producers can reduce total cost of ownership even when unit prices are not the lowest.
These implications are not abstract. They translate directly into contract structures, supplier qualification checklists, inventory policies, and capital allocation priorities. The report translates these strategic themes into actionable frameworks, enabling procurement, engineering, and finance teams to align on a coherent market engagement model.
What the Full Report Delivers
This preview establishes the macro context and competitive architecture that frame the phosphor bronze wire market entering 2026. The complete Worldwide Phosphor Bronze Wire Market research builds on this foundation with operational depth designed for immediate decision support. The report provides detailed segment mapping across regions, alloy grades, and applications, accompanied by historical trajectory analysis and forward-looking forecasts that account for raw material price sensitivity, tariff exposure, and regulatory compliance pathways. It includes competitive benchmarking that situates key producers within capability matrices, recent development timelines, and strategic positioning assessments. Additional modules address supply chain structure, pricing dynamics, substitution risk, and scenario modeling that stress-tests demand under varying raw material and trade policy conditions.
The objective of the full study is to convert market complexity into executable intelligence. Whether the priority is securing reliable supply for electrical connector programs, evaluating capacity investment in specific alloy grades, assessing tariff exposure in cross-border procurement, or benchmarking competitor moves in automotive and electronics applications, the report provides the structured evidence base required to move from intuition to informed action.
Moving from Context to Concrete Intelligence
The worldwide phosphor bronze wire market is entering a phase where growth, specification complexity, and regulatory scrutiny converge. Aggregate expansion toward a 1426.88 million USD valuation by 2032, supported by a 4.5 percent CAGR, masks a detailed landscape of grade-specific demand, regional supply asymmetries, and competitive concentration that will decisively influence sourcing outcomes and investment returns. Companies that treat this environment as a commodity exercise will encounter avoidable friction. Those that internalize the structural dynamics early will position themselves to secure preferred grades, manage compliance risk, and align capacity with genuine demand signals.
For executives and analysts preparing 2026 plans, the strategic imperative is clear: integrate market architecture, competitive behavior, and regulatory context into a single decision framework. The complete report delivers that framework with the segment-level precision, forecast discipline, and competitive mapping necessary to act confidently. Detailed regional splits, application-specific revenue paths, grade-level demand trajectories, and full competitive profiles are available in the full publication, where the depth of analysis matches the complexity of the decisions at hand.
For detailed analysis of this topic, please visit the official page: Worldwide Phosphor Bronze Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com