

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Horse Alfalfa Feed Market Hits $8.51B in 2025, to Reach $12.6B by 2032

Strategic Intelligence for the Equine Nutrition Sector: Navigating the Global Alfalfa Feed Market 2026–2032
The global equine nutrition landscape is entering a decisive phase. As horse ownership stabilizes in mature markets and expands in emerging economies, the demand for premium alfalfa feed—a cornerstone of high-performance equine diets—is being reshaped by intersecting forces: climate-driven water constraints, rising input costs, shifting distribution channels, and a competitive landscape that rewards scale, traceability, and consistent quality. For executives, procurement leaders, and investment strategists operating in the animal nutrition and agri-commodity space, generic industry narratives no longer suffice. What is required is a rigorously validated, forward-looking intelligence framework that translates macro trends into actionable commercial decisions.
Our latest Worldwide Alfalfa Feed for Horse Market study delivers precisely that framework. Spanning historical performance from 2020 through 2025 and projecting forward to 2032, this research integrates verified market sizing, structural segmentation, competitive benchmarking, and regulatory risk mapping into a single decision-grade asset. The following overview outlines the strategic architecture of the report, highlights the operational intelligence it contains, and demonstrates why 2026 represents a critical inflection point for stakeholders who must anticipate rather than react to market shifts.
Why 2026 Is a Defining Year for Alfalfa Feed Strategy
The market has already crossed a significant threshold. Total revenue for alfalfa feed designated for horse applications reached approximately US$8,510.0 million in 2025, reflecting sustained growth from a 2020 baseline of roughly US$6,450.3 million. The trajectory through the forecast horizon points to continued expansion, with a projected compound annual growth rate of 5.8 percent, propelling the market toward US$12,627.8 million by 2032. These figures are not abstract statistics; they represent a compounding shift in procurement expectations, supply chain complexity, and regional rebalancing that will directly impact pricing power, inventory strategy, and channel partnerships over the next seven years.
Yet the headline numbers only tell part of the story. The real strategic challenge lies in understanding how growth is distributed across product formats, distribution pathways, and geographic corridors—and how structural pressures such as water allocation reforms, input cost inflation, and consolidation dynamics will alter the competitive advantage of individual players. This report is designed to surface those leverage points without obscuring them behind aggregations that mask operational reality.
What the Research Delivers: Operational Intelligence for Executive Decision-Making
Built for professionals who need to translate market signals into procurement schedules, capacity planning, and partner selection, the study provides a multi-layered view of the alfalfa feed ecosystem. Rather than stopping at top-line projections, the analysis maps the structural components that determine margin viability, supply resilience, and market access.
The report examines the market across three primary analytical dimensions:
Worldwide Alfalfa Feed for Horse Market
- Product form architecture , capturing how different physical formats align with end-user feeding programs, storage constraints, transport economics, and premium pricing tolerance.
- Distribution channel pathways , detailing where commercial transactions are concentrated, how procurement behavior differs across direct bulk trade, specialty retail, and digital platforms, and what this means for channel-specific margin structures.
- Regional demand and supply geometry , identifying where consumption intensity is highest, how production hubs are positioned relative to end markets, and which corridors face the greatest exposure to climate and regulatory disruption.
Each dimension is supported by historical baselines, forward-looking scenario logic, and structural indicators that reveal how market share is shifting among formats and channels. The analysis deliberately avoids static snapshots; instead, it connects the behavior of buyers, the economics of producers, and the constraints of logistics networks into a coherent narrative that executives can use to stress-test assumptions.
Beyond structural mapping, the research embeds practical tools for day-to-day strategic planning. These include:
Alfalfa Hay Market
- Cost-structure references that frame the production economics of alfalfa, helping procurement and finance teams evaluate supplier quotes against prevailing input conditions and regional yield realities.
- Channel-entry considerations that clarify where growth is most accessible, where competition is most intense, and how branding, certification, and consistency requirements differ by customer segment.
- Supply-risk lenses that link water availability, irrigation policy, and land-use trends to expected output variability, enabling more resilient sourcing strategies across multiple harvest cycles.
The result is a report that functions as both a strategic compass and an operational reference. It is structured so that teams can move quickly from high-level market context to specific questions about sourcing, positioning, and expansion without losing analytical rigor.
Competitive Dynamics: Scale, Specialization, and the New Rules of Differentiation
The alfalfa feed for horse market is not a monolith of undifferentiated commodity trading. It is a space where consistency, quality grading, traceability, and geographic positioning matter profoundly. Buyers—whether managing elite equine facilities, specialty retail chains, or international distribution networks—increasingly demand predictability in fiber length, moisture content, nutritional profile, and freedom from contaminants. That reality has elevated the strategic importance of producers and exporters who can combine scale with a demonstrable quality narrative.
The competitive landscape reflects this tension. Large-scale producers and exporters such as Anderson Hay & Grain Co., Inc., Standlee Premium Products, LLC, Al Dahra ACX Global Inc., and Bailey Farms International anchor significant portions of the trade through established export channels, consistent baling and pelleting capabilities, and distribution relationships that span retail and international procurement. Alongside them, specialized suppliers such as Green Prairie International Inc., Cubeit Hay Company, Barr-Ag Ltd., Riverina (Australia) Pty Ltd., and SL Follen Company reinforce the premium and non-GMO segments with offerings that emphasize fiber integrity, regional branding, and equine-specific formulations. European players including Alfalfa Monegros, S.L. and Grupo Osés extend the geographic breadth of quality supply, particularly for thoroughbred and high-performance equine markets. Border Valley Trading and Oxbow Animal Health further illustrate how export-grade consistency and species-tailored formulations continue to carve out defensible market positions.
What distinguishes the leaders is not merely volume, but the ability to align product architecture with channel expectations. Suppliers that can reliably deliver clean, consistent bales alongside pellets, cubes, and chaff formats are better positioned to serve mixed feeding programs and to navigate the preferences of both direct bulk buyers and specialty retail accounts. The report maps these competitive postures in detail, examining how brand positioning, product mix, geographic footprint, and channel relationships interact to shape share stability and growth optionality.
Recent industry developments underscore how quickly operational advantage can be created or eroded. In April 2025, DLF opened specialized Product Knowledge Centers in Philomath, Oregon, and Port Hope, Ontario, highlighting seed and forage innovations with direct implications for equine applications. Earlier, in January 2025, Norden Manufacturing introduced the Norden AlfaTed reel-style tedder, a machinery advancement designed to help farmers preserve hay quality before baling. These moves may appear narrow in isolation, but they reflect a broader pattern: the market is increasingly rewarding technical precision, quality assurance, and process reliability at every stage of the value chain. The study places such developments into a competitive context, helping readers assess which innovations are likely to translate into durable commercial advantage and which are more likely to be absorbed into baseline expectations.
Structural Pressures Reshaping Supply and Pricing Logic
Any credible strategy for the alfalfa feed market must account for the forces that are altering the cost and availability of supply. Two clusters of pressure stand out: input economics and water governance.
On the cost side, university cost-of-production studies compiled through the American Farm Bureau Federation indicate that full economic costs for alfalfa production have ranged from approximately $165 to more than $300 per ton, depending on irrigation intensity, with an average near $229 per ton across major U.S. states. Input expenses—water, fertilizer, labor, fuel, and machinery—have climbed between 20 and 35 percent since 2020, even as average yields have remained close to 3.5 tons per acre. For procurement leaders, this environment means that historical price assumptions can no longer be extrapolated without adjustment. The report incorporates these economics as a reference frame, helping teams evaluate whether supplier pricing reflects region-specific cost realities, whether alternative sourcing corridors can mitigate exposure, and how product form choices may influence total landed cost.
On the regulatory and resource side, water constraints are becoming one of the most consequential variables in alfalfa supply planning. California's Sustainable Groundwater Management Act mandates basin-level pumping reductions by 2040, with interim allocations already producing 20 to 30 percent cuts in irrigation deliveries in critically overdrafted sub-basins. In Arizona, the groundwater-management framework has restricted new irrigation permits in Phoenix and Tucson Active Management Areas, while the state's Colorado River water share has declined by more than 1 million acre-feet, contributing to an estimated 12 percent contraction in alfalfa acreage between 2023 and 2025. Deficit irrigation programs in California and the Imperial Valley have further reduced water allotments by 25 to 50 percent in some areas, directly affecting output available for feed markets.
These are not distant risks. They are active determinants of where alfalfa can be grown economically, how reliable annual harvests will be, and how pricing power will be distributed between producers and buyers. The study integrates these dynamics into a region-and-dynamics framework that allows decision-makers to see where supply vulnerability is most acute, how it may affect product availability across forms and channels, and what strategic responses—such as contract structuring, geographic diversification, or inventory buffering—are most appropriate for different operating models.
Concentration, Channel Evolution, and the Strategic Value of Granular Intelligence
Market structure matters as much as market size. The alfalfa feed for horse market is moderately fragmented at the top, with a CR3 of 18.5 percent and a CR5 of 26.4 percent. This concentration profile suggests that while no small group of firms dominates the entire market, a manageable set of leading suppliers exerts meaningful influence over certain channels, regions, and product categories. For competitors, this creates both opportunity and risk: there is room to differentiate and grow, but the path is shaped by the procurement standards, channel relationships, and quality expectations set by the most established players.
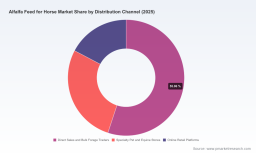
Distribution is equally instructive. The market is not flowing through a single dominant pipeline. Direct sales and bulk forage trading represent a substantial share of commercial activity, reflecting the importance of large-scale procurement relationships and logistical efficiency. At the same time, specialty pet and equine stores, along with online retail platforms, continue to expand their role, driven by end-user demand for convenience, branded quality, and detailed product information. The report examines how these channels differ in margin dynamics, customer expectations, and growth trajectory, providing a basis for decisions about where to invest, where to partner, and where to defend.
Product form preferences further complicate the picture. Different formats serve different feeding programs, storage conditions, and transport economics, which means that growth is not uniform across the portfolio. Some formats benefit from premium positioning and targeted retail demand, while others are optimized for bulk handling and large-scale equine operations. Understanding how these segments interact—and how input and water pressures may shift the relative attractiveness of each form—is essential for anyone planning capacity, pricing, or product development.
This is precisely the level of granularity that generic industry summaries fail to provide. Our report keeps the focus on the operational questions that determine outcomes: which channels offer the most defensible growth, which product forms align with shifting buyer requirements, which regions face the greatest supply volatility, and how leading competitors are adapting their portfolios and export strategies in response.
How to Use This Research for 2026 Decision-Making
The study is designed to support a wide range of strategic use cases. Procurement teams can use the cost-structure references and regional supply analysis to refine sourcing strategies, evaluate contract terms, and anticipate price behavior under varying input and water conditions. Commercial leaders can use the channel and product-form analysis to prioritize market-entry efforts, shape product positioning, and allocate sales resources toward the most responsive customer segments. Competitive intelligence teams can use the company profiles and recent development tracking to benchmark peer strategies, identify partnership opportunities, and monitor moves that may signal shifts in quality standards or export capability. Investors and corporate development groups can use the market trajectory and concentration profile to assess growth optionality, consolidation potential, and sector resilience across the forecast period.
Most importantly, the research is structured to reduce uncertainty in the decisions that matter most in 2026: whether to expand into new channels, how to hedge against supply-side volatility, which product formats deserve investment attention, and which competitors are building durable advantages versus those that are merely riding short-term demand.
Access the Complete Strategic Briefing
The overview above captures the analytical architecture and strategic intent of the Worldwide Alfalfa Feed for Horse Market study, but the full value lies in the detailed segmentations, regional demand mappings, channel economics, competitive benchmarking, and scenario-aware projections that support each conclusion. While this introduction highlights the framework and the forces shaping the market, the complete report provides the segment-level evidence, company-level comparisons, and operational references needed to convert insight into execution.
To explore the full dataset, regional breakdowns, distribution-channel dynamics, and the complete competitive landscape, we invite you to access the full report through our official publication portal. The complete intelligence package is designed to serve as the foundational reference for 2026 planning cycles and beyond, giving your team the clarity required to act with confidence in a market where quality, water, cost, and channel strategy are increasingly inseparable.
For detailed analysis of this topic, please visit the official page: Worldwide Alfalfa Feed for Horse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com