

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Fecal Occult Testing Market to Reach $2.25B by 2032 at 5.96% CAGR

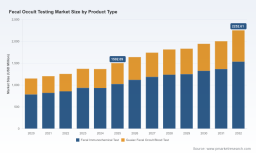
Strategic Intelligence for the Next Horizon: Navigating the Fecal Occult Testing Market 2026-2032
In an era where early detection defines patient outcomes and operational efficiency dictates healthcare viability, the landscape of gastrointestinal screening is undergoing a profound transformation. As we stand at the threshold of 2026, clinical stakeholders, diagnostic manufacturers, and investment strategists require more than a snapshot of current performance. They need a high-resolution roadmap that illuminates where growth will materialize, which regulatory shifts will reshape demand, and how competitive dynamics will consolidate or fragment market share.
PW Consulting is pleased to introduce our newly released Worldwide Fecal Occult Testing Market research, a comprehensive analytical instrument designed specifically to empower data-driven decision-making across the next seven-year forecast window. This briefing article outlines the strategic architecture of the study, demonstrates its immediate relevance to enterprise planning, and reveals why this intelligence asset has become indispensable for organizations positioning themselves in the colorectal cancer screening and gastrointestinal diagnostics ecosystems.
The Macro Trajectory: A Foundation for Strategic Planning
The global market for fecal occult testing has demonstrated remarkable resilience and sustained expansion across the historical evaluation period, reflecting broader shifts toward value-based care, preventive screening mandates, and the clinical migration from invasive endoscopic procedures to convenient, high-sensitivity stool-based assays. Base-year assessments establish a revenue baseline that has been consistently augmented by adoption of immunochemical methodologies, expanded reimbursement pathways, and the deployment of automated laboratory platforms capable of processing high volumes with minimal manual intervention.
Looking forward, the forecast horizon through 2032 projects a compound annual growth rate of 5.96 percent, culminating in a market valuation that substantially exceeds the 2.25 billion USD threshold. This trajectory is not speculative; it is anchored in observable adoption curves, demographic tailwinds from aging populations in developed and emerging markets alike, and the structural integration of fecal occult blood screening into national and regional cancer prevention programs. For executive teams, these figures represent more than revenue potential. They signal sustained demand elasticity, procurement continuity, and long-term capacity requirements that must be factored into capital allocation, R&D prioritization, and supply chain strategy.
Worldwide Proctoscope Market
The historical sequence from 2020 through 2025 reveals nuanced inflection points, including periods of market recalibration and consolidation, which our analysis deconstructs to identify the underlying operational, regulatory, and reimbursement variables that shaped performance. Understanding these patterns equips leaders with predictive sensitivity, enabling them to stress-test their portfolios against analogous future disruptions.
What the Study Delivers: Architecture of Actionable Intelligence
This market research was engineered to bridge the gap between high-level market commentary and the granular, operationally relevant data that strategists require. Rather than providing generic overviews, the study dissects the ecosystem through multiple analytical lenses, each calibrated to support distinct decision-making functions:
- Product-Type Stratification: The analysis segments the market into fecal immunochemical testing and guaiac-based fecal occult blood methodologies, mapping adoption trends, clinical preference shifts, automation compatibility, and diagnostic sensitivity advantages that are reshaping procurement specifications across screening programs and clinical laboratory networks.
- End-User Utilization Frameworks: Demand is examined across diagnostic laboratories, hospital systems, and clinics with supplementary care pathways, revealing differences in procurement cycles, volume thresholds, automation investment behavior, and the operational drivers that influence test selection and vendor consolidation.
- Geographic Deployment Insights: Regional performance is evaluated to uncover localized reimbursement maturity, screening guideline alignment, infrastructure readiness, and the competitive intensity that characterizes each major market zone. The report isolates the structural factors that explain variance in growth velocity and adoption depth without reducing complex regional dynamics to superficial summaries.
- Competitive Positioning and Benchmarking: A rigorous evaluation of the market's leading participants provides a view into product portfolio strategies, technological differentiation, automation integration, geographic expansion tactics, and the corporate maneuvering that shapes market concentration and competitive advantage.
- Regulatory and Reimbursement Context: The study embeds critical policy intelligence, including classification requirements, screening authorization parameters, and coverage frameworks that govern commercial viability, ensuring that strategic recommendations align with the operational realities of compliance and reimbursement navigation.
Competitive Landscape: Structural Dynamics Among Key Players
The fecal occult testing arena is characterized by a blend of established diagnostic conglomerates, specialized screening innovators, and regional manufacturers that collectively define market rhythm. Our analysis highlights a concentration profile in which the top three industry participants account for approximately 42.5 percent of total revenue, and the top five collectively represent 58.8 percent. This concentration level signals a mature competitive environment where scale, automation capability, regulatory clearances, and clinical evidence portfolios serve as critical moats.
Leading organizations such as Polymedco CDP, LLC continue to advance fecal immunochemical testing solutions anchored in automated analyzers and sampling systems supported by robust clinical evidence, reinforcing the shift toward high-throughput, standardized screening workflows. Beckman Coulter, Inc., operating under the Danaher umbrella, maintains a strong presence through guaiac-based detection systems alongside immunoassay alternatives, offering diversified testing modalities that serve both traditional and evolving screening protocols. Eiken Chemical Co., Ltd. has reinforced its position through the supply of FIT reagents and automated fecal occult blood analyzers designed for accuracy and reliability, aligning closely with national screening initiatives that prioritize consistent quantitative output.
QuidelOrtho Corporation broadens the point-of-care and professional diagnostic footprint with rapid testing offerings, while Abbott Laboratories integrates immunoassay-based fecal occult blood detection into wider clinical diagnostics ecosystems, creating cross-portfolio value for healthcare networks managing gastrointestinal and cancer screening pathways. Sentinel Diagnostics contributes to the immunochemical segment through FOB Gold and compatible quantitative hemoglobin detection platforms optimized for automated laboratory instrumentation. Biohit Oyj delivers the ColonView quick test for simplified professional detection, addressing settings where streamlined workflows and rapid triage are prioritized. Sysmex Corporation advances high-throughput laboratory screening through automated fecal immunochemical testing systems and reagents, reinforcing the infrastructure backbone that large-volume diagnostic networks depend upon.
In the rapid test and distributed supply segment, Alfa Scientific Designs, Inc., CTK Biotech, Inc., Certest Biotec S.L., and Jant Pharmacal Corporation serve point-of-care, over-the-counter, and grassroots screening applications through lateral flow, immunochromatographic, and distributed rapid device formats. This diverse participant ecosystem illustrates how the market balances centralized laboratory scale with decentralized accessibility, a duality that shapes channel strategy, distribution partnerships, and product development priorities.
Recent corporate activity further underscores market dynamism. During 2025, Geneoscopy achieved regulatory clearances for improved stool collection kits supporting its multi-target stool RNA test, including occult hemoglobin detection components, simplifying at-home colorectal cancer screening workflows. Separately, Premera launched an in-home test kit program incorporating FIT kits for eligible members beginning in May 2025. These developments highlight the convergence of at-home convenience, molecular and immunochemical screening innovation, and payer-driven accessibility, signaling that future competitive advantage will be built on user experience, specimen integrity, and integration with payer and provider screening networks.
Market Dynamics: The Forces Shaping Commercial Reality
Market growth in this sector cannot be understood through product preference alone. It is fundamentally shaped by reimbursement policy, regulatory classification, and clinical authorization boundaries that determine which tests can be deployed, for whom, and under what economic conditions.
Reimbursement frameworks remain a decisive growth lever. Coverage for fecal occult blood testing under Medicare Part B reflects long-standing recognition of screening value for eligible beneficiaries, with immunoassay pathways supported under defined coding structures for simultaneous testing scenarios. In 2025, policy updates within the CMS Physician Fee Schedule refined colorectal cancer screening test provisions and adjusted laboratory service requirements for rural health clinics, expanding access pathways and influencing procurement patterns in underserved and decentralized care settings. These reimbursement mechanics directly impact test utilization, lab volume forecasting, and the commercial attractiveness of specific assay formats across different care environments.
Regulatory discipline imposes equal strategic significance. Fecal occult blood devices fall under defined classification parameters for the detection of occult blood in feces as an aid in diagnosing gastrointestinal disorders. Devices marketed specifically for colorectal cancer screening require appropriate premarket authorization or substantial equivalence clearance with validated performance in screening populations. Importantly, devices cleared solely for gastrointestinal disorder detection are not authorized for colorectal cancer screening indications without additional evaluation and clearance. This regulatory distinction shapes product labeling, marketing claims, clinical adoption, and the development commitments required to expand indication scope. For organizations planning product extensions, geographic entry, or indication expansion, this environment demands precise alignment between test design, clinical validation, and regulatory submission strategy.
Why This Research Matters for 2026 Decision-Making
Entering 2026, enterprises operating in or adjacent to the fecal occult testing ecosystem face a set of interdependent strategic challenges. Demand is expanding, but growth is uneven across regions and care settings. Automation is accelerating, yet procurement cycles vary widely between centralized laboratories and decentralized clinic networks. Regulatory boundaries are clear but require careful navigation, especially for manufacturers seeking to distinguish screening-use claims from general gastrointestinal detection applications. Reimbursement adjustments continue to reshape volume flows, particularly in rural and community-based settings where access policy evolution has direct financial implications.
Our research translates these complexities into structured guidance. It enables organizations to:
- Evaluate market sizing and forecast trajectories with a transparent methodology that supports capacity planning, investment prioritization, and long-horizon scenario modeling.
- Understand how product-type preferences are evolving between immunochemical and guaiac-based formats, and what that implies for R&D focus, portfolio balance, and channel strategy.
- Assess end-user demand patterns across diagnostic laboratories, hospitals, and clinics, revealing where volume concentration, automation investment, and vendor consolidation are most likely to intensify.
- Benchmark competitive positioning against the full roster of incumbent and emerging players, identifying gaps in automation, indication coverage, geographic reach, and clinical evidence that can be exploited or defended.
- Integrate reimbursement and regulatory intelligence into commercial planning, ensuring that market entry, expansion, and messaging strategies remain compliant and economically viable.
Crucially, the study is designed to serve both strategic planners and tactical execution teams. For corporate development and investor relations, it offers a defensible market narrative supported by forecast logic and structural analysis. For product, marketing, and regulatory leaders, it provides context for positioning decisions, indication strategy, and channel optimization. For procurement and operations stakeholders, it sheds light on end-user behavior and the competitive pressure points that influence supply specifications and partnership requirements.
Worldwide Fecal Occult Testing Market
The Strategic Case for Complete Intelligence
High-level summaries can indicate that a market is growing. They cannot reveal the interplay of regulatory constraints, reimbursement evolution, automation adoption, and competitive concentration that determines who captures value and how. The Worldwide Fecal Occult Testing Market report from PW Consulting delivers the analytical depth required to move beyond surface-level trends and into precision-targeted decision-making.
The complete study includes detailed revenue estimates, segmentation breakdowns, regional performance distributions, end-user adoption profiles, competitive profiling, and scenario-ready forecast structures that support internal planning and external stakeholder communication. Organizations that rely solely on headline figures risk misallocating resources, misreading competitive vulnerability, or underestimating the operational implications of regulatory and reimbursement change. Those that engage with the full research foundation are positioned to anticipate demand shifts, align product and commercial strategy with policy reality, and execute with greater confidence across the market's evolving segments.
As screening programs expand, automation becomes a baseline expectation, and at-home and molecular-adjacent innovations continue to influence consumer and provider expectations, the need for rigorous market intelligence will only intensify. PW Consulting designed this research to serve as a strategic compass: clarifying where growth is structurally supported, where competitive pressure is intensifying, and where regulatory and reimbursement conditions will open or close commercial pathways.
For decision-makers preparing for 2026 and the forecast years that follow, the complete intelligence package provides the evidentiary foundation necessary to convert market momentum into sustainable strategic advantage. Detailed segmentation data, comprehensive regional analysis, and full competitive profiling are presented in the report to support the depth of insight your organization requires. We invite you to access the full study to obtain the complete data architecture and analytical content behind this overview, ensuring that your strategic planning rests on the full breadth of available intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Fecal Occult Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com